
Article
Align Your Off-The-Plan Build Timeline With Key Finance Milestones
A practical Australian guide to matching your off‑the‑plan build stages with finance milestones so you don’t get caught short at valuation, approval or settlement.
Key Takeaway
Aligning an off-the-plan build timeline with finance milestones means mapping the developer’s estimated build stages to key funding checkpoints: initial assessment, mid-build review, final valuation and unconditional approval. Because banks usually reassess your position 4–8 weeks before settlement and apply a 3% serviceability buffer, buyers should hold 3–6 months of repayments in cash, refresh pre-approvals every 3–6 months, and run worst-case valuations early. This article outlines a practical, date-based checklist you can implement this week.
This topic is covered in full on Tailored Loans Sydney
A practical Australian guide to matching your off‑the‑plan build stages with finance milestones so you don’t get caught short at valuation, approval or settlement.
Read the full guide on tailoredloans.sydneyAligning your build timeline with your finance milestones means mapping every major construction stage to a specific funding check: deposit, pre‑approval refreshes, valuation, and final approval before settlement. If you’re buying off‑the‑plan or building with a 1–3 year horizon, you can’t just get one pre‑approval and hope for the best. You need a dated plan that survives rate rises, policy changes and valuation surprises.
Use this guide to build that plan this week.
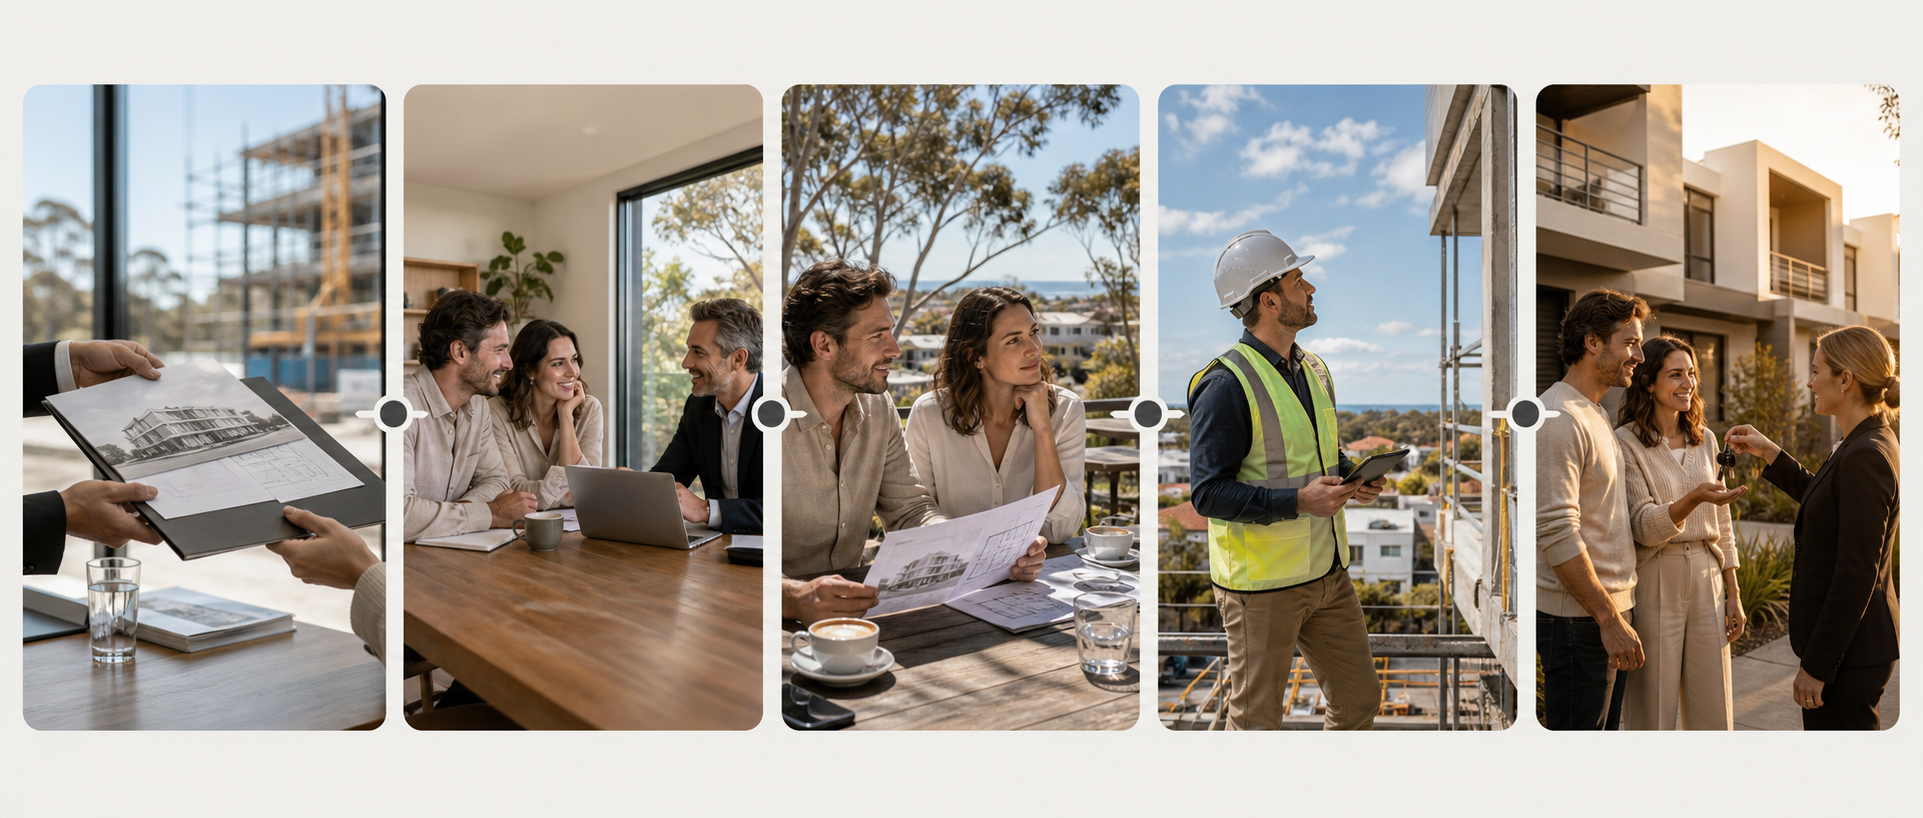
1. The core problem: your build moves slowly, lenders move fast
Why timing is different for off‑the‑plan
With off‑the‑plan, your contract might be signed today, but:
- The bank will usually re‑assess your full situation 4–8 weeks before settlement, not just rely on an old pre‑approval.
- APRA expects banks to test you at ~3% above the actual rate, so serviceability can fail even if your income hasn’t changed.
- The final loan is based on the valuer’s figure at settlement, not your contract price.
That’s why standard pre‑approvals often fail for off‑the‑plan. You must keep finance “fresh” and aligned to the build.
If you haven’t already, pair this with the more detailed buyer’s timeline in Your Off‑the‑Plan First Home: A Simple Settlement Timeline.
Typical off‑the‑plan vs lender timeline
| Stage | Build / Contract Event | Finance Milestone | What You Should Do |
|---|---|---|---|
| Month 0 | Sign contract, pay deposit | Initial assessment | Confirm borrowing capacity, choose structure |
| Month 0–3 | Early construction / planning | First pre‑approval | Lock in lender policy snapshot, set buffers |
| Month 6–12 | Structure up, midway build | Pre‑approval refresh | Update income, debts, living costs |
| Month 12–24+ | Practical completion approaching | Final valuation ordered | Run worst‑case scenarios, address gaps |
| 4–8 weeks pre‑settlement | Settlement date issued | Unconditional approval | Freeze big financial moves until after settlement |
2. Build a date‑based finance map this week
Step 1: Lock in your best estimate of settlement
Start with the estimated practical completion and sunset dates in your contract. Developers often email updated target dates during the build – file them.
Create a one‑page timeline with:
- Contract date and deposit paid
- Developer’s current estimated completion date
- Sunset date (latest allowable completion)
- Your target settlement month (be conservative: add 2–3 months slippage)
This becomes your finance map, similar to the one‑page plan we use for clients across loans and properties (see the planning approach discussed in /insights/coordinating-accountant-broker-financial-planner-bronte-property-plan).
Step 2: Overlay finance milestones
On the same page, pencil in:
- Now: capacity check + provisional structure
- 3 months after contract: first formal pre‑approval
- Every 3–6 months until 6 months pre‑settlement: pre‑approval refresh
- 6–3 months pre‑settlement: dry‑run valuation and worst‑case scenarios
- 8–4 weeks pre‑settlement: final valuation + unconditional approval
Treat these dates like non‑negotiable appointments. They’re when you verify you still pass the bank’s tests.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.