
Article
How To Align Wills, Trust Deeds and Loans For Smooth Succession
Written and reviewed by James Chee, CPA · Last reviewed
A practical Australian guide to lining up your will, trust deeds and loan structures so properties, businesses and mortgages pass smoothly to the next generation without tax shocks or family conflict.
Key Takeaway
Australians can align wills, trust deeds and loan structures by first mapping who legally owns each asset, who owes each debt, and how those should change at death, then updating documents in one coordinated review. With 32.5% of borrowers already in mortgage stress, poorly planned inheritances can force distressed sales and tax problems. A joint meeting between lawyer, accountant and broker this week is a practical first step to simplify structures and avoid future disputes.
Watch the short answer
Using a family trust or company to hold investment assets
If you are weighing up how wills and trust deeds fit with your loans, this video shows how trusts and companies can hold your investments.
Read the transcript
Using a family trust or a corporate holding structure is brilliant for asset protection, but will instantly paralyse a standard retail bank manager. Their systems are built for simple PAYG slips. The moment an application involves interlocking entities, they panic. We build clean financial narratives that track your true entity cash flow, ensuring underwriters see your strength, not just your complexity. DM me 'STRUCTURE' to unlock your borrowing capacity.
General information only, not personal advice. Your situation is assessed before any recommendation.
Coordinating your will, trust deeds and loan structures means making sure your legal documents, ownership records and actual loans all tell the same story about who owns what, who owes what, and who is meant to benefit when you die. When they aren’t aligned, executors get stuck, beneficiaries argue, and valuable property is often sold under pressure just to untangle the mess.
This guide gives you a decision-grade, Australian-focused checklist you can act on this week with your lawyer, accountant and broker.
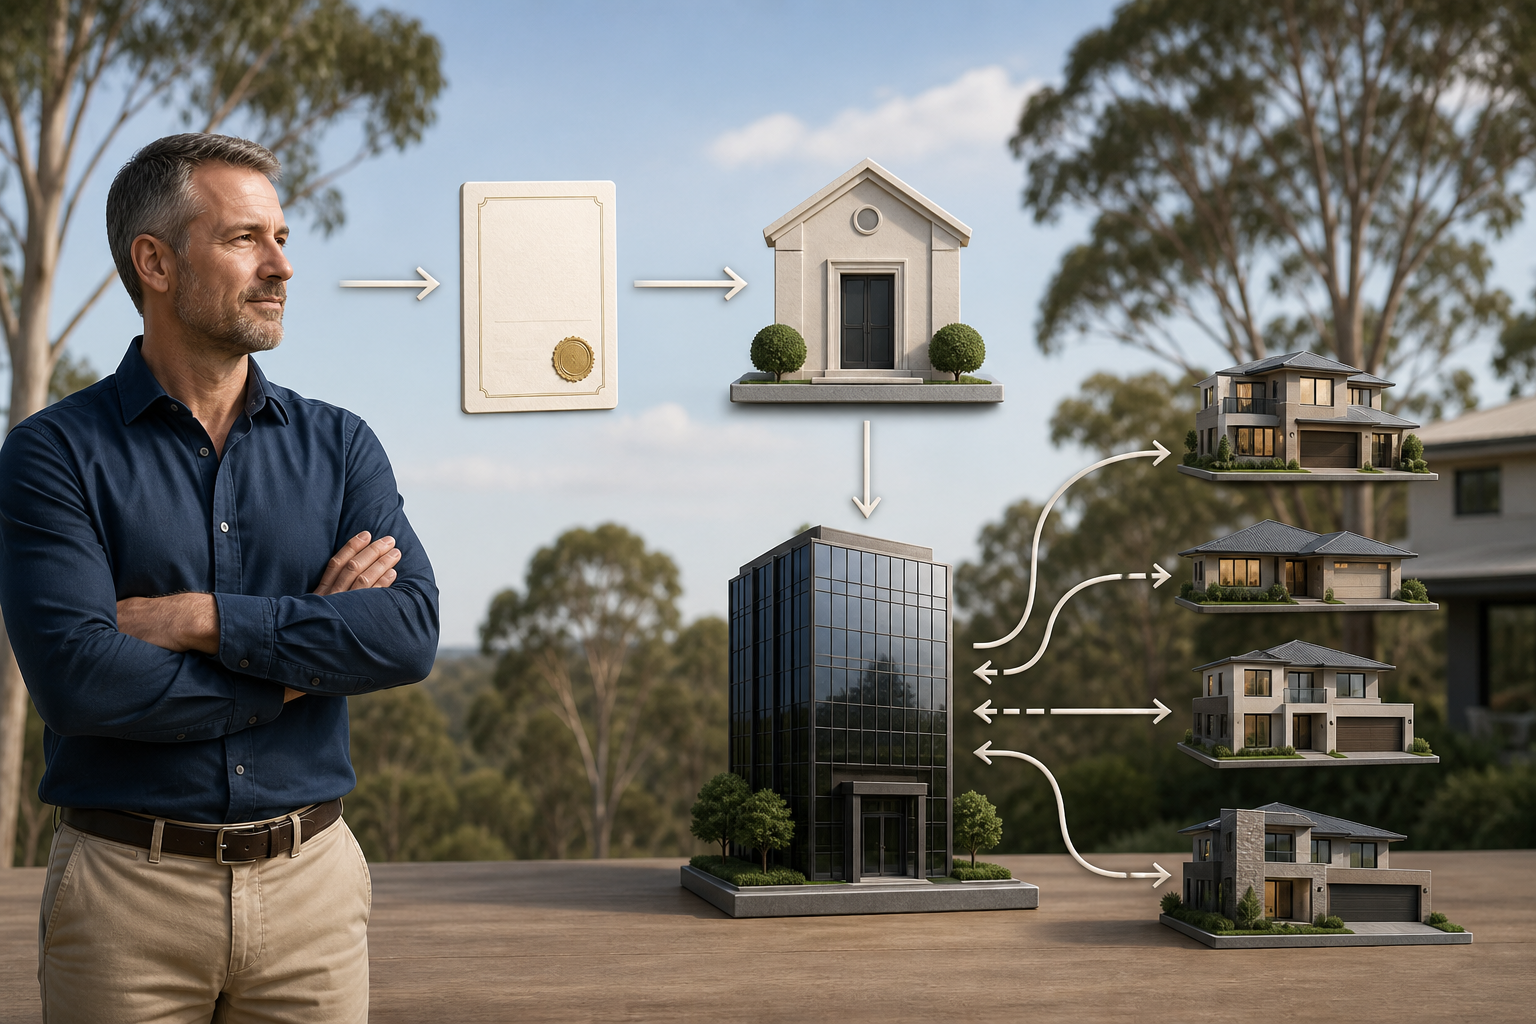
1. Start with a simple map: assets, entities and loans
Before you change documents, you need a one-page picture of your world.
1.1 List every asset and who owns it
Create a table with:
- Property and business interests (addresses, ABNs)
- Entity: personal name, joint, company, family trust, SMSF
- Estimated value and loan balance
Flag complexity: cross-collateralised loans, guarantors, or assets held via trusts or SMSFs. If you’re not sure whether a property is cross-collateralised, see the explanation in [/insights/cross-collateralisation-vs-standalone-loans-which-structure].
1.2 List every loan and who is liable
For each home, investment, business or SMSF loan, record:
- Borrower names and any guarantors
- Security property (or properties)
- Current limit and balance
- Repayment type (P&I vs interest-only)
The key is to see where ownership and loan liability do not match – for example, a spouse on the title but not on the loan, or a trust-owned property with personal guarantees.
1.3 Check your current will and trust deeds against the map
Now hold your will and trust deeds up against this map and ask:
- Does the will try to gift an asset that’s actually owned by a company or trust?
- Does it ignore large debts attached to ‘gifts’ of property or business interests?
- Do trust deeds and company constitutions allow the succession you’ve described in your will?
If the answer to any of these is “not really”, you’ve identified your first alignment job.
2. How wills, trusts and loans interact in practice
2.1 What your will actually controls
Your will mainly governs assets you personally own. It generally does not:
- Override trust deeds or company constitutions
- Deal with super or insurance with binding nominations directly to beneficiaries
So if most of your wealth sits in trusts, companies or super, your will is just one piece of the puzzle.
2.2 How trust deeds and company rules can override your intentions
Discretionary trust deeds and shareholder agreements decide:
- Who can be a beneficiary or shareholder
- Who controls the entity (appointor, trustee, director)
- How control passes on death
If your will leaves ‘the business’ to one child but the shareholder agreement passes control to another, the agreement usually wins. That’s where litigation risk and forced sales appear.
2.3 Loans that outlive you
Home and investment loans do not vanish on death. Typically:
- The estate keeps paying from rent, business income, cash or insurance; or
- Assets are sold to clear debt; or
- Beneficiaries refinance into their own names.
A coordinated plan should set out which of these you want for each major loan. Our article on protecting heirs with insurance and offsets digs deeper into those mechanics: [/insights/insurance-estate-planning-large-mortgage-australia].
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Property planning
How To Build Cash Buffers And Credit Limits That Actually Work
Property planning
Can Trade Finance Quietly Crush Your Home Loan Borrowing Power?
Property planning
How Australian SMEs Can Fund Stock Before Sale With Trade Finance
Property planning
Should Your Building Finance a Pool, Gym or EV Chargers?
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.