
Article
Smart ways to finance hospitality equipment without choking cashflow
Written and reviewed by James Chee, CPA · Last reviewed
A practical guide to financing kitchen equipment, point‑of‑sale systems and delivery vehicles for Australian cafés, restaurants and food operators, without strangling cashflow.
Key Takeaway
Australian hospitality businesses can finance kitchen equipment, POS systems and delivery vehicles using stand-alone equipment loans, leases and fit-out funding rather than stretching home loans, keeping total repayments within a safer 15–25% of realistic revenue. Terms typically range from 3–7 years for vehicles and heavy equipment and 3–5 years for technology, with lenders capping total asset age at 5–7 years for POS and 10–15 years for vehicles. The key is matching each loan’s term to asset life and cashflow, then comparing total dollars repaid before signing.
Watch the short answer
Can I get a home or business loan with a 12‑month-old business?
Working out how to fund fit‑out and equipment on young business cashflow? This video shows how lenders view 12‑month‑old trading.
Read the transcript
Started a wildly successful business 12 months ago? The bank still thinks you're a startup risk. The standard institutional rule is that you need 2 full years of ABN history to get a mortgage, but if your cash flow is booming right now, you shouldn't have to wait another 12 months to buy a house. At Local Knowledge Finance, we have access to specialist alt doc lenders who will approve your loan with just 6 to 12 months of ABN registration and clean bank statements. Your success shouldn't be penalised by arbitrary timelines. DM me the word 'BUSINESS' to bypass the 2-year rule.
General information only, not personal advice. Your situation is assessed before any recommendation.
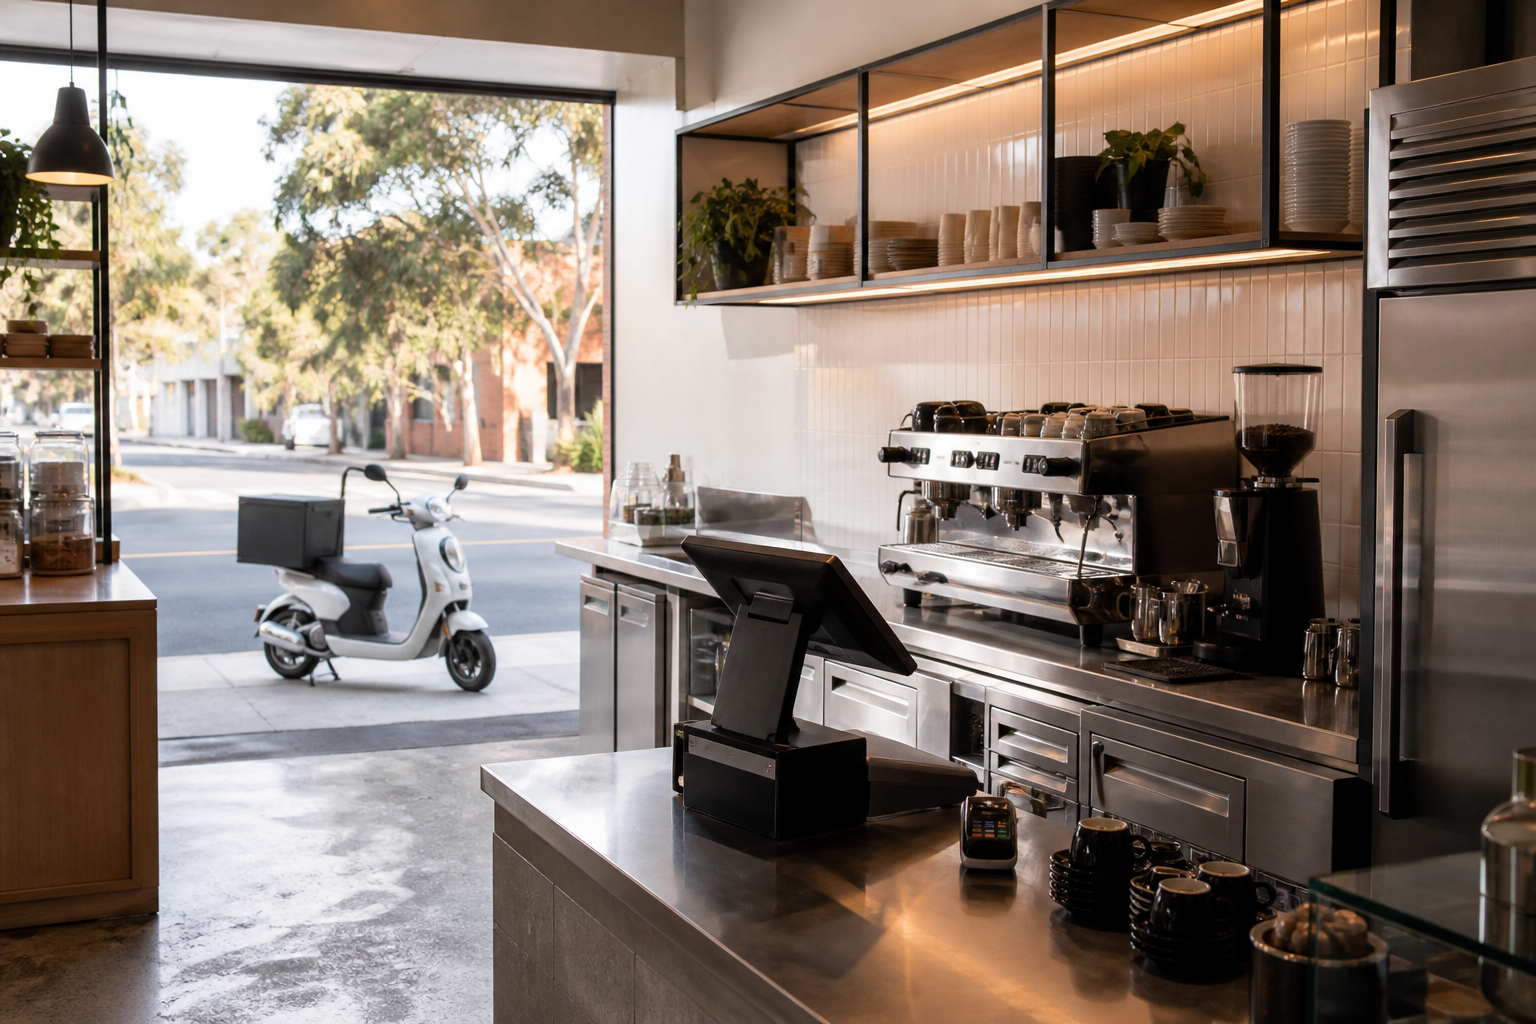
This topic is covered in full on Local Knowledge Finance
A practical guide to financing kitchen equipment, point‑of‑sale systems and delivery vehicles for Australian cafés, restaurants and food operators, without strangling cashflow.
Read the full guide on ding.financialHospitality businesses can finance kitchen equipment, POS systems and delivery vehicles using stand‑alone equipment loans, leases and structured fit‑out funding, rather than loading everything onto a home loan. The safest approach is to keep total repayments within about 15–25% of realistic revenue, match each loan term to the gear’s working life, and avoid paying interest on obsolete tech.
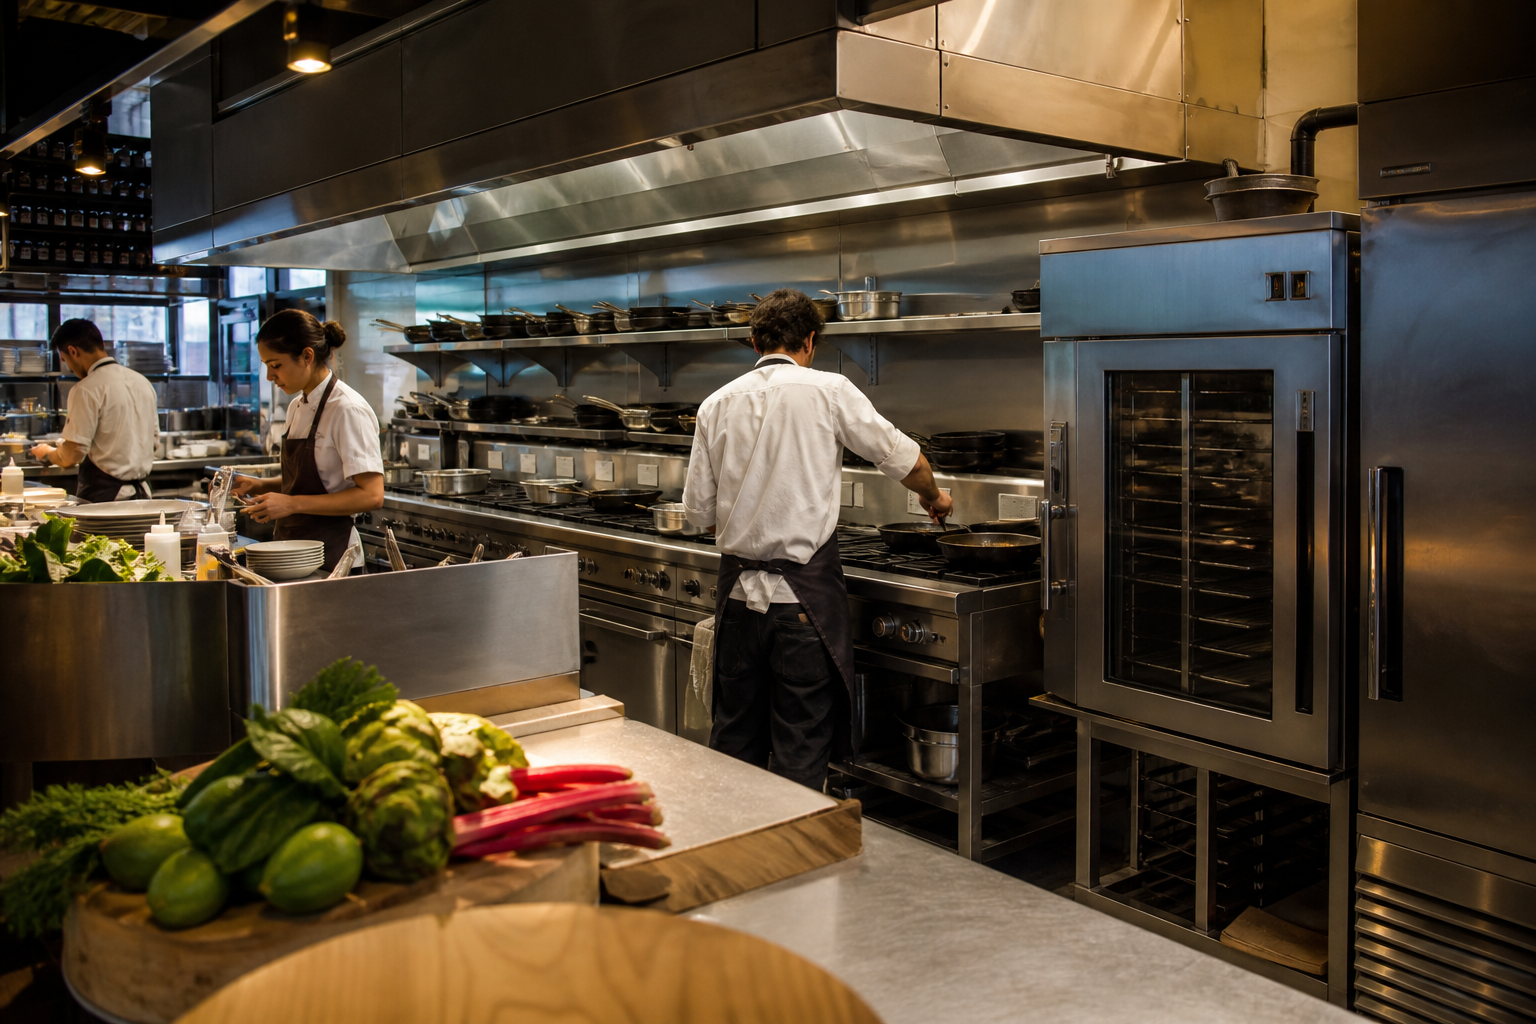
1. What you can actually finance in hospitality
1.1 Typical kitchen equipment
Lenders are generally comfortable funding standard, resaleable kitchen assets, for example:
- Commercial ovens, ranges and grills
- Refrigeration and freezers
- Dishwashers and glasswashers
- Coffee machines and grinders
- Stainless benches, exhausts and smallwares packages
New gear is usually easier to fund than used. As a guide, many lenders will finance 80–100% of the cash price for new equipment and a lower percentage for older or very specialised items (see also /insights/how-much-can-i-borrow-for-business-equipment-lvrs-terms-security).
1.2 Point‑of‑sale (POS) and tech
Most POS funding covers:
- Touchscreen terminals and tablets
- Receipt printers and cash drawers
- Kitchen display screens
- Software licences and subscriptions (sometimes bundled)
Tech has a shorter life. Lenders often want POS terms at 3–5 years, with a maximum asset age of 5–7 years by the end of the loan (consistent with broader tech rules from /insights/new-vs-used-equipment-what-lenders-will-and-wont-finance).
1.3 Delivery vehicles and scooters
For delivery‑focused venues and dark kitchens, finance can cover:
- Cars and small vans
- Refrigerated utes
- Scooters and motorbikes
Here, lenders usually cap total asset age at 10–15 years at the end of the term, so a 5‑year loan suits a 5–8 year old vehicle, and 5–7 years for brand‑new ones.
2. Main finance options: side‑by‑side
There’s no single “best” structure. The right answer mixes different products so each asset’s loan matches its working life.
2.1 Common facilities for hospitality equipment
| Asset type | Typical product | Indicative term | Security | When it fits best |
|---|---|---|---|---|
| Heavy kitchen gear | Chattel mortgage / lease | 4–7 years | Gear itself | Long‑life items with good resale value |
| Coffee machine only | Small ticket equipment loan | 3–5 years | Machine, personal guar. | Smaller deals, income‑critical equipment |
| POS hardware/terminals | Technology equipment loan | 3–4 years | POS equipment | Fast‑changing tech, frequent upgrades |
| Delivery vehicles | Vehicle chattel mortgage | 3–7 years | Vehicle, sometimes PG | Cars, vans, scooters linked to deliveries |
| Full fit‑out mix | Blend of above + biz loan | 3–7 years | Mix of asset & cashflow | New venues, refurbishments and multi‑asset projects |
For full fit‑outs, splitting funding into buckets is usually safer than one big blended loan. That principle is explained in detail for cafés in /insights/funding-mascot-cafe-restaurant-retail-fitout-without-killing-cashflow.
2.2 Why not just top up your home loan?
Using your home for business equipment can look cheap, but you’re often repaying a 5‑year asset over 25–30 years. Prior articles show this can nearly triple total interest versus a 5–7 year stand‑alone facility (see /insights/cross-collateralisation-property-equipment-loans-pros-cons-alternatives).
For hospitality operators, that also concentrates risk: one bad season and both the business and the family home are on the line.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.