
Article
Timing Your Purchase: Reading Local Signals in Booms and Lulls
Written and reviewed by James Chee, CPA · Last reviewed
Buying in a boom or flat market can both work if you read the local numbers properly. Here’s how a switched‑on broker should track auctions, days on market and lending conditions so you can act safely this week.
Key Takeaway
Buying in a boom vs a flat market both can work if buyers track local indicators like auction clearance rates, days on market and discounting, and align loan structure with conditions. Clearance rates above ~70% often signal a hot market, while rising days on market and larger discounts indicate more buyer power. The article explains how brokers interpret these signals alongside APRA’s 3% serviceability buffer and changing lender appetite to decide on buffers, pre-approval strength and negotiation tactics.
Watch the short answer
Home loan tips for digital creators and freelancers
While you’re weighing boom vs lull using local data, this video steps through home loan basics if you’re a digital creator or freelancer.
Read the transcript
If you earn your revenue through digital creator platforms or rolling freelance contracts, standard retail banks are programmed to treat you like a high-risk borrower. When their automated systems look for a standard corporate payslip, and find multiple payment platforms instead, they hit 'reject'. We don't use those systems. We use alternative documentation pathways specifically built for modern digital income. We utilise a 12-month smoothing model that verifies your true capacity straight from your bank deposits, entirely bypassing the outdated PAYG paperwork gatekeepers. DM me, 'CREATOR', to get your digital income assessed by a human.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Buying in a boom or flat market can both work if you read the local numbers properly. Here’s how a switched‑on broker should track auctions, days on market and lending conditions so you can act safely this week.
Read the full guide on tailoredloans.sydneyBuying in a boom can be as smart as buying in a flat market – if you read local indicators and match your finance strategy to the conditions. Your broker should be tracking suburb‑level auction results, days on market, discounting and lender appetite, then turning that into clear rules: how much to bid, how long to fix, and how much buffer you really need.
Here’s how to make a decision you can act on this week.
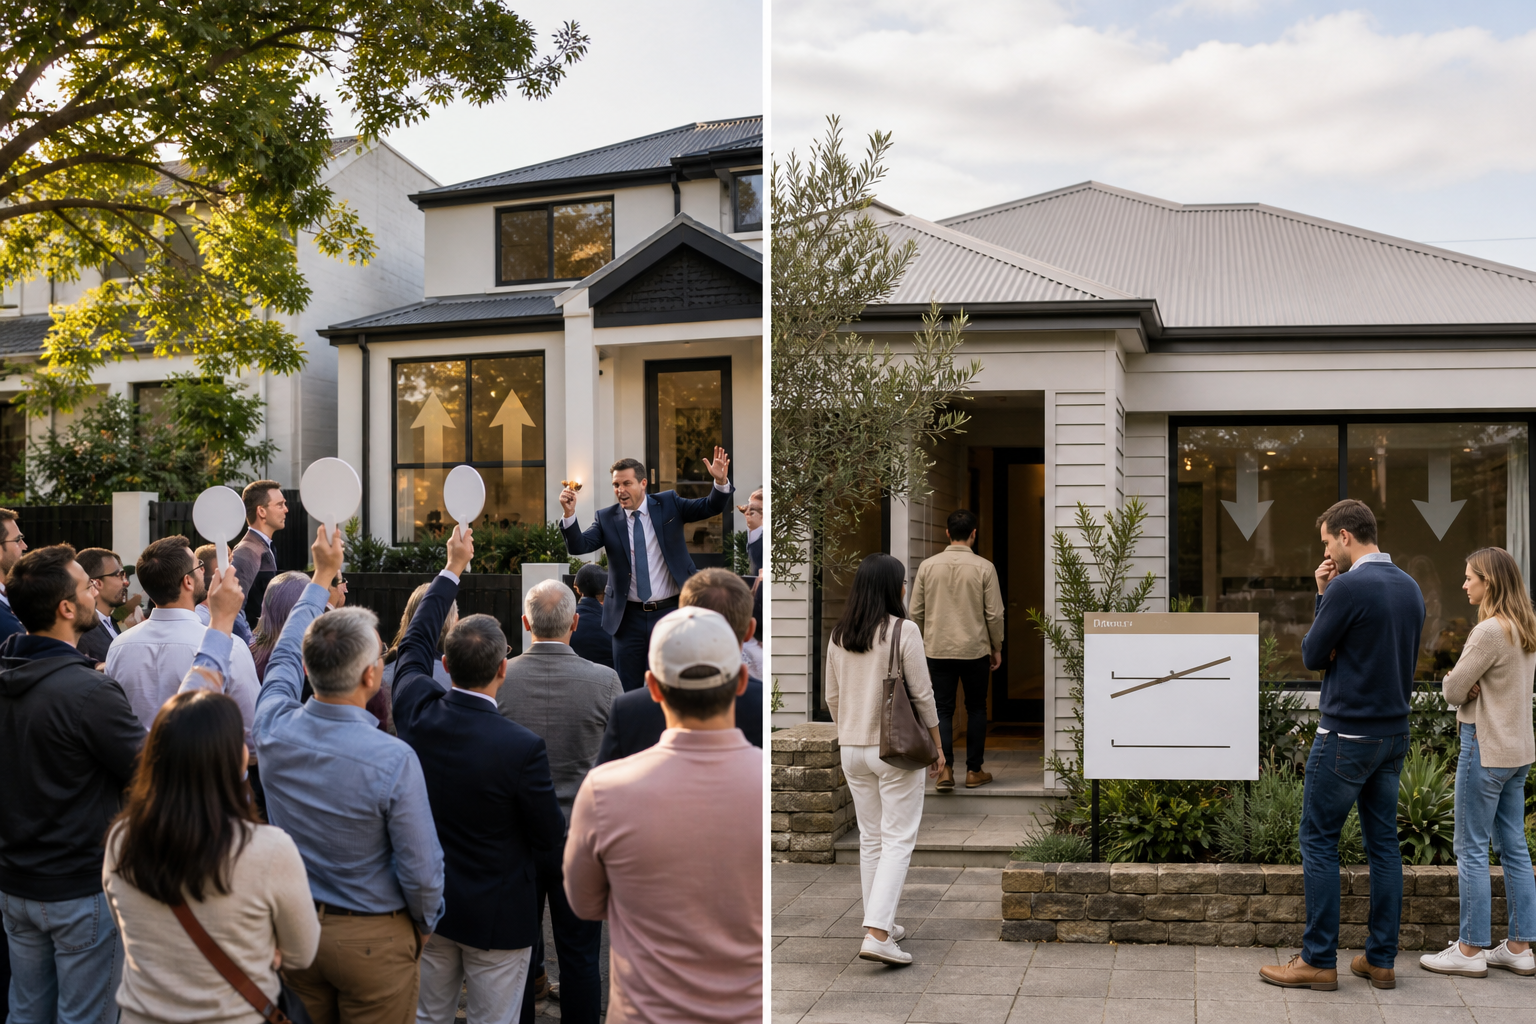
Boom vs flat: what actually changes for your finance?
In a boom, prices and sentiment are rising fast. The risks are overpaying, cashflow strain if rates rise, and valuation shortfalls.
In a flat or softer market, prices are sticky or drifting. The risks are buying a dud that keeps sliding, and over‑gearing on something with weak fundamentals.
A good broker adjusts three things to match the cycle:
- Approval quality – how strong your pre‑approval and documentation need to be.
- Structure – how you split fixed/variable, use offsets and interest‑only.
- Risk buffers – cash in offset, extra capacity above your planned repayments.
For complex scenarios or competitive suburbs, a genuinely local broker has an edge because they see how banks and valuers treat specific postcodes week to week. That’s the point of difference covered in more depth in When a Truly Local Mortgage Broker Gives You a Real Edge.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.