
Article
How Banks Really Judge Off-the-Plan Projects (And What To Avoid)
Most buyers obsess over floorplans and finishes. Banks care about very different things. This guide shows how lenders really assess off-the-plan projects so you can pick developments that are more likely to be funded all the way to settlement.
Key Takeaway
Banks judge off-the-plan projects on developer strength, location risk, project scale, buyer mix and contract terms, not just the individual borrower. Lenders typically stress-test valuations and may cap loan-to-value ratios or restrict postcodes they see as oversupplied. Choosing projects with strong developers, balanced unit mixes, realistic pricing and lender-friendly contracts materially improves the odds of finance approval at settlement. Buyers should review both their own borrowing capacity and the project’s risk profile before signing a contract.
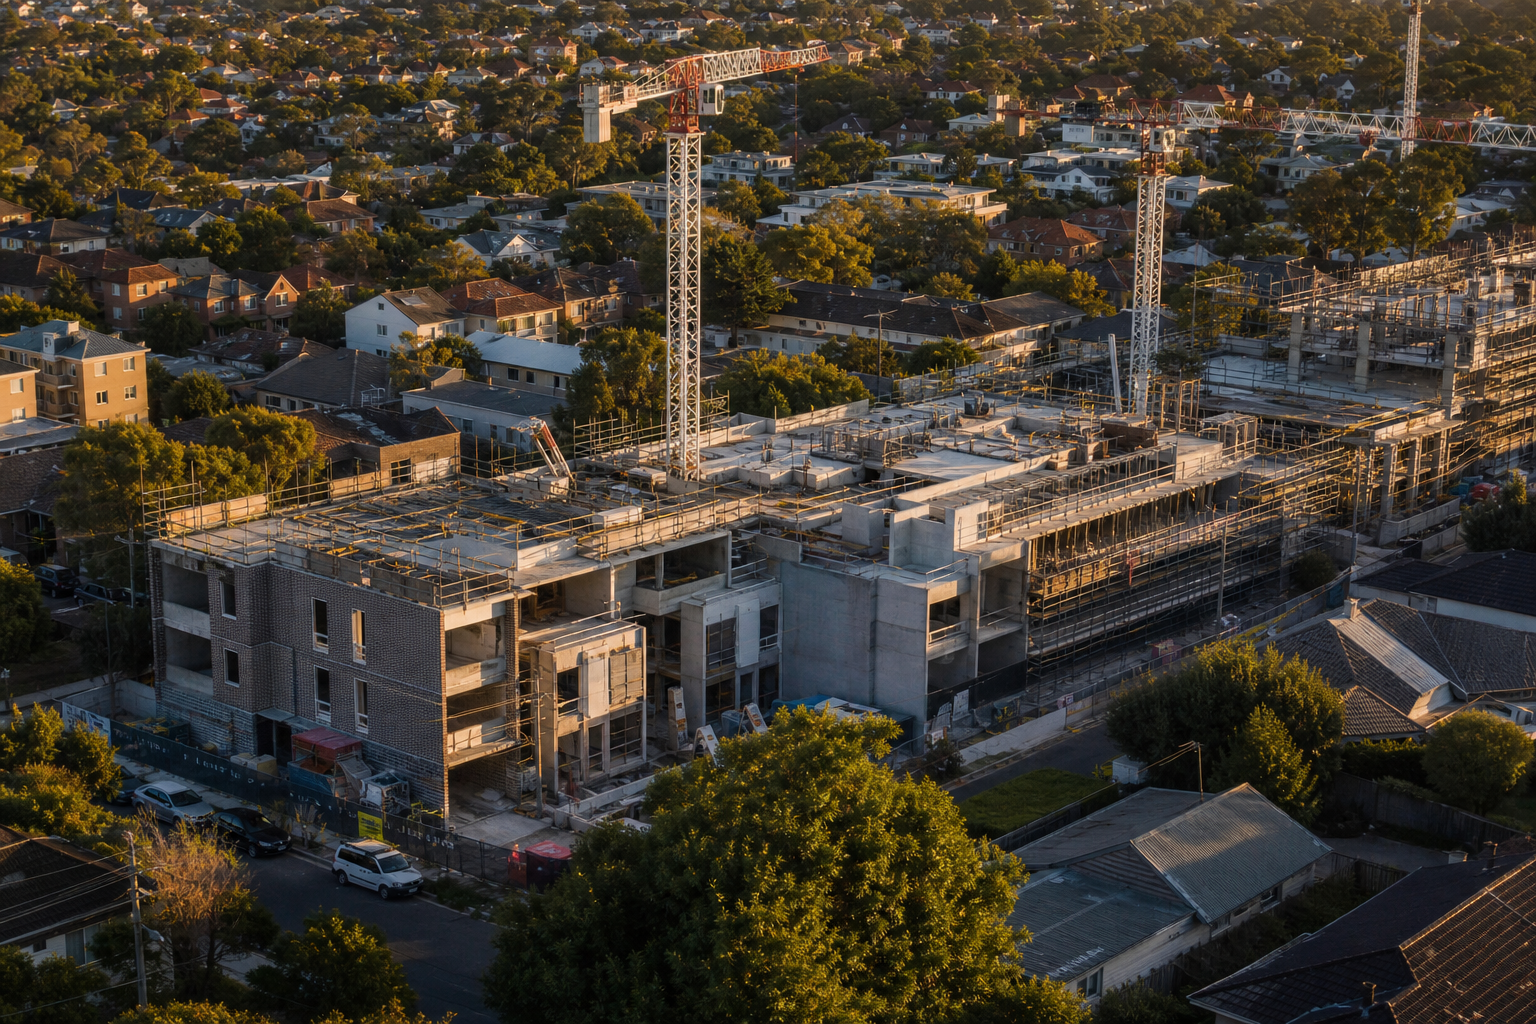
This topic is covered in full on Tailored Loans Sydney
Most buyers obsess over floorplans and finishes. Banks care about very different things. This guide shows how lenders really assess off-the-plan projects so you can pick developments that are more likely to be funded all the way to settlement.
Read the full guide on tailoredloans.sydneyMost off-the-plan horror stories I see don’t start with a bad borrower – they start with a project the banks never really liked.
In lender language, choosing the right off-the-plan project means picking a development that is likely to value up, settle smoothly, and stay within the bank’s risk appetite all the way through construction. If you choose a project the banks see as risky, your loan can fall over at valuation or settlement – even if your personal finances are spotless.
What I tell my clients is simple: before you fall in love with the brochure, check whether the project itself looks lendable.
The lender’s rulebook: how banks really view off-the-plan
When a bank assesses an off-the-plan purchase, they effectively run two separate credit decisions:
- Do we like you? Income, expenses (including HEM), credit history, existing debts.
- Do we like this project? Developer, location, design, contract terms, valuation risk.
You can control the first. This article is about the second.
For a project to be lender-friendly, banks usually want:
- a proven developer and builder with a clean track record
- sensible scale for the suburb (not the 600th unit in a small town)
- a mix of apartments that owner-occupiers would actually live in
- contracts that don’t give the developer unlimited power to change fundamentals
- pricing that stacks up against recent, settled sales.
If those aren’t there, the bank’s appetite shrinks: they might reduce maximum LVRs, cap exposure in that building, or quietly blacklist the project altogether.
Developer and builder: the first filter most buyers skip
The mistake I see most is buyers spending weeks analysing floorplans and zero minutes checking who is actually building the thing.
What banks look for in a developer
Lenders generally favour projects where the developer:
- has a track record of delivering similar projects on time and on budget
- has not featured in recent defects scandals, major lawsuits or insolvencies
- is willing to provide full project information to banks.
If a developer drags their feet or refuses to provide core documents, that’s a strong warning sign. I’ve written separately about the specific paperwork lenders want in /insights/developer-information-bank-approval-off-the-plan – it’s worth reading that alongside this guide.
Why the builder matters as much as the brand on the brochure
Many big-name developers outsource construction. Banks (and valuers) will look hard at:
- the builder’s licensing, insurance and defect history
- whether they are already stretched across multiple large sites
- how they handled previous downturns.
In the post-2020 construction environment – with multiple builder collapses – I treat builder risk as a first-order issue. A glossy marketing suite won’t fix a half-built shell if the builder fails and funding is pulled.
Action this week: Ask the agent, in writing, to confirm who the builder is and whether that builder has delivered similar projects in the last five years. If they dodge the question, find another project.
Scale, location and saturation: why some postcodes are quietly capped
Banks don’t lend into maps – they lend into micro-markets.
Project scale vs local demand
Big is not automatically bad, but lenders get nervous when:
- the number of new units is large relative to the existing stock in the suburb
- there are multiple similar towers completing around the same time
- local incomes and population growth don’t justify the extra supply.
In those cases, banks worry that:
- valuations will come in low when everyone tries to settle at once; and
- some buyers will walk, leaving unsold stock and price discounting.
Postcode policy and internal caps
Most lenders maintain internal risk settings such as:
- “Soft caps” on exposure to particular postcodes or buildings
- tighter maximum LVRs (e.g. 80% instead of 90–95%) in high-density zones
- extra scrutiny for studios and small one-bedders.
This is why two buyers with identical incomes can get very different answers depending on where they buy.
Action this week: Ask your broker to run a quick postcode policy check for the building you’re considering. If several mainstream lenders impose lower maximum LVRs or avoid that postcode, treat it as a yellow flag.
For some buyers, this is where rentvesting or delaying the move becomes a smarter play than forcing a marginal project.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.