
Article
Buying Near The Bronte Cliffs: How Banks See Coastal Risk
Written and reviewed by James Chee, CPA · Last reviewed
Thinking of buying or refinancing near the Bronte coastline? Here’s how banks assess erosion, cliff and storm risk, how it affects your borrowing and valuation, and what to check this week before you bid or apply.
Key Takeaway
Banks will lend on coastal and cliffside property in Bronte, but they closely assess erosion, storm, access and insurability risk before approving a mortgage. Lenders may reduce maximum LVRs from 90–95% down to 70–80% for exposed sites, and valuation comments can override even strong incomes. Borrowers should review Waverley Council hazard maps, obtain indicative insurance quotes, and build 6–12 months of cash buffers to improve approval odds and avoid overpaying for high‑risk locations.
Watch the short answer
Home loans when you earn foreign income or live overseas
Working out coastal risk near Bronte? This video steps through how banks look at loans when your income or address is overseas.
Read the transcript
Earning foreign income or living overseas? Australian banks make it incredibly painful to buy local property. Foreign income shading, complex exchange rate calculations, and strict residency matrices mean most expats give up on Australian property investment. You need a broker who navigates the non-resident and expat lending policies daily. We cut through the red tape, maximising your foreign currency income to secure premium Australian real estate. Expand your portfolio back home. DM me the word 'EXPAT' to learn how.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Thinking of buying or refinancing near the Bronte coastline? Here’s how banks assess erosion, cliff and storm risk, how it affects your borrowing and valuation, and what to check this week before you bid or apply.
Read the full guide on tailoredloans.sydneyBanks will lend against many Bronte coastal and cliffside properties, but they look hard at erosion, storm and access risk before they say yes. If valuers flag high hazard or limited resale demand, your maximum LVR can drop from 90–95% to 70–80%, or the loan can be declined even with strong income.
In practice, that means you must check the risk yourself before bidding or refinancing, not after.
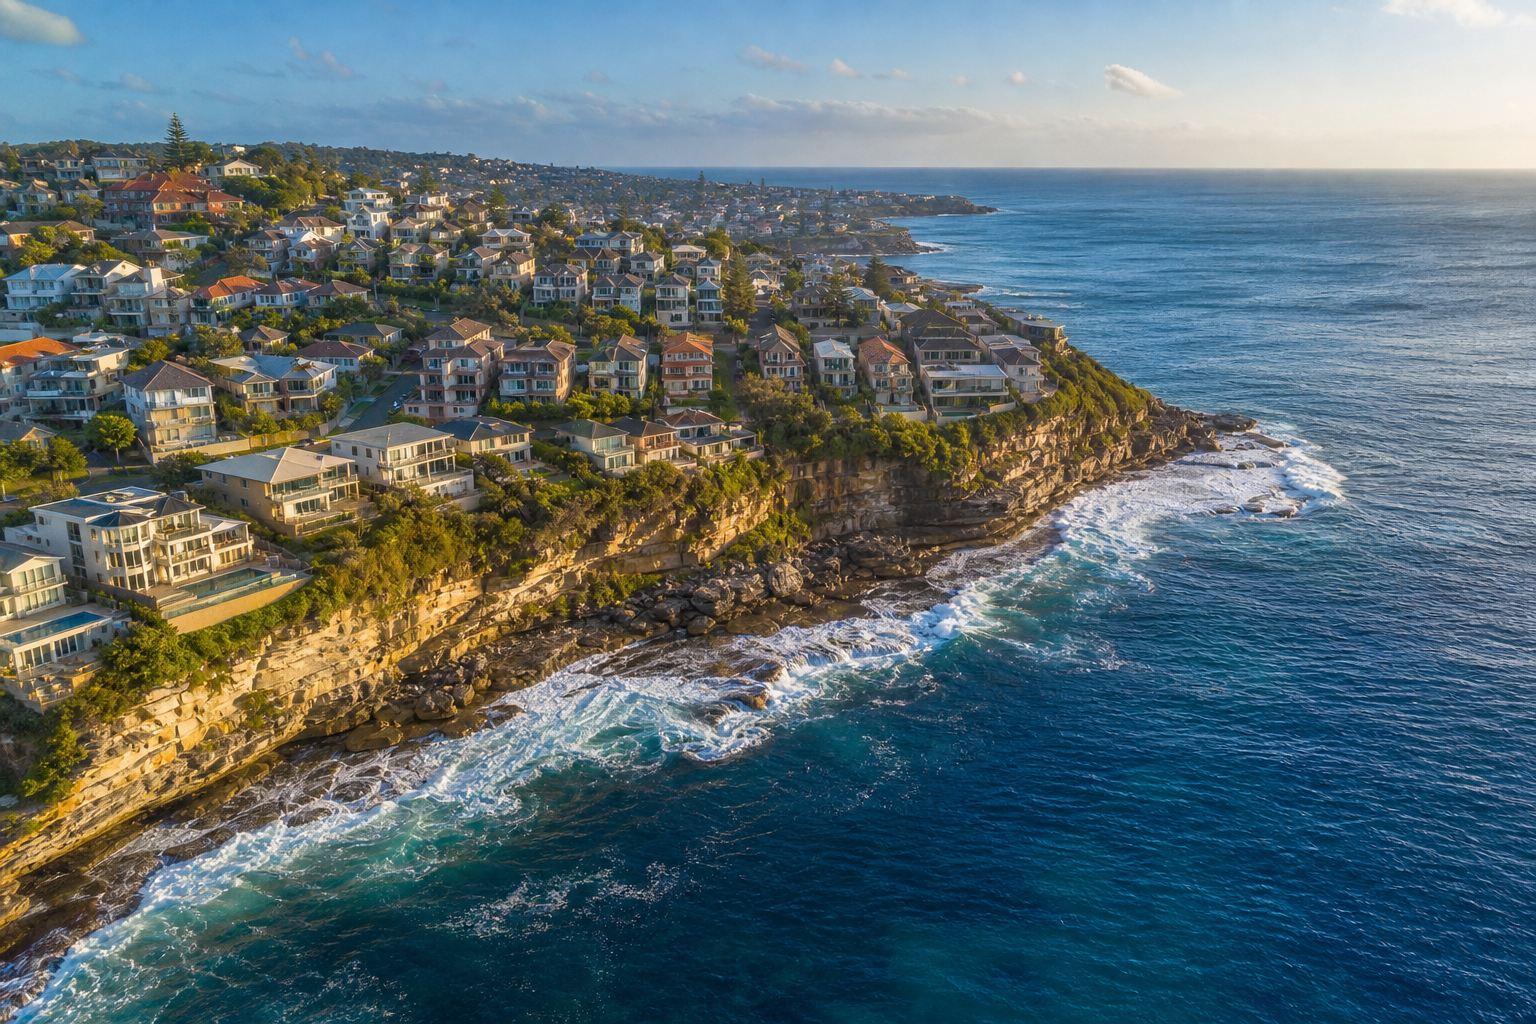
How banks think about Bronte coastal and cliff risk
From a lender’s point of view, Bronte’s cliffs and beachfront are beautiful collateral until they’re hard to insure or hard to sell. They care about three things:
- Will this property still be there and usable in 20–30 years?
- Can a typical buyer insure it at a reasonable cost?
- Is there a deep resale market if they ever have to sell it?
To answer that, credit teams lean heavily on the valuer’s comments and local planning data, not just the purchase price.
Common lender red flags:
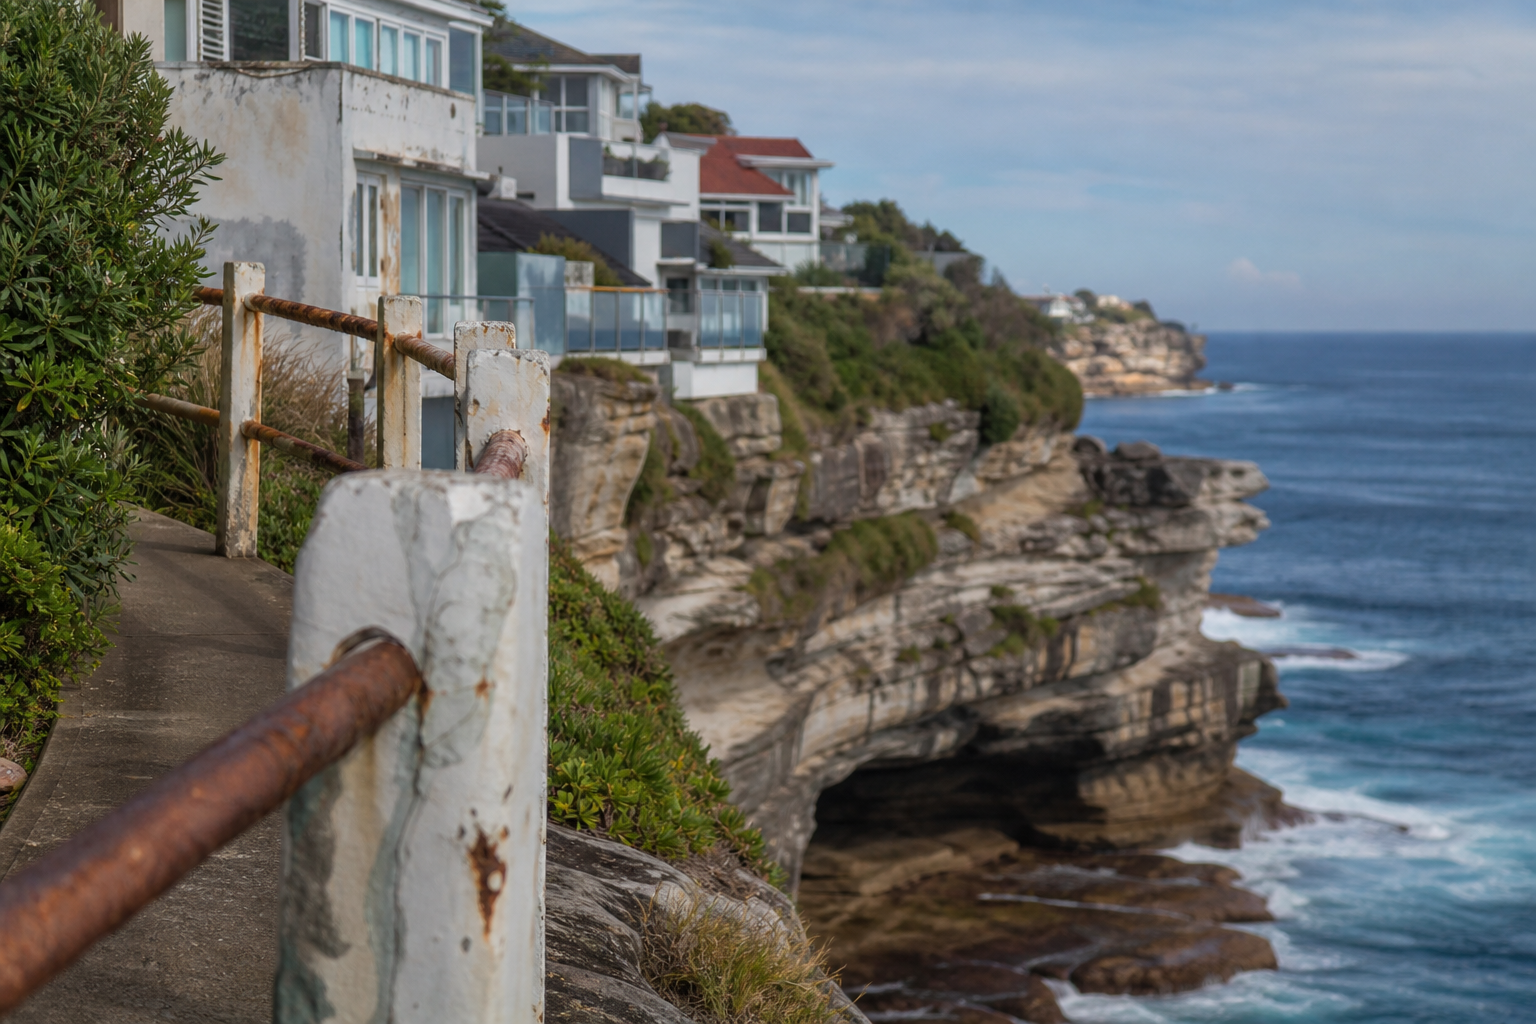
- Very close to an eroding cliff or escarpment
- In a mapped coastal hazard or landslip zone
- Limited vehicle access for emergency services
- Heavy reliance on expensive, specialist insurance
If two or more show up, expect tougher terms.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.