
Article
Decoding Company, Community and Strata Titles in Alexandria
Plain‑English guide to how company title, community and strata schemes work in Alexandria, and what each means for your deposit, borrowing power and finance risk this week.
Key Takeaway
This guide explains how company title, community title and strata schemes in Alexandria affect borrowing power, deposit size and bank approval. Lenders typically treat company title as higher risk, with lower maximum LVRs and tighter scrutiny of by‑laws and shareholder rules, while mainstream strata can support up to 80–90% LVR if the building is strong. Buyers should confirm title structure early, match it to lender appetite, and stress-test repayments at rates 3% higher before signing contracts.
This topic is covered in full on Tailored Loans Sydney
Plain‑English guide to how company title, community and strata schemes work in Alexandria, and what each means for your deposit, borrowing power and finance risk this week.
Read the full guide on tailoredloans.sydneyBuying in Alexandria or Green Square, the title on the contract – company, community or strata – can quietly decide how much you can borrow, what deposit you need and how hard the bank will look at your building.
Within the first week of taking a property seriously, you want to know exactly which title you’re dealing with and what that means for your finance. In Alexandria:
- Strata is usually the easiest to finance.
- Community can be fine but behaves more like a mini‑estate with shared facilities and extra levies.
- Company title is the most complex and often needs a bigger deposit and a more specialist lender.
This guide unpacks those differences in plain English, so you can make a decision‑grade call on your next Alexandria purchase or refinance this week.
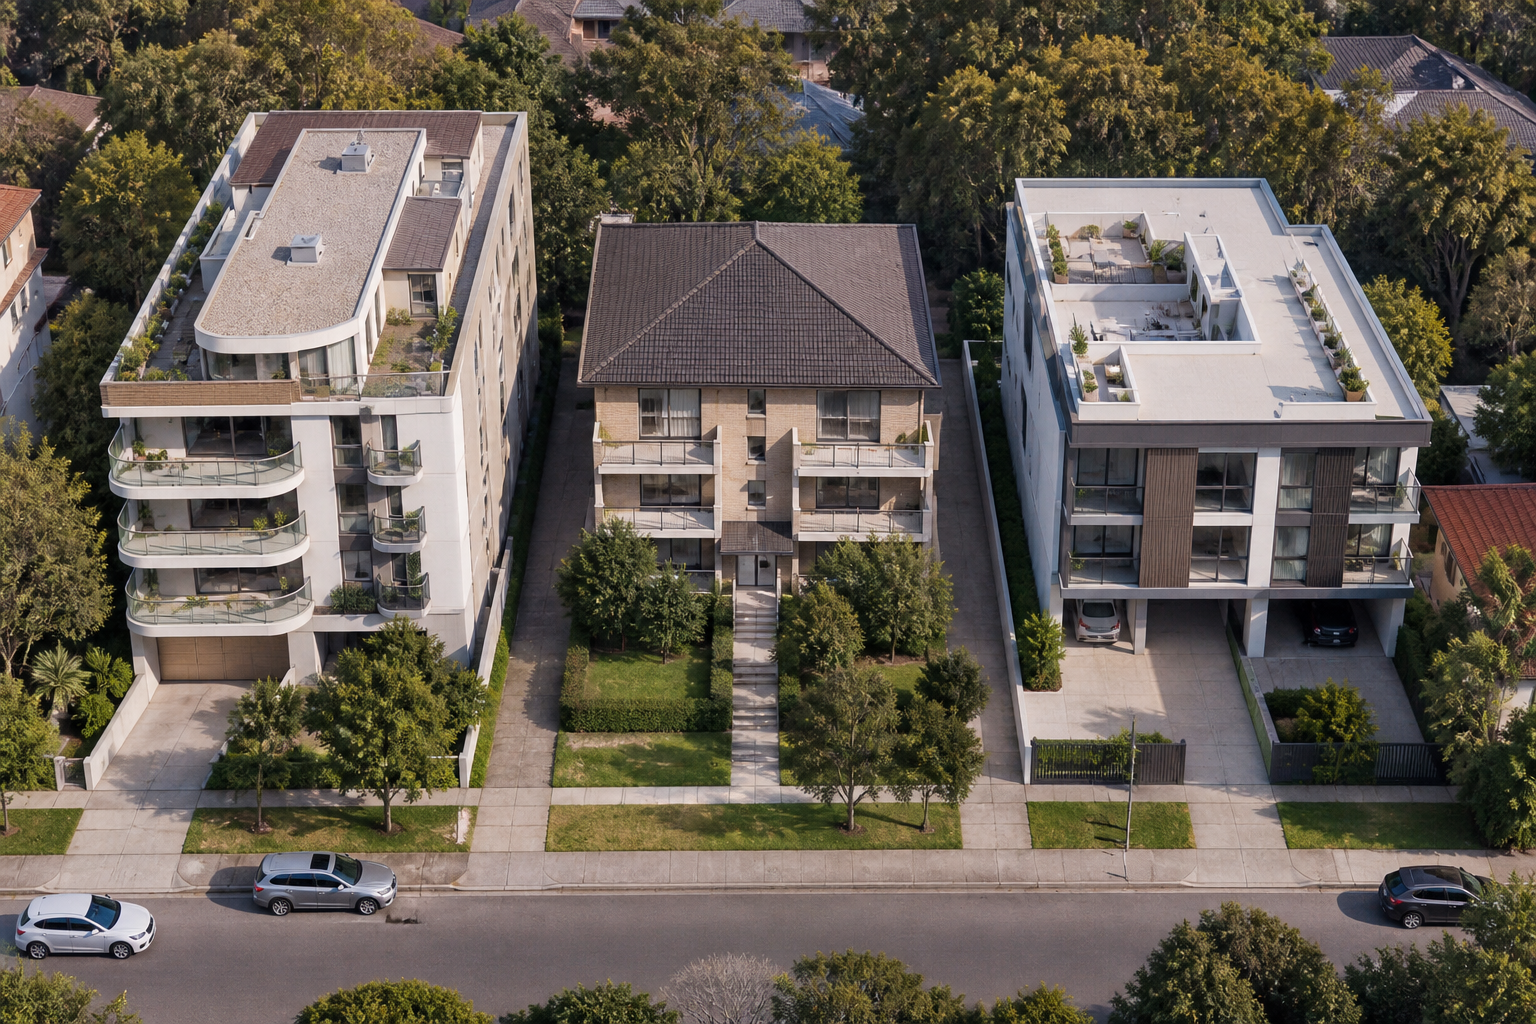
1. The three main title types you’ll see in Alexandria
1.1 Quick definitions in local language
Strata title
You own your unit plus a share of the common property via the owners corporation. Very common in Alexandria apartments, from older walk‑ups to big new complexes around Green Square.
Community title
You own your lot (often a townhouse or terrace) and share facilities such as gardens, driveways or recreation areas via a community association. More common in townhouse complexes or mixed townhouse/apartment estates.
Company title
You buy shares in a company that owns the building, and those shares give you the right to live in a specific unit. Common in older Sydney blocks; a handful pop up in inner‑south areas as you move away from pure new strata stock.
From a lifestyle point of view, all three can feel similar: you have neighbours, shared spaces and levies. From a finance point of view, they are very different.
2. Why lenders care about title type in Alexandria
Banks and non‑banks look at Alexandria through a risk lens:
- High‑density development, some mixed‑use buildings and a mix of older and brand‑new stock.
- A history of building defects, waterproofing and cladding issues in pockets of the area.
- A lot of investors and first‑home buyers using high leverage.
Title type sits on top of that. It affects three things:
- How easy it is to sell if the bank ever needs to recover its money.
- How transparent the rules and finances are (by‑laws, levies, sinking funds, company constitution).
- How much control other owners or directors have over who can buy, occupy or rent.
The more uncertainty there is on those points, the more conservative the lender tends to be.
If you’re looking at anything outside plain‑vanilla strata, it’s worth reading our broader inner‑south guide on quirks: Financing Company Title and Strata Quirks Around Green Square.
3. How strata, community and company title differ for finance
3.1 Headline lending differences
Below is a realistic, illustrative comparison. Actual policies vary by lender and change over time.
| Feature / Risk Area | Mainstream Strata (Alexandria) | Community Title (Townhouses/Estates) | Company Title (Older Blocks) |
|---|---|---|---|
| Typical max LVR (owner‑occupier)* | Up to ~90–95% with LMI, ~80% without | Often up to ~90% with LMI, some lenders cap lower | Commonly 60–80%; many lenders decline or treat case‑by‑case |
| Typical max LVR (investor)* | Often capped ~80–90% | Often similar to strata but more lender variation | Often max ~60–70%; some lenders won’t fund investors |
| Valuation approach | Standard, but more scrutiny for small/mixed‑use | Standard plus check of estate facilities and levies | Extra conservative; valuers look hard at demand and resale |
| Legal complexity | Low – standard legislation and by‑laws | Moderate – layered schemes, extra rules possible | High – company constitution, share rules, director approval |
| Tenant/occupier restrictions | By‑laws only (usually manageable) | Community rules plus strata by‑laws | Often significant restrictions on leasing or short‑stay |
| Common red flags | Cladding, defects, weak strata | Under‑funded estate facilities, restrictive rules | No lending history, right of veto on buyers, big levies |
*Indicative only – not a quote or promise. Always check specific lender policy.
3.2 What this means in practice
In Alexandria terms:
- A standard 2‑bed strata unit in a solid building might support up to 90–95% LVR with LMI for an owner‑occupier, assuming income and credit stack up.
- A townhouse in a community scheme might be similar but with more questions about levies, facilities and the health of the community association.
- A company title unit may need a 20–40% deposit and a lender that specifically accepts company title – especially if you’re an investor.
We dig into each type below.
4. Strata title in Alexandria: usually the easiest, not always simple
4.1 Why banks like mainstream strata
Strata in NSW is a known quantity. There’s modern legislation, standard documents and a deep resale market in Alexandria, Zetland and Green Square.
Lenders like that:
- It’s easy to value: plenty of comparable sales.
- Rules are clear: by‑laws, minutes, insurance, levies.
- If they ever need to sell, the buyer pool is broad.
This is why strata is the benchmark most policies are written around.
4.2 The local twists: size, density and mixed‑use
In Alexandria/Green Square, the strata label can still hide quirks:
- Small or studio apartments – some lenders have minimum internal sizes (often 40–50 m² excluding balcony).
- High‑density complexes – entire blocks full of investors can attract lower LVR caps.
- Mixed‑use buildings – retail, restaurants or short‑stay accommodation underneath can spook some lenders.
We unpack those in more detail in the related pieces on small units and high‑density buildings:
- Small Studio and One‑Bed Apartments in Alexandria: Minimum Size, LVR and Valuation Basics
- High‑Density and Mixed‑Use Buildings Around Green Square and Alexandria: Extra Lending Rules to Know
4.3 Worked example – mainstream strata unit
You’re buying a $900,000, 2‑bed strata unit in a solid Alexandria block.
- You want to borrow at 90% LVR = $810,000.
- You’ll need at least $90,000 deposit plus costs (stamp duty, legals, inspections) – say another ~$40,000–$45,000.
- On a 30‑year P&I loan at an indicative 6% p.a., repayments are about $4,850/month.
Using our stressed‑cost rule of thumb (buffering rates by +3% [src: inner‑south cash‑buffer guides]), you should also check:
- Repayments at 9% ≈ $6,500/month.
- Can your after‑tax income and cash buffer sustain that level, especially in a suburb known for auction pressure and short settlements? See Winning Short Settlements and 66Ws in Alexandria Without Blowing Up.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.