
Article
How I Coordinate Personal, Business And SMSF Loans For A Rose Bay Home
Buying a high‑end Rose Bay home with personal, business and SMSF loans is less about rates and more about orchestration. Here’s how I structure it so your family home, business and super all pull in the same direction without over‑exposing you.
Key Takeaway
Coordinating personal, business and SMSF loans for a high-end Rose Bay home means treating all debts and guarantees as one ecosystem, because banks usually do. A $5m purchase with 70% LVR can easily involve $3.5m in borrowing across entities, so sequencing and security choices materially affect capacity and risk. The key is to model combined cashflows, avoid cross-collateralising home and business assets, and lock in clean, purpose-specific splits before signing a contract.
Most Rose Bay buyers think in terms of “my home loan” and “my business loans”. Lenders don’t. Once your SMSF, companies and trusts are in the mix, banks usually treat every debt and guarantee as one ecosystem. For a $5–8 million Rose Bay purchase, that ecosystem can make or break both the deal and your retirement.
The core job is to coordinate personal, business and SMSF lending so three things are true at once: (1) you can settle the home, (2) your business still works on Monday, and (3) your super stays on track. That’s structure, not just rate.
A real Rose Bay scenario: three balance sheets, one decision
A recent (anonymised) client: late‑40s Rose Bay couple, she’s a specialist doctor, he runs a marketing agency. They wanted a $7.5m home with harbour glimpses.
- Personal: existing $1.3m home loan, strong equity, lumpy income.
- Business: $800k in equipment and working‑capital facilities, all personally guaranteed.
- SMSF: $1.4m balance, already holding a geared commercial property via LRBA.
Their first bank said: “We can probably stretch to $4.5m home loan if you close some business facilities and don’t touch the SMSF.” That looked like a funding gap.
What I told them: “The problem isn’t your income or assets. It’s that everything is wired together in the wrong order.”
We:
- Re-sequenced the move (refinance + restructure before new contract).
- Unwound cross‑collateralisation between the business and current home.
- Ring‑fenced the SMSF so its LRBA didn’t strangle personal borrowing capacity.
The result: clean approval for a $5m owner‑occupied facility plus a separate investment split for future plans, without raiding business working capital.
That’s the difference between “a home loan” and orchestration.
If your world sounds even half like this and you’re still dealing with siloed advice, you’ve probably outgrown a generalist. I expand on that in Deciding Between a Specialist or Generalist Mortgage Broker in Rose Bay.
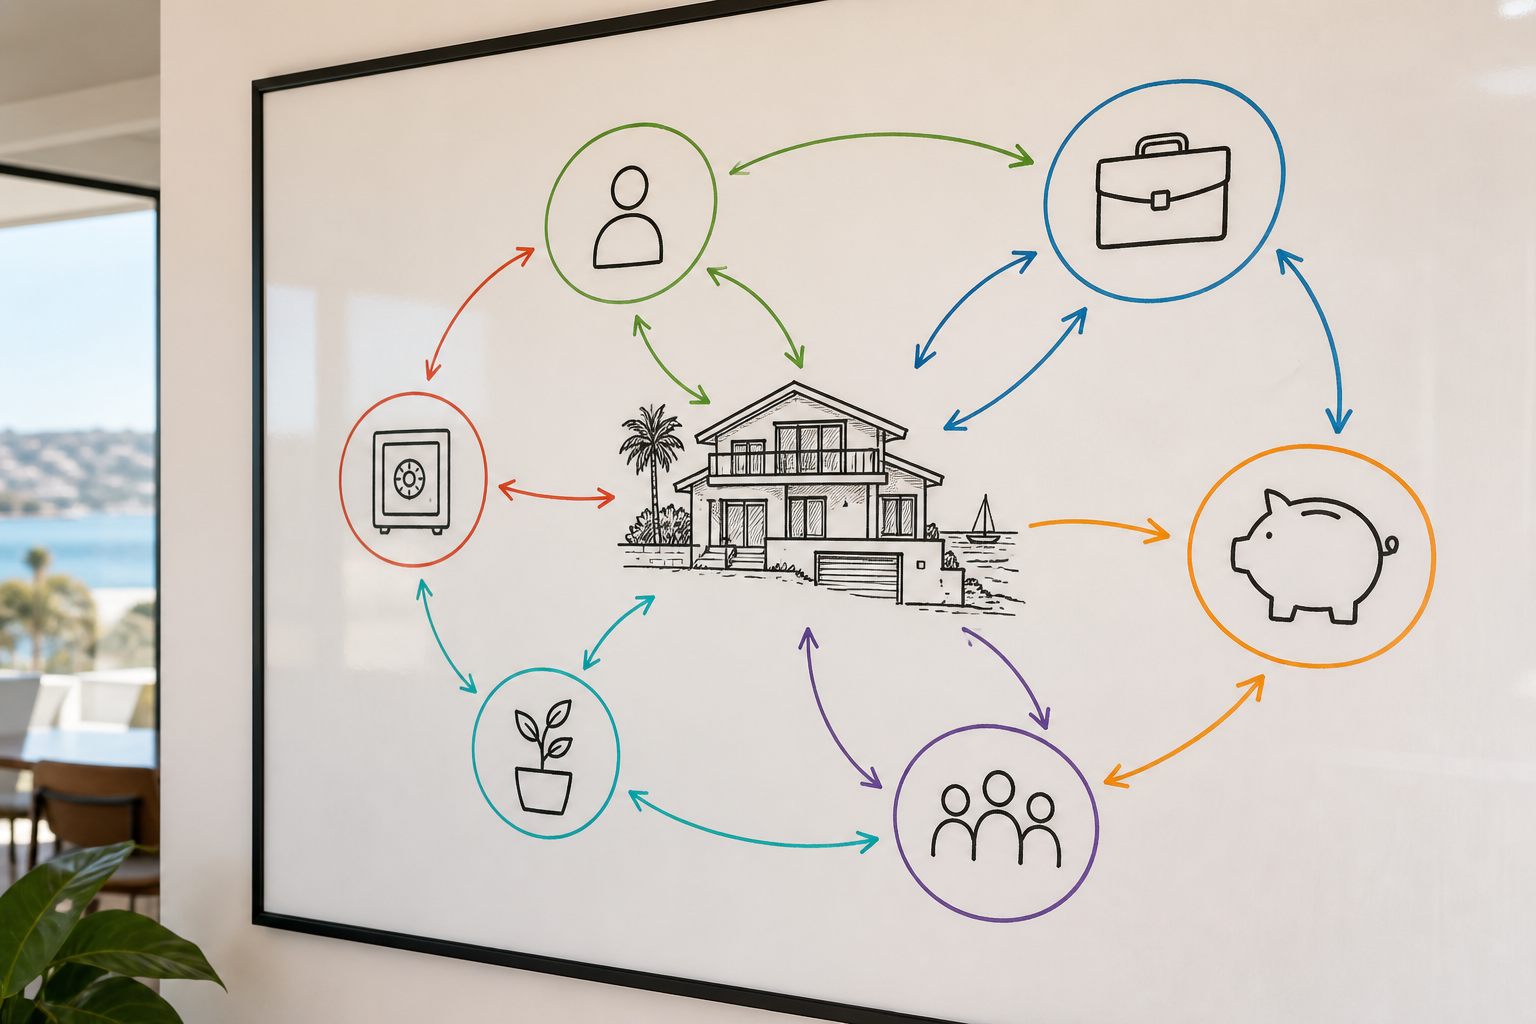
Step 1: Map your ecosystem before you touch a contract
What I tell my clients
Before we talk about what you can borrow, we map what you must protect: your family home, your business continuity, and your super.
That means building one integrated model across:
- Personal – home loans, investment loans, credit cards, HECS, living costs (APRA’s HEM benchmarks plus your real spend).
- Business – term loans, overdrafts, lease and equipment finance, any ATO payment plans, and every personal guarantee.
- SMSF – LRBAs, contributions, pensions, and the fund’s cash buffer.
Lenders are increasingly doing this consolidated assessment themselves, particularly once SMSF, company or trust borrowing is involved. If you don’t do it first, you’re letting them design your structure by default.
Why the order of moves matters
In Rose Bay, a “standard” high‑end purchase might look like:
- Price: $6.5m
- Target LVR: 70% (to avoid punitive LMI tiers)
- Borrowing need: $4.55m
If, in the 12 months before you buy, you:
- Add a new $1m SMSF LRBA for an off‑the‑plan unit; and
- Refinance your agency into a single, large bank facility all guaranteed off your existing home;
…then walk into a lender asking for $4.5m+ owner‑occupied debt, they will see a heavily geared, interconnected system. Your personal capacity could be cut by seven figures.
The better sequence is often:
- Model the combined picture (personal + business + SMSF cashflows).
- Restructure existing debt to de‑risk the home and simplify guarantees.
- Lock in home capacity for the Rose Bay purchase.
- Only then add or tweak SMSF and business facilities.
I go deeper on the entity side in When SMSF, Company And Trust Borrowing Demands More Than A Generalist.
Step 2: Decide what really secures your Rose Bay home
The mistake I see most: a bank quietly taking your new Rose Bay purchase as a convenient security for everything — home, business, sometimes even SMSF‑related guarantees.
Clean security vs “just give it all to the bank”
For a $6.5m purchase, a typical clean structure might be:
- Owner‑occupied facility A – $3.8m, P&I 30 years, secured only by Rose Bay home.
- Investment facility B – $750k, IO 5 years, secured by Rose Bay plus an investment property.
Compare that with a “lazy” structure I regularly unwind:
- One $4.5m mega‑facility securing: new Rose Bay home, existing investment unit, plus a business loan sub‑limit.
- Personal guarantees across all business entities.
On paper, it’s one big loan at a decent rate. In practice:
- A business wobble risks the family home.
- You can’t refinance the home separately without also moving the business.
- Every future deal (e.g. another investment, or a business acquisition) has to fit through one lender’s risk lens.
The knowledge fact we see again and again in Rose Bay and Dover Heights is that cross‑collateralising home, trust and company properties around personal guarantees significantly increases the risk that a business shock forces sale of personal assets. That’s why I usually separate home, investment and business loans into distinct facilities.
You’ll see the same theme in Keep Your Eastern Suburbs Home Safe When You Run A Business.
A worked security example
Say you own:
- Current home: $4m, loan $1.2m.
- Investment unit: $2m, loan $1m.
- Business premises (company): $3m, loan $1.5m (personally guaranteed).
You’re buying Rose Bay for $7m. The safer structure could be:
- Refinance and split current home loan:
- $900k owner‑occupied (to be cleared on sale).
- $300k business‑purpose split amortising over 5–7 years.
- Ring‑fence business premises to a business lender that doesn’t want the new home.
- New Rose Bay loan at 70% LVR ($4.9m) secured only by Rose Bay and, if needed, the investment unit — not by the business property.
Is it more work? Absolutely. But you’ve:
- Contained business risk.
- Preserved the ability to refinance the home in future.
- Kept your SMSF out of the firing line.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.