Article
Telltale Signs Your Dover Heights Debt Is Becoming Dangerous
Written and reviewed by James Chee, CPA · Last reviewed
Clear, local red flags that your Dover Heights mortgage and other debts are tipping from manageable to dangerous, plus a practical one‑week stabilisation plan.
Key Takeaway
A Dover Heights debt load is becoming unsustainable when total loan repayments, stress‑tested at 3% above current rates, exceed 35–40% of after‑tax income and cash or offset buffers fall below 3–6 months of essential costs. Roy Morgan data shows over 30% of Australian mortgagors are now ‘At Risk’ of mortgage stress, underscoring the need for early action. Households should quickly assess repayment ratios, buffers and behaviour shifts, then adjust budgets or seek professional help within a week.
Watch the short answer
Why staying loyal to your bank can cost you
If your Dover Heights debt feels like it’s slipping, this video shows how sticking with one bank can quietly make things harder.
Read the transcript
Banks don't reward loyalty, they exploit it. If you have been with the same mortgage or commercial lender for over 18 months, you are almost certainly paying a premium compared to a new customer walking in off the street. At Local Knowledge Finance, we run proactive audits to squeeze your current lender for a better rate or seamlessly transition you to a more agile pipeline. Stop donating money to bank profits. DM me 'AUDIT' right now.
General information only, not personal advice. Your situation is assessed before any recommendation.
Your Dover Heights debt is becoming unsustainable when, under a 3% interest rate stress test, total repayments chew through more than 35–40% of your after‑tax income and you have less than 3–6 months of essential costs in cash or true offset. Once you’re topping up living costs with new debt or asset sales, you’re in the danger zone, not just a rough patch.
Here’s how to check where you stand this week.
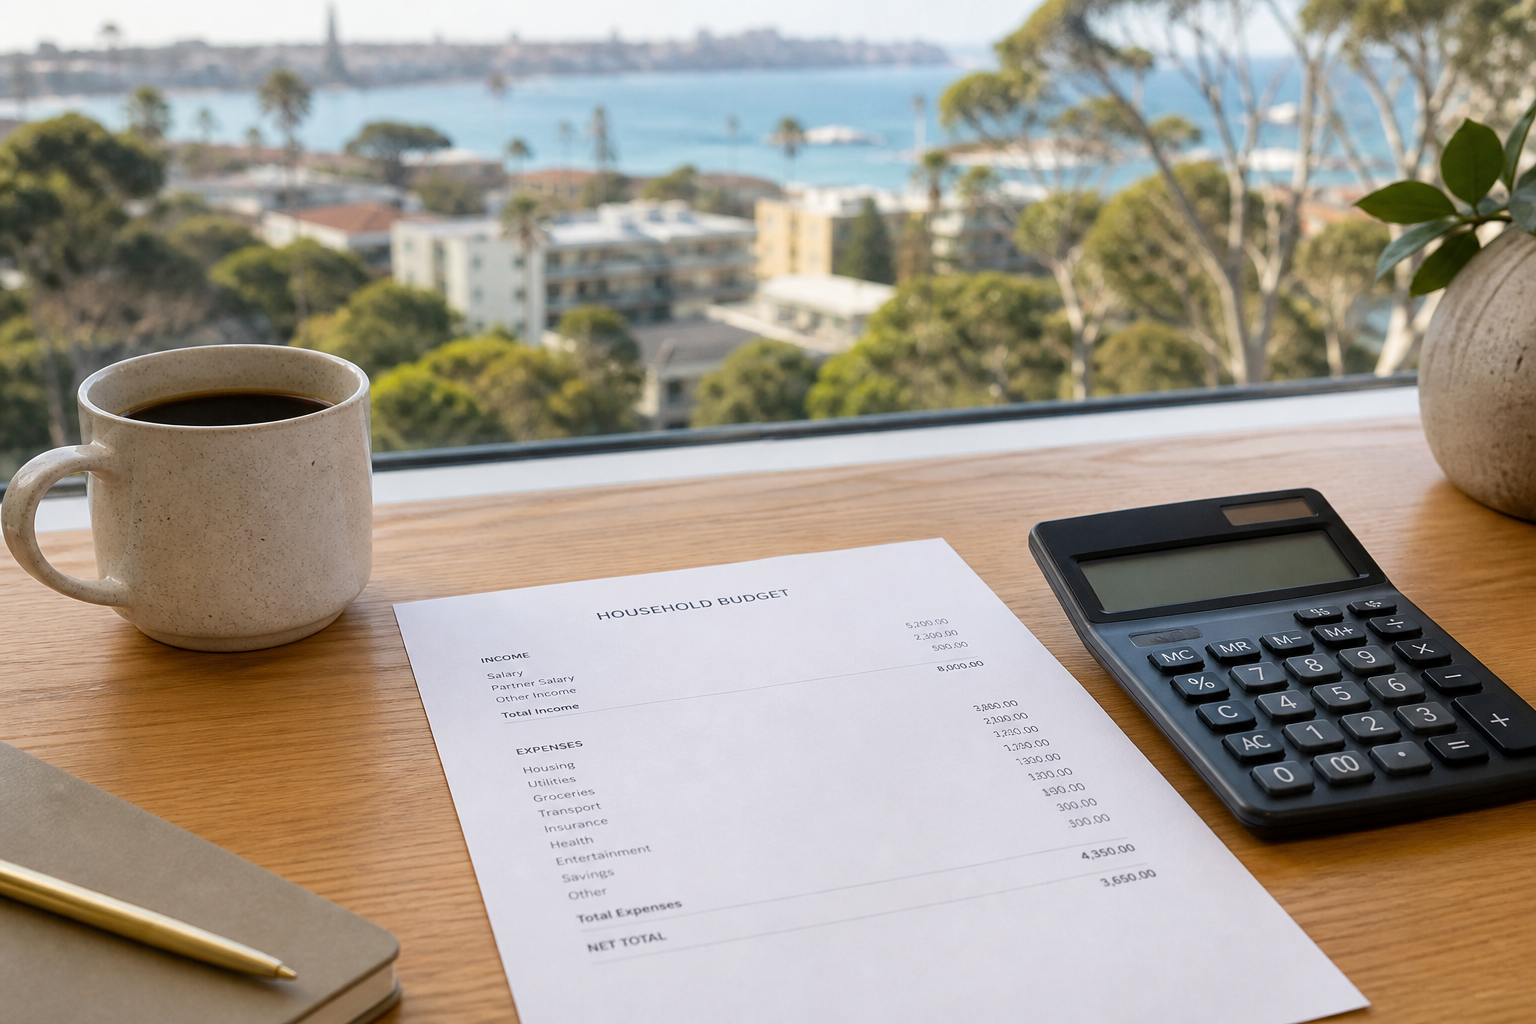
Quick stress test: are you over the line?
Run these two numbers first. If both are flashing red, treat it as urgent.
-
Stressed repayment ratio
- Add up all loan repayments: home, investment, car, personal, credit cards (assume full repayment over 3 years), business loans you support personally.
- Stress‑test at 3% above your current interest rate (APRA style). Your broker or bank can give you this figure.
- Divide that monthly total by your after‑tax household income.
If the stressed ratio is above 35–40%, research and our other guides say your debt is drifting into unsustainable territory for most households (see also /insights/inner-south-debt-load-red-flags-unsustainable and /insights/debt-red-flags-unsustainable-what-to-do-early).
-
Cash buffer check
- Add up essential monthly costs: loan repayments, food, utilities, insurance, transport, basics for kids.
- Count only cash or true offset (not redraw, shares or crypto).
- Divide buffer by essentials.
If you have less than 3–6 months, you’re running thin. For Dover Heights‑level mortgages and self‑employed borrowers, 6–12 months is the safer target.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Suburb guides
How to Build a Safe Standby Equity Facility on a Dover Heights Home
Suburb guides
Airbnb on Dover Heights Prestige Properties: How Banks Really Treat It
Suburb guides
Digital broker or Dover Heights local? How to choose this week
Suburb guides
Taming Progress Payments and Cost Overruns on a Dover Heights Coastal Reno
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.