
Article
Downsizing To Clear Debt: How To Use Sale Proceeds Smartly
Written and reviewed by James Chee, CPA · Last reviewed
Downsizing can wipe your mortgage and clean up other debts – but only if you plan how the sale proceeds, super contributions and new loan structure all work together. This quick guide shows you the key decisions to lock in before you list your home.
Key Takeaway
Downsizing and clearing debt works best when homeowners first calculate realistic after‑cost sale proceeds, then prioritise wiping non‑deductible home and consumer debt before deciding how much to contribute to super via downsizer rules and how much to allocate to the next property. In a high‑rate environment where about 28% of mortgage holders are ‘At Risk’ of stress, this approach can materially improve retirement cashflow. The key actionable step is to lock a written percentages plan for proceeds before listing the home.
Watch the short answer
Thinking about downsizing or moving house?
Learn how bridging loans can smooth the move between your current and next home.
Read the transcript
If you are looking to downsize or move houses, do not let an aggressive real estate agent bully you into selling your family home in a rush just to clear capital. Bridging finance allows you to buy your property first, secure your next chapter, and then sell your current home calmly when the market conditions favour you. Keep control of your equity. DM me 'BRIDGE' to map out the transition.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Downsizing can wipe your mortgage and clean up other debts – but only if you plan how the sale proceeds, super contributions and new loan structure all work together. This quick guide shows you the key decisions to lock in before you list your home.
Read the full guide on tailoredloans.sydneyUsing downsizing to clear debt means deliberately using your sale proceeds to wipe non‑deductible loans, reduce housing costs and rebuild buffers before you even think about lifestyle upgrades. Done well, you end up with a smaller home, lower (or no) mortgage and a cleaner balance sheet that actually works in retirement.
Step 1: Know your real sale proceeds before you dream
Before you plan contributions or a new loan, work out what you’ll actually walk away with.
Quick formula:
Sale price
− agent fees (usually ~1.5–2.5% + marketing)
− legal costs
− selling prep (styling, minor repairs)
− discharge fees and any existing loans
= net sale proceeds
Example
Sell for $1.6m, costs $60k all up, existing mortgage $600k.
$1,600,000 − $60,000 − $600,000 = $940,000 net proceeds.
This is the pot you’re actually dividing between your new home, debt clearance, super and buffers.
If you’re buying off-the-plan or timing is tricky, pair this with the sequencing ideas in /insights/downsizing-off-the-plan-apartment-finance-timing-equity-release.
Step 2: Set a simple proceeds plan (percentages, not vibes)
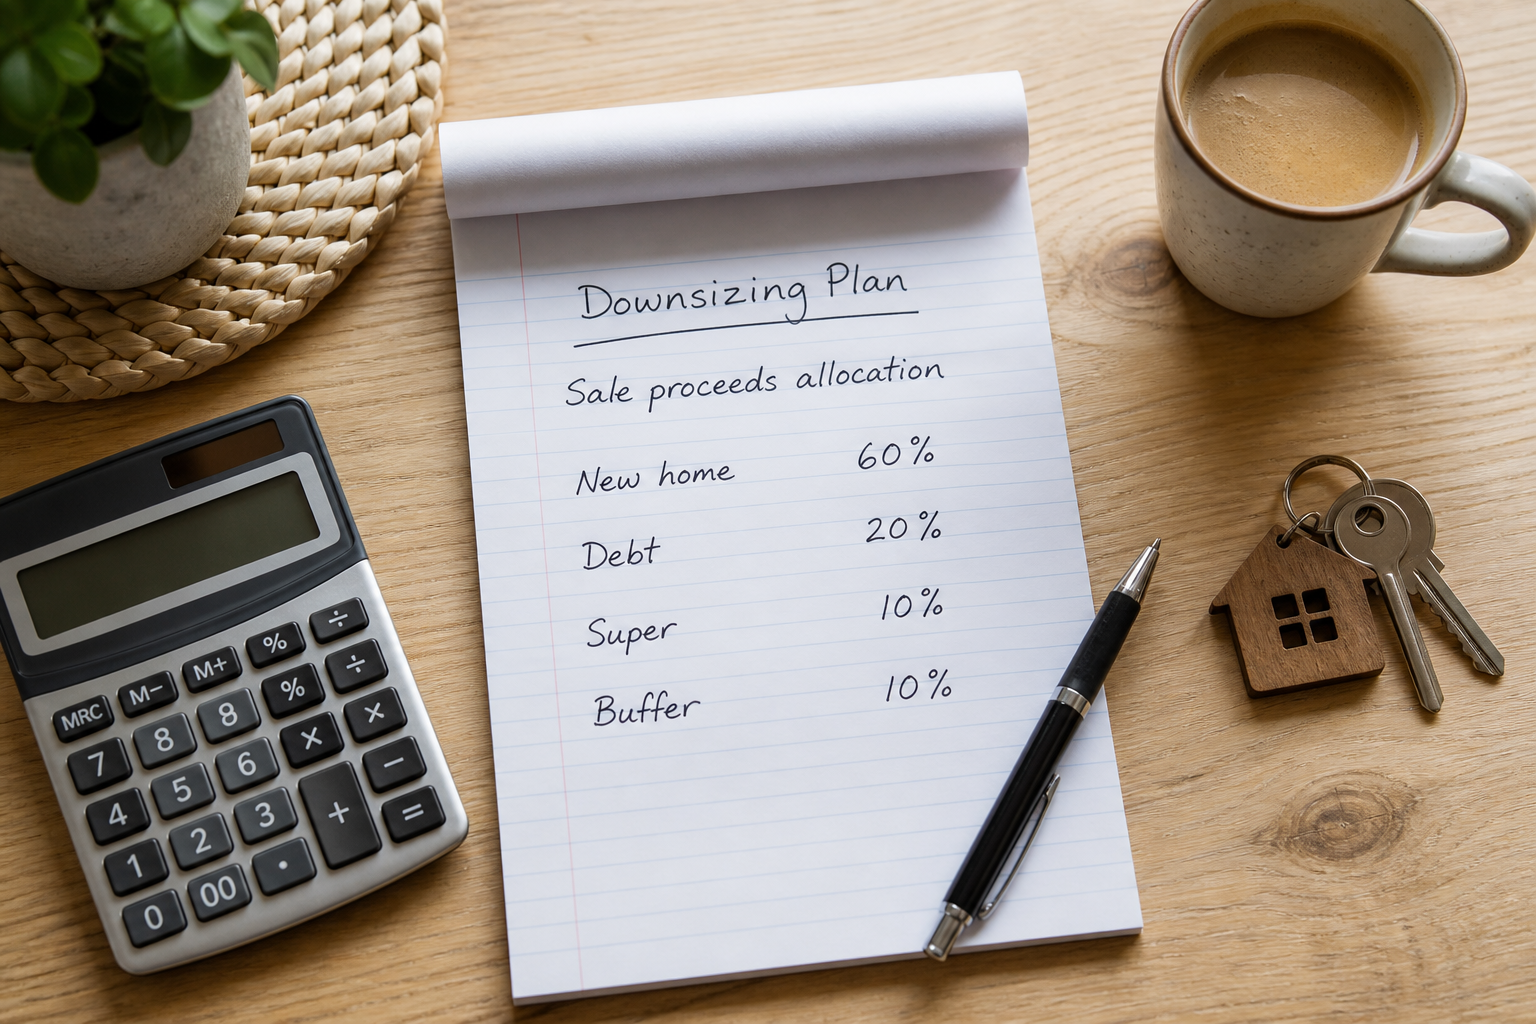
Decide, in writing, how every dollar of that pot will be used before you sign an agency agreement.
A common pre-retirement mix (not advice, just a pattern):
- 40–60%: new home purchase (deposit + costs)
- 20–40%: clear home, credit card and personal loan debt
- 10–30%: super contributions (including downsizer contributions, if eligible)
- 5–10%: cash buffer and one-off move costs
For many couples in their late 50s or 60s, a balanced goal is:
- Clear all non-deductible home and consumer debt.
- Keep only manageable investment or business debt.
- Maximise sensible super contributions, including downsizer contributions where you qualify (fact 7).
Locking this plan in early makes later decisions about refinancing, offsets and super much easier.
Step 3: Use sale proceeds to kill the right debts first
Not all debt is equal.
Priority order for most households:
- Unsecured consumer debt – credit cards, personal loans, Buy Now Pay Later. These usually have the highest rates and no tax benefit.
- Home loan on your main residence – non‑deductible, so every extra dollar you owe here costs you after-tax.
- Tax and ATO payment plans – clear these if they’re stressing cashflow, but check with your accountant first.
- Investment or business debt – often deductible, so you may keep some of this if it supports your income.
Remember, loan purpose, not the property, drives interest deductibility (fact 2). If you’re rolling debts into a new structure, use clean loan splits so you can prove what’s deductible later.
There’s also a behavioural risk: after consolidating or paying out cards, many people quietly run them back up (fact 20). If you clear cards with sale proceeds, cut the limits or close the cards the same week.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.