
Article
Using Eastern Suburbs home equity for school fees and big bills
Written and reviewed by James Chee, CPA · Last reviewed
How Eastern Suburbs families can safely use home equity to cover private school fees and big life costs without turning short-term needs into 30 years of mortgage stress.
Key Takeaway
This guide explains how Eastern Suburbs families can safely use home equity to pay school fees and big life costs, recommending any new split be repaid within 3–7 years while keeping total housing repayments under 30–35% of net income. It compares top-ups, refinance and separate splits, and shows how long terms can make total interest on school fees exceed the original cost. The key action is to model a clear 3–7 year repayment plan before drawing a dollar.
Watch the short answer
Home loan tips for digital creators and freelancers
If you’re weighing up using home equity, this video explains home loan basics that also apply to digital creators and freelancers.
Read the transcript
If you earn your revenue through digital creator platforms or rolling freelance contracts, standard retail banks are programmed to treat you like a high-risk borrower. When their automated systems look for a standard corporate payslip, and find multiple payment platforms instead, they hit 'reject'. We don't use those systems. We use alternative documentation pathways specifically built for modern digital income. We utilise a 12-month smoothing model that verifies your true capacity straight from your bank deposits, entirely bypassing the outdated PAYG paperwork gatekeepers. DM me, 'CREATOR', to get your digital income assessed by a human.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
How Eastern Suburbs families can safely use home equity to cover private school fees and big life costs without turning short-term needs into 30 years of mortgage stress.
Read the full guide on tailoredloans.sydneyYou can use home equity to pay private school fees and big life costs in the Eastern Suburbs, but it’s only wise if: (1) the new split is modest, (2) you can clear it in 3–7 years, and (3) total housing repayments stay under roughly 30–35% of your after‑tax income. If you can’t tick all three, you’re better off changing the spending plan, not stretching the mortgage.
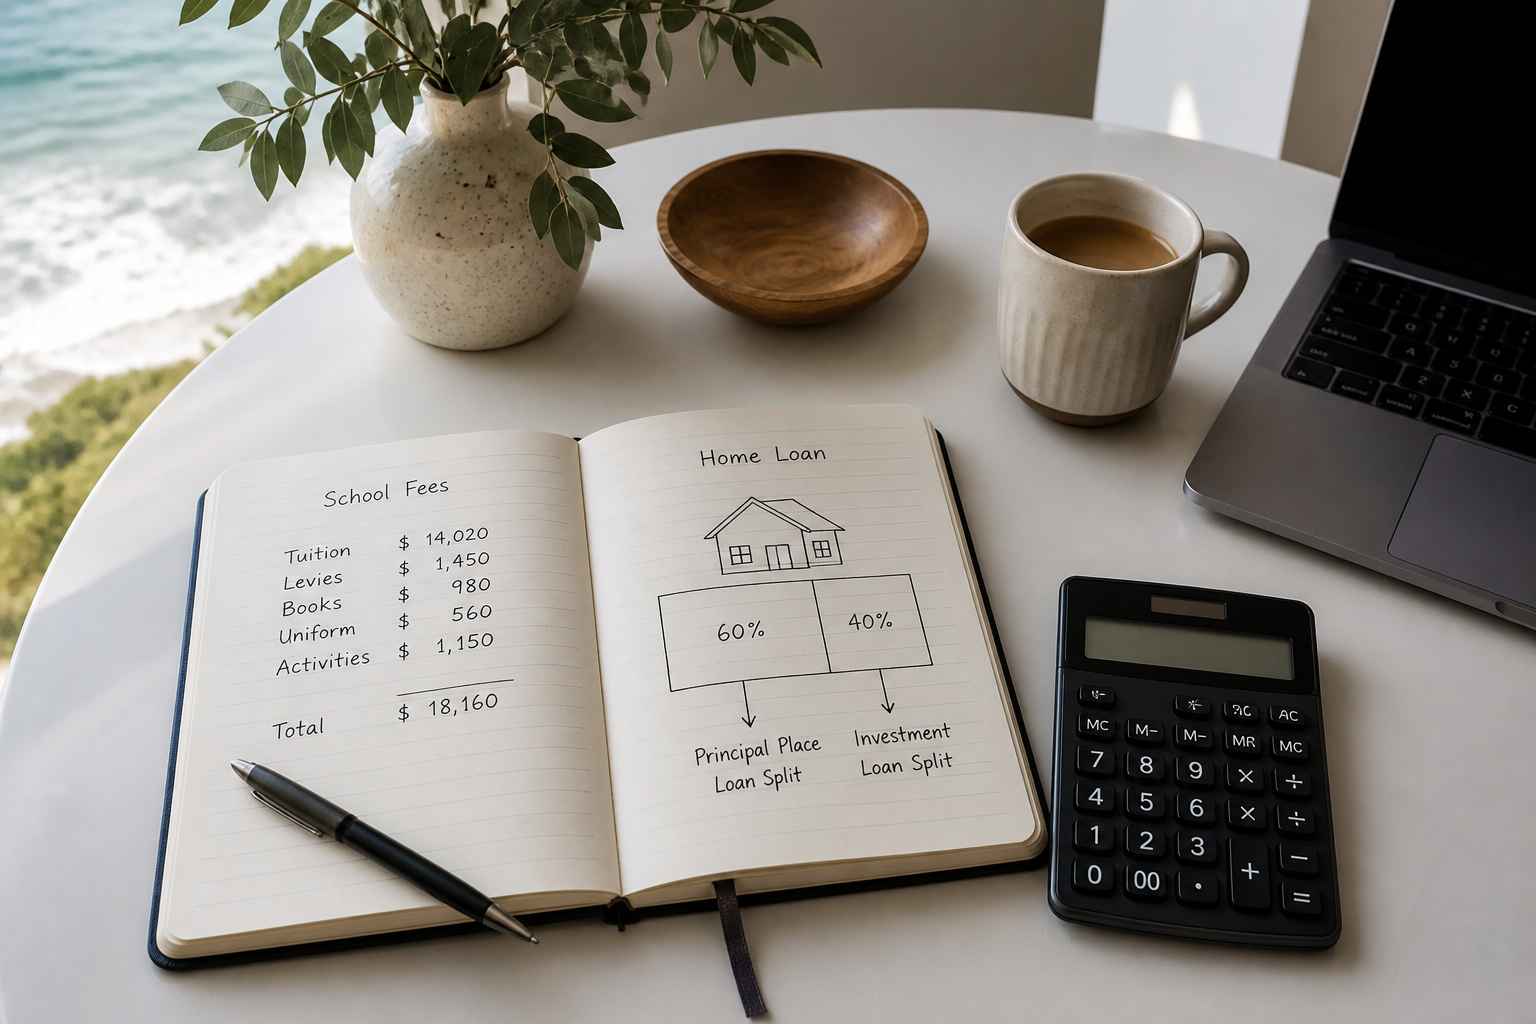
Step 1: Decide if using equity is actually sensible
Think of equity release as a short‑term cashflow bridge, not a lifestyle subsidy.
Generally reasonable uses in the East:
- 3–5 years of private school fees during a tight income period
- One‑off medical or family law costs
- Temporary business or self‑employment wobble where income is likely to recover
- Time‑bound support for parents or adult children
Red flags:
- Funding ongoing lifestyle (holidays, cars, everyday spending)
- No plan to pay it out in 3–7 years
- Total repayments already over 35–40% of after‑tax household income
- Cash buffer under 3 months of essential costs (including loans)
Roy Morgan estimates around 28% of mortgage holders are already at risk of stress. If you’re in that zone, adding more debt for non‑essential costs is dangerous.
For a deeper framework on when it’s worth it, see When It Makes Sense To Use Home Equity For Life’s Big Bills.
Step 2: Match the loan term to the expense
Borrowing for short‑life expenses over 25–30 years is where smart families quietly lose six figures.
Worked example – Sydney private school fees
- Assume $50,000 per year for 6 years = $300,000 total
- You release $300,000 against your Woollahra home at 6.0% p.a.
Compare two options:
| Strategy | Term | Approx monthly | Total interest | Comment |
|---|---|---|---|---|
| A: 30‑year blended | 30 yrs | ~$1,798 | ~$347,000 | You pay more interest than the original fees |
| B: 7‑year split | 7 yrs | ~$4,382 | ~$67,000 | Tougher cashflow, far lower lifetime cost |
Numbers are indicative only, but the pattern is real: stretch school fees over 30 years and you can easily pay more in interest than the education itself.
Rule of thumb:
If you wouldn’t take a 7‑year personal loan for it, think very hard before adding it to a 30‑year mortgage.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 3 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.