
Article
Using Home Equity Safely: Renovations, Investments and Buffers
How to release equity safely for renovations, investments or a cash buffer, with broker-designed structures that respect APRA LVR limits and protect your home.
Key Takeaway
Equity release can safely fund renovations, investments or a cash buffer when borrowers cap total LVR near 80%, keep 3–6 months of repayments in offset, and separate loan splits by purpose. APRA requires lenders to apply at least a 3% serviceability buffer, meaning repayments are tested above current interest rates. The key actionable step is to map a broker-designed structure this week that sets clear LVR limits, buffers and loan purposes before touching existing equity.
This topic is covered in full on Tailored Loans Sydney
How to release equity safely for renovations, investments or a cash buffer, with broker-designed structures that respect APRA LVR limits and protect your home.
Read the full guide on tailoredloans.sydneyReleasing equity from your home for renovations, investments or a safety buffer is safe when you cap your total lending at a conservative loan‑to‑value ratio (LVR), keep clear cash buffers and separate each purpose into its own loan split. A broker‑designed plan makes sure you stay comfortably inside APRA rules, avoid lenders mortgage insurance (LMI) where possible, and don’t accidentally create long‑term tax headaches.
Step 1: Know how much equity you can safely touch
Lenders look at your LVR: total lending ÷ property value.
A common safe rule is to calculate usable equity at 80% LVR and leave the rest untouched.
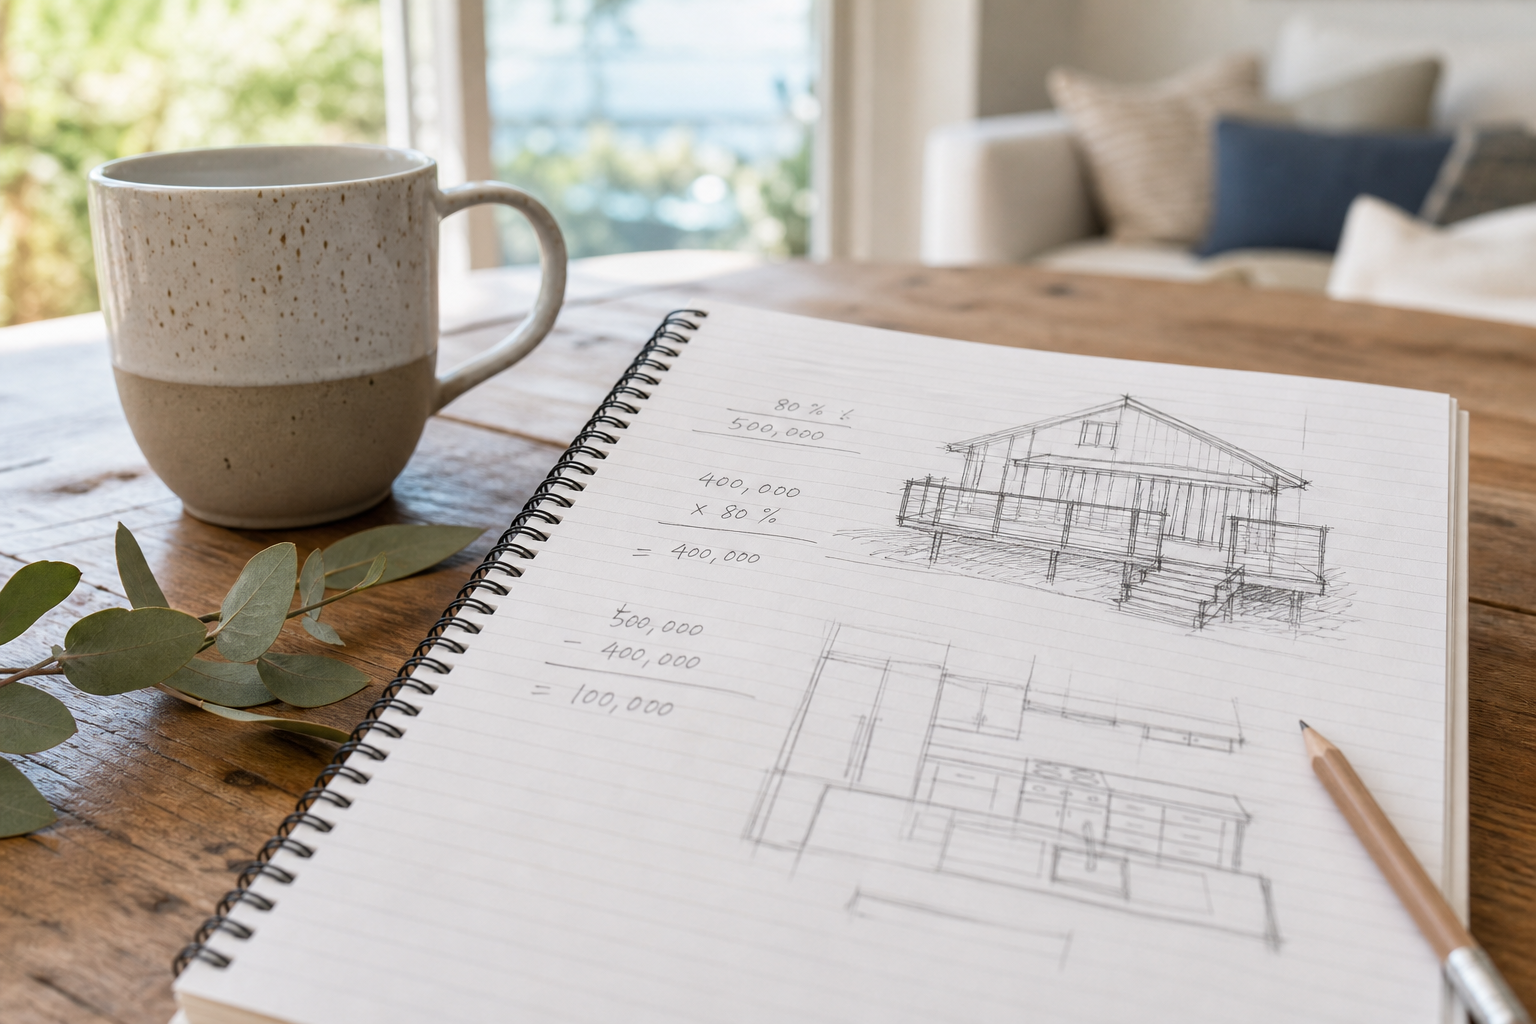
Usable equity formula
80% of current value − existing home loan balance.
If your home is worth $1.4m and your loan is $700k:
- 80% of $1.4m = $1.12m
- Usable equity ≈ $1.12m − $700k = $420k (before serviceability checks)
For many clients, we then reduce this again to protect buffers – often aiming for a total LVR of 70–80%, in line with our guidance in /insights/how-much-equity-safely-unlock-mascot-home.
Why brokers start with LVR and buffers, not just equity
A broker will test three things before recommending a number:
- Target LVR – can we keep you at or below 80% to avoid LMI and give flexibility?
- Repayments under stress – can you still afford them with a 3% APRA buffer on the rate?
- Cash buffer – will you have at least 3–6 months of total loan repayments in offset after the equity release?
If any of these fail, the safe answer is: release less, or not yet.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 3 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.