
Article
Financing a Move Into Bronte’s Best School Catchments, Step by Step
A clear, numbers-first guide to financing a move into key Bronte, Waverley and Clovelly school zones without overstretching your family budget.
Key Takeaway
This article explains how to finance a move into key Bronte, Waverley and Clovelly school zones by sizing your budget under a 3% APRA serviceability buffer and stress-testing repayments at 35–40% of after-tax income. It outlines how to compare selling versus keeping your current home, use equity for deposits, and handle bridging risk. Readers get a one-week, step-by-step action plan to confirm borrowing power, shortlist school catchment pockets, and prepare for pre-approval before enrolment deadlines.
This topic is covered in full on Tailored Loans Sydney
A clear, numbers-first guide to financing a move into key Bronte, Waverley and Clovelly school zones without overstretching your family budget.
Read the full guide on tailoredloans.sydneyParents moving into Bronte, Waverley or Clovelly for school zones are usually paying a premium, so the finance question is simple: how much can you safely spend, after stress-testing repayments at rates 3% higher, and should you sell, keep or rent your current home to get there? If you answer that clearly before you start bidding, you can target the right pockets and avoid last‑minute panic before enrolment cut‑offs.
1. Understand the Bronte school-zone price premium
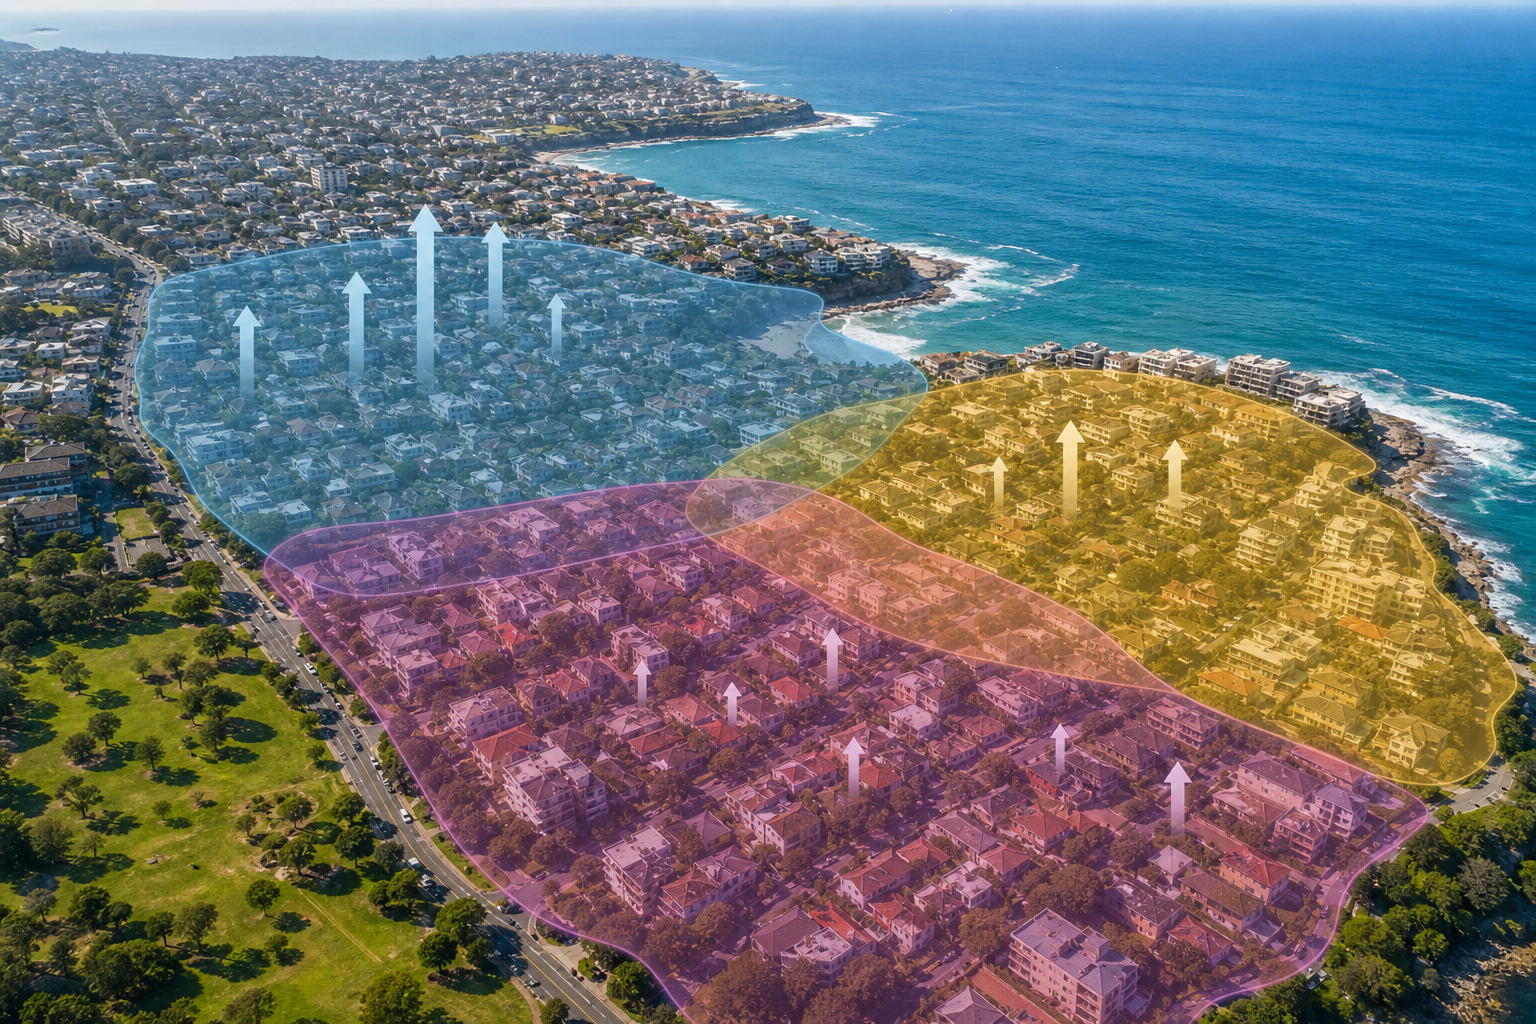
Families aren’t just buying bricks in Bronte; they’re buying into catchments for quality primary schools and selective paths in the Eastern Suburbs. That shows up in the numbers.
Quick answer: allow for a meaningful price step‑up versus non‑zone suburbs and test that against your income under a 3% rate buffer. Use that result, not just online estimates, as your working budget.
1.1 Typical price gaps and what they mean for loans
Exact premiums vary street by street, but in practice:
- Houses and larger semis in key Bronte/Waverley catchments commonly sit well over $3m.
- Family‑sized apartments and smaller semis in Bronte/Clovelly pockets may be $1.8m–$3m.
- Neighbouring, less prized school pockets can be 10–20% cheaper.
Assuming 80% LVR and indicative numbers only:
| Target price | 20% deposit | Loan size (80% LVR) | P&I @ 6.5%* | P&I @ 9.5% (stress) |
|---|---|---|---|---|
| $1.8m | $360k | $1.44m | ~$9,100/m | ~$12,100/m |
| $2.4m | $480k | $1.92m | ~$12,100/m | ~$16,100/m |
| $3.0m | $600k | $2.4m | ~$15,200/m | ~$20,200/m |
*30‑year P&I, owner‑occupier, rates illustrative only. Always check current products.
If stressed repayments land above ~35–40% of after‑tax household income (see /insights/bronte-debt-load-unsustainable-warning-signs), treat that as a warning, not a target.
2. Decide: sell first, buy first or keep and rent?
Your next decision is whether to unlock maximum borrowing power by selling, or try to keep your existing home as an investment.
2.1 If you sell first
Selling first usually gives the cleanest finance picture:
- Clear how much cash you have for deposit and costs.
- Lower overall debt at settlement, which means easier servicing.
- Less chance of needing bridging finance.
This is often the safest path for families prioritising school stability over investment upside.
2.2 If you buy first (bridging or high LVR)
Buying first can work in fast‑moving pockets but stacks risk: you may hold two loans at once.
Read the detailed tests in /insights/bridging-finance-eastern-suburbs-upgraders-keep-rent-or-sell, but in brief you should:
- Test borrowing capacity with a 3% buffer on both loans.
- Use realistic sale price, not best‑case.
- Hold at least 6–12 months of stressed repayments plus living costs in offset.
If the numbers only work on perfect assumptions, scale back the purchase or switch to sell‑then‑buy.
2.3 If you keep the old place as an investment
Keeping your former home can build long‑term wealth, but:
- Banks shade rental income (often 70–80%).
- You’ll carry higher total debt, which eats into your school‑zone budget.
- You must keep loan purpose and splits clean for future tax deductibility (see knowledge fact 1).
Often, upgrading for schools and keeping the old place only works when your combined income is strong and you’re comfortable with high but well‑buffered leverage.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.