
Article
Heritage overlays in Bellevue Hill, Vaucluse and Rose Bay: risk or edge?
Heritage overlays in Bellevue Hill, Vaucluse and Rose Bay can shrink your buyer pool and bank valuation – or protect scarcity and long‑term value. This guide shows how they really affect renovation options, lending, and resale, and how to decide if a specific property is a value trap or a hidden asset.
Key Takeaway
Heritage overlays in Bellevue Hill, Vaucluse and Rose Bay affect value because they restrict demolition and major alterations, which often reduces perceived development potential and bank valuations by narrowing the future buyer pool. However, overlays can also protect character streetscapes and scarcity, supporting long‑term price resilience in blue‑chip areas. Buyers should treat each property individually, test renovation paths with council and valuers, and model finance with buffers so they’re paid for restrictions rather than overpaying for potential they can’t unlock.
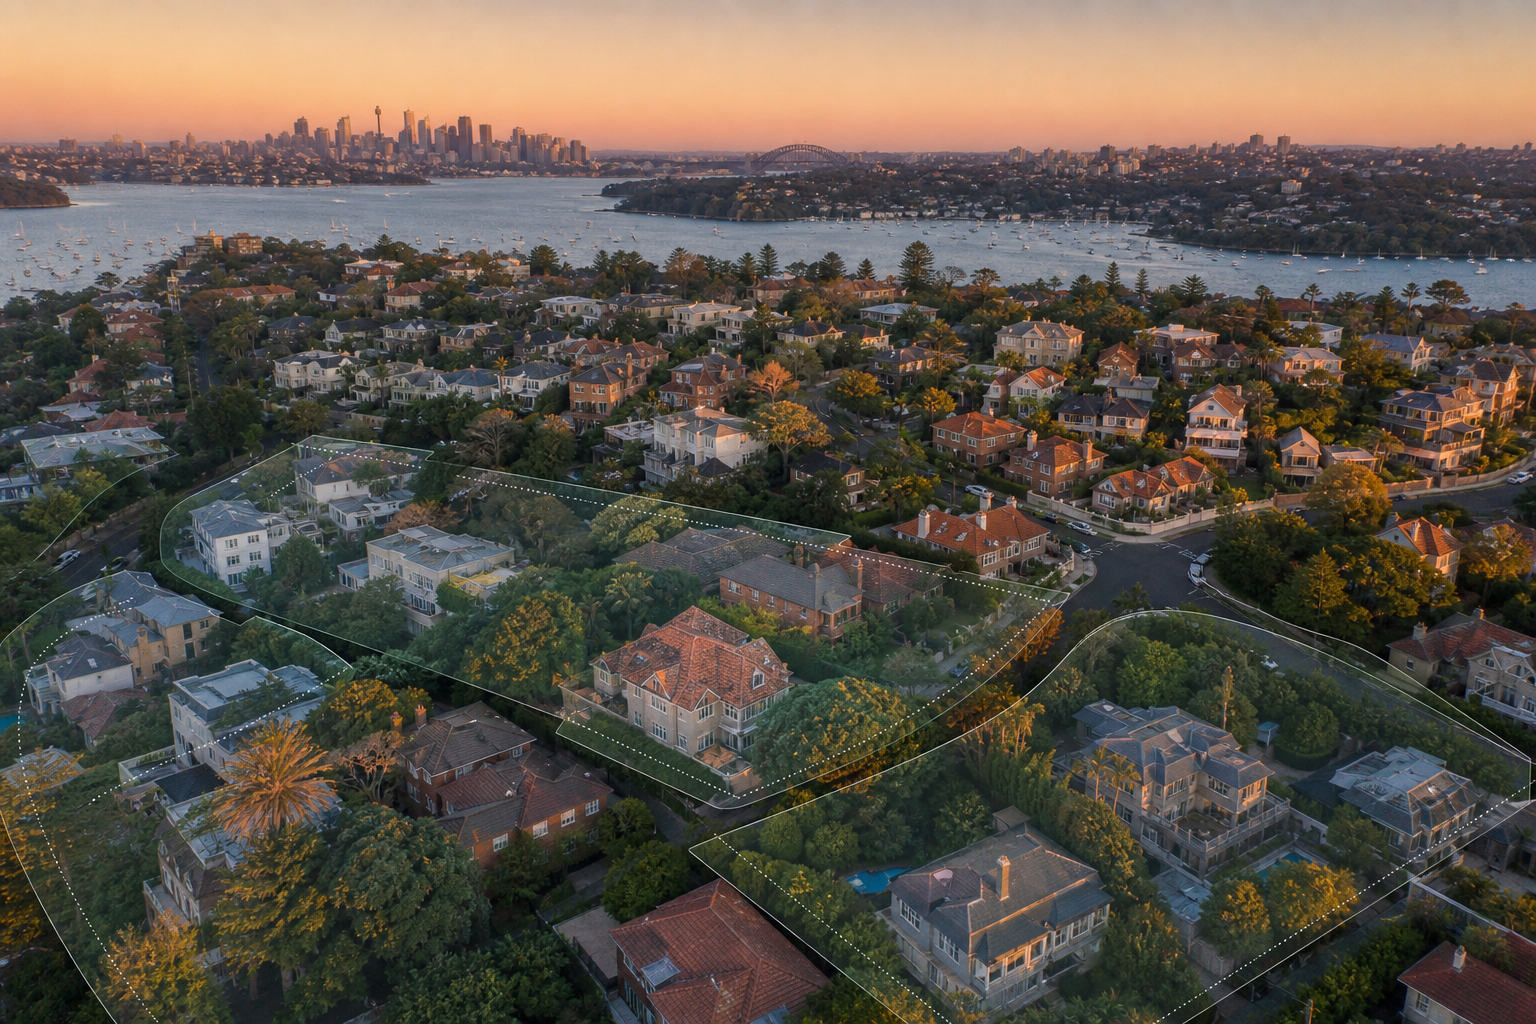
This topic is covered in full on Tailored Loans Sydney
Heritage overlays in Bellevue Hill, Vaucluse and Rose Bay can shrink your buyer pool and bank valuation – or protect scarcity and long‑term value. This guide shows how they really affect renovation options, lending, and resale, and how to decide if a specific property is a value trap or a hidden asset.
Read the full guide on tailoredloans.sydneyHeritage overlays in Bellevue Hill, Vaucluse and Rose Bay can either cap your upside or quietly protect your value. A heritage overlay is a planning control that restricts demolition and certain alterations so that a building, streetscape or conservation area keeps its character. For buyers, owners and investors, the real question is simple: does this specific overlay leave you with a safe, financeable, liveable home – and enough upside for the price you’re paying?
Below is a decision‑grade framework you can use this week to test a property, a renovation idea or a refinance in Sydney’s east.
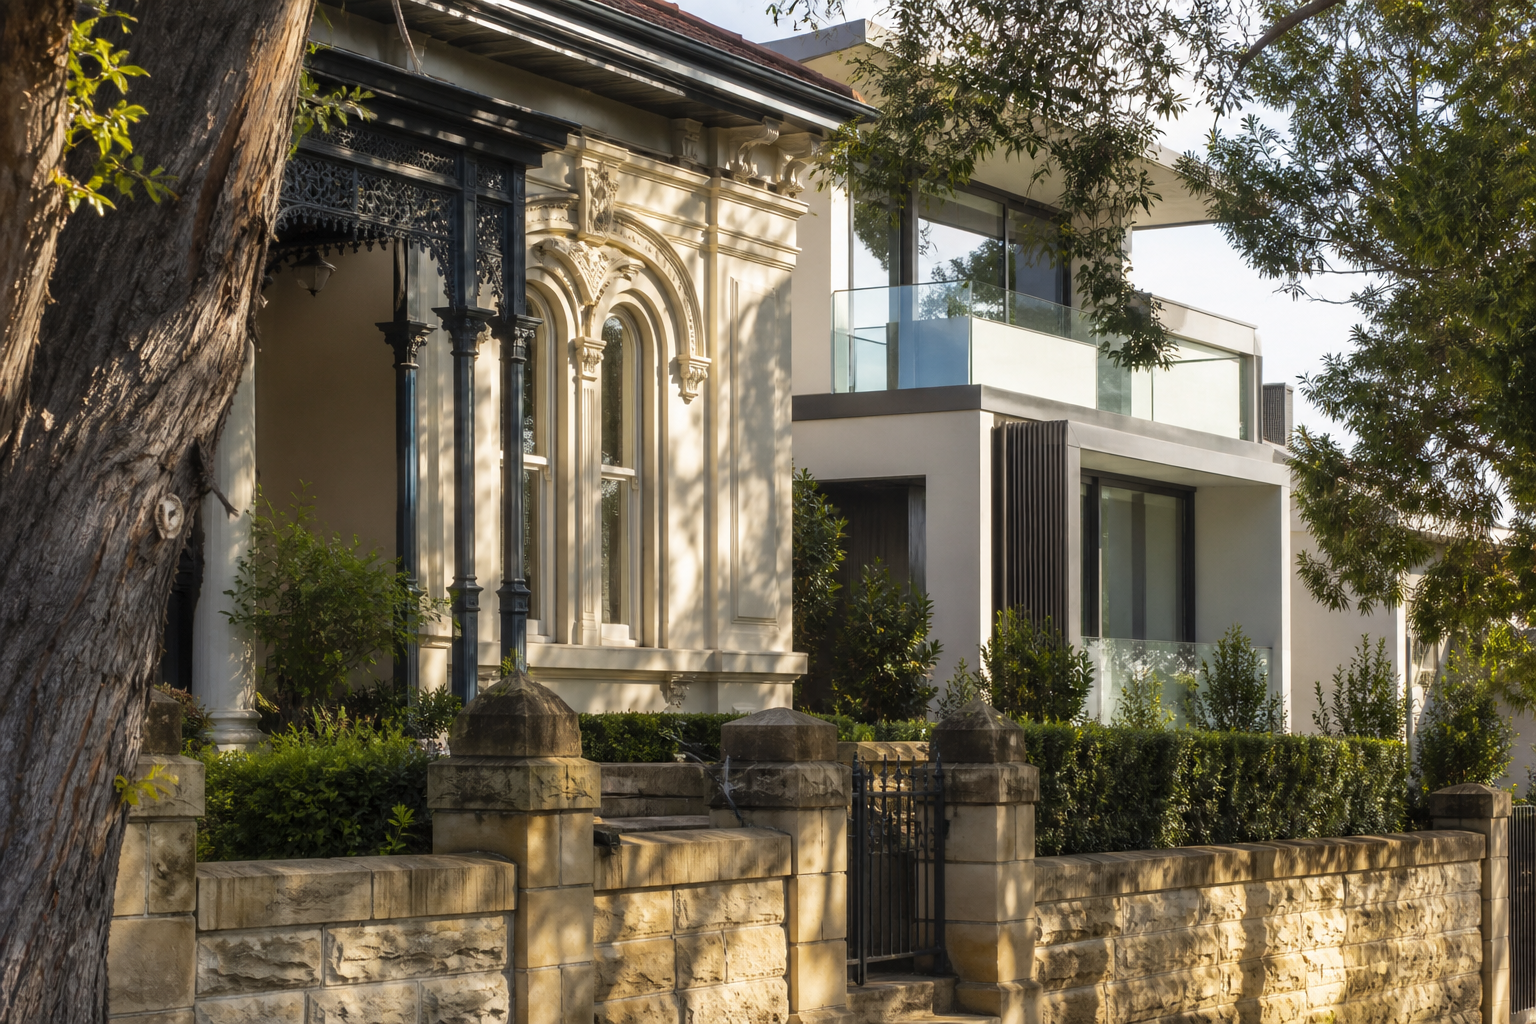
1. What a heritage overlay really means in Sydney’s east
1.1 Heritage overlay vs heritage item vs conservation area
In Woollahra and Waverley councils (covering Bellevue Hill, Vaucluse and Rose Bay), you’ll typically see three related concepts on the planning maps:
- Heritage item – an individual building or feature with specific heritage significance.
- Heritage conservation area (HCA) – a broader precinct where the overall character is protected.
- Heritage overlay / clause – the rules in the Local Environmental Plan (LEP) and Development Control Plan (DCP) that govern what you can and can’t do.
Each brings different practical constraints. A listed heritage item can have very tight controls on demolition and façade changes. A conservation area may focus more on street presentation while allowing more flexibility at the rear.
1.2 Typical constraints you’ll run into
Banks and valuers care less about the exact clause number and more about the practical effect:
- Demolition or major external change generally needs development consent.
- Height, bulk and roof form changes are heavily scrutinised.
- Front façade, visible side walls and roof lines usually must stay consistent with the streetscape.
- Secondary dwellings, garages and pools may be pushed behind the main building line or limited in size.
This doesn’t always mean “no renovation”. It means more design work, more consultants, longer timeframes – and sometimes a hard no to your dream scheme.
1.3 Why lenders and valuers care so much
From a bank’s point of view, two questions dominate:
- How easy is it to sell if we ever have to?
- How big is the future buyer pool?
Heritage overlays can:
- Shrink the pool of buyers to those comfortable with character homes and higher upkeep.
- Reduce speculative “developer” bidding, which can pull back end values.
- Lengthen selling time if the market turns.
That’s why heritage or overlays often sit in the background of very different bank valuations for seemingly similar homes. You’ll see this play out in detail in /insights/why-two-eastern-suburbs-properties-valued-so-differently.
2. Value trap vs hidden asset: a simple decision lens
2.1 Three tests you can run this week
To decide whether a specific heritage‑affected property is a value trap or hidden asset, run three tests:
- Livability test – Can this home work for you with modest, council‑friendly changes? If you need radical alteration to make it livable, heritage is a bigger red flag.
- Finance test – Will the overlay materially reduce bank valuation or LVR compared with a non‑heritage neighbour?
- Resale test – Is there a clear, durable buyer pool for this type of dwelling in this exact street, even with the overlay?
If all three are positive, the overlay is more likely a hidden asset, protecting streetscape and scarcity. If two or three are negative, you’re probably looking at a value trap.
2.2 How overlays can quietly protect value
In blue‑chip pockets of Bellevue Hill, Vaucluse and Rose Bay, overlays can actually:
- Prevent out‑of‑scale new builds that block views or sunlight.
- Maintain consistent character that appeals to downsizers and professionals.
- Limit supply of comparable homes, supporting prices through cycles.
Work from ABS “Total Value of Dwellings” data shows that NSW blue‑chip suburbs often experience smaller price swings than fringe locations. Overlay‑protected character streets are one reason certain postcodes in Sydney’s east hold value better when prices fall – a theme explored in /insights/eastern-suburbs-postcodes-that-hold-value-best-when-prices-fall.
2.3 When it becomes a value trap
Overlays tend to become value traps when:
- You’re paying a “future development” price for land you can’t meaningfully intensify.
- Practical renovation options are so narrow that only a small niche of heritage enthusiasts would buy at your exit price.
- Ongoing maintenance (timber, slate, sandstone) and compliance costs soak up your cashflow.
In those cases, you’re carrying extra risk for upside you can’t actually unlock.
3. How heritage overlays affect bank valuations and lending
3.1 The valuer’s checklist on heritage properties
When a valuer steps onto a heritage‑affected site, they’re effectively scoring:
- Development potential – Can the building be extended at the rear or underbuilt? Or is the envelope largely fixed?
- Condition and compliance – Are there obvious deferred maintenance issues likely to be expensive under heritage rules?
- Marketability – How many buyers will be turned off by restricted changes, higher upkeep or lack of garaging/pool potential?
They then compare your property with recent sales of similar constrained homes, not with the free‑to‑knockdown house three doors down.
That’s one reason why two homes in the same street can get very different valuation numbers, as illustrated in /insights/why-two-eastern-suburbs-properties-valued-so-differently.
3.2 Typical lender responses you may see
Banks don’t have one uniform policy on heritage, but in practice you might see:
- Conservative valuations relative to purchase price.
- Tighter maximum LVRs (e.g. 70–80% instead of 90–95%) on some properties.
- Extra questions about renovation plans and costings.
Non‑bank and private credit lenders may be more flexible, but usually at a higher interest margin. Recent RBA research (Feb 2026) notes the growth of non‑bank credit as one reason why overall financial conditions can feel looser than the cash rate alone suggests – useful, but you’re still paying for risk.
3.3 Example: Same street, two different valuations
| Property | Overlay status | Land size | Potential | Indicative bank LVR range* | Likely valuer stance |
|---|---|---|---|---|---|
| A | No overlay | 650 m² | Knockdown‑rebuild, duplex potential (subject to zoning) | Up to 90–95% (if other factors OK) | Values full development potential; strong competition from developers |
| B | Heritage item in HCA | 650 m² | Rear extension only, façade fixed, tight height control | 70–80% with some lenders | Compares to other constrained homes; discounts speculative upside |
*Indicative only – actual LVR depends on lender, borrower profile and broader risk policy. Not a rate or approval quote.
If you pay close to Property A pricing for Property B land, you’re taking developer‑level risk without developer‑level flexibility.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 6 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.