
Article
Getting a Home Loan When You Owe the ATO: What Really Matters
Written and reviewed by James Chee, CPA · Last reviewed
You can often get a home loan even if you owe the ATO, but only when the debt is disclosed, under control and your cash flow still passes lender stress tests. This guide shows small‑business owners the real rules, what to fix first and when to apply.
Key Takeaway
Australian small‑business owners can often still get a home loan with ATO debt if the tax is fully disclosed, on a formal payment plan, and post‑tax cash flow comfortably passes lender stress tests with a 3% interest rate buffer. Lenders weigh the size and age of ATO arrears, lodgement history, and business stability more than the mere existence of debt. The key actionable step is to move from ‘ignored’ to ‘managed’ ATO debt before lodging a mortgage application.
Watch the short answer
Maxed Out on Your Residential Borrowing Capacity?
If ATO debt is limiting your options, this video explains what to consider when your residential borrowing capacity is already maxed out.
Read the transcript
Are you maxed out on your residential borrowing capacity? It's time to pivot to commercial. Many investors hit a wall where retail banks cut off their residential borrowing, but commercial lending operates on an entirely different rulebook. Lenders look heavily at the lease strength and the yield of the commercial asset itself, often allowing you to borrow outside of your personal PAYG constraints. It's the ultimate pathway to scaling your portfolio when the residential door closes. Ready to scale? DM me the word 'COMMERCIAL' to pivot your investment strategy.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
You can often get a home loan even if you owe the ATO, but only when the debt is disclosed, under control and your cash flow still passes lender stress tests. This guide shows small‑business owners the real rules, what to fix first and when to apply.
Read the full guide on tailoredloans.sydneyYou can sometimes get a home loan while you owe the ATO, but only if the debt is fully disclosed, on a realistic payment plan, and your post‑tax cash flow still passes lender stress tests. If the debt is large, ignored, or your BAS and returns are overdue, most mainstream banks will either decline you or slash your borrowing power.
How lenders really treat ATO debt
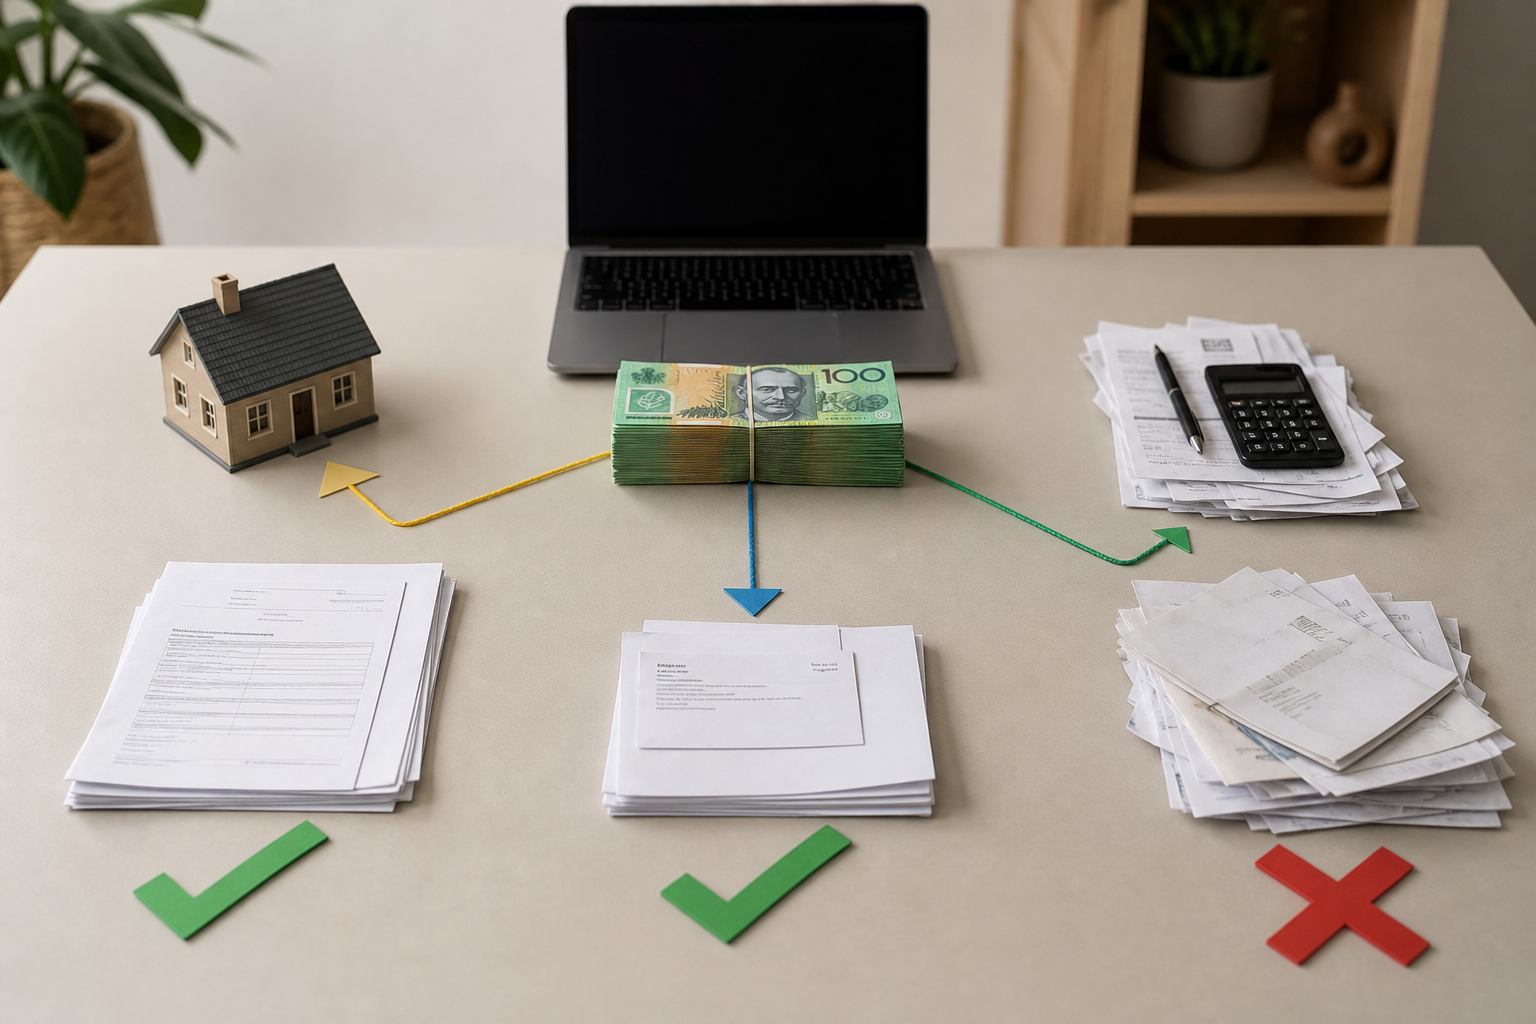
For small‑business owners, lenders don’t just ask “Do you owe tax?” — they ask three questions:
- Is everything lodged? (tax, BAS, PAYG)
- Is the ATO debt managed? (formal plan vs hoping it goes away)
- Can you safely afford mortgage + ATO + business costs at buffered rates?
ATO debt is usually treated as priority debt.
If you get into trouble, the ATO tends to get paid before the bank.
That’s why undisclosed or messy tax positions are a red flag.
For more detail on how banks frame this risk, see /insights/ato-debt-payment-plans-home-loans-what-lenders-think.
What usually kills an application
Lenders get very nervous when they see:
- Unlodged returns or BAS for the last 1–2 years.
- ATO payment plans that don’t actually match your cash flow (you’re already missing instalments).
- Garnishee notices on bank statements.
- Evidence you’re using home loan redraw as recurring working capital for BAS, wages or GST — that effectively turns your mortgage into an overdraft and concentrates business risk on the family home.
Any of these can push you from a prime lender into specialist territory, with higher rates and lower borrowing limits.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Commercial & development
Smart Debtor Finance Around Progress Claims For Builders And Tradies
Commercial & development
Construction Cashflow 101: Progress Claims, Retentions And Funding Gaps
Self-employed lending
How to clean up overdrafts and director loans before a home loan
Self-employed lending
Simple Working Capital Setups For Sole Traders That Stay Tax‑Clean
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.