
Article
Step‑By‑Step: How a Bronte Mortgage Broker Actually Gets You Approved
Written and reviewed by James Chee, CPA · Last reviewed
A clear, step‑by‑step look at how a Bronte mortgage broker takes you from first call through approval to settlement – and what you need to do each week to keep things moving.
Key Takeaway
A Bronte mortgage broker typically takes borrowers from first call to formal home loan approval in around two to four weeks by following a structured workflow: strategy call, document collection, pre‑assessment, lender selection, application, valuation, and credit decision. For Eastern Suburbs clients with $1–3m loans, keeping total repayments under 30–35% of after‑tax income when modelled at rates 3% higher is a practical safety guardrail. The key actionable step is booking a strategy call and preparing core documents before actively house‑hunting.
Watch the short answer
Why staying loyal to your bank can cost you
As you map out each step to approval, this video shows how sticking with one bank alone can quietly work against your plan.
Read the transcript
Banks don't reward loyalty, they exploit it. If you have been with the same mortgage or commercial lender for over 18 months, you are almost certainly paying a premium compared to a new customer walking in off the street. At Local Knowledge Finance, we run proactive audits to squeeze your current lender for a better rate or seamlessly transition you to a more agile pipeline. Stop donating money to bank profits. DM me 'AUDIT' right now.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
A clear, step‑by‑step look at how a Bronte mortgage broker takes you from first call through approval to settlement – and what you need to do each week to keep things moving.
Read the full guide on tailoredloans.sydneyA good Bronte mortgage broker runs a tight, repeatable process: clarify your numbers and goals, pre‑assess with several lenders, then project‑manage your loan all the way to settlement.
If you’re organised and responsive, you can usually go from first call to formal approval in 2–4 weeks, then to keys soon after.
Stage 1: First call (this week) – do you even qualify?
Your first call isn’t about picking a lender.
It’s about confirming three things:
- Can you safely borrow what you’re hoping for?
- Is the timing realistic for Bronte / Eastern Suburbs prices?
- What’s the smartest structure for tax and flexibility?
In 20–30 minutes, a good broker will ask for rough figures on income, savings, existing debts, kids, and target price range.
They’ll estimate a safe borrowing range by stress‑testing your repayments at an interest rate 3% higher than today and keeping total home/investment repayments under about 30–35% of your after‑tax income – a practical ceiling to reduce mortgage stress risk, especially in the Eastern Suburbs.
If the numbers look viable, you move straight to documents.
Stage 2: Document sprint and pre‑assessment
This is the most important – and most painful – part. The faster you move here, the faster you get approved.
What you’ll be asked for
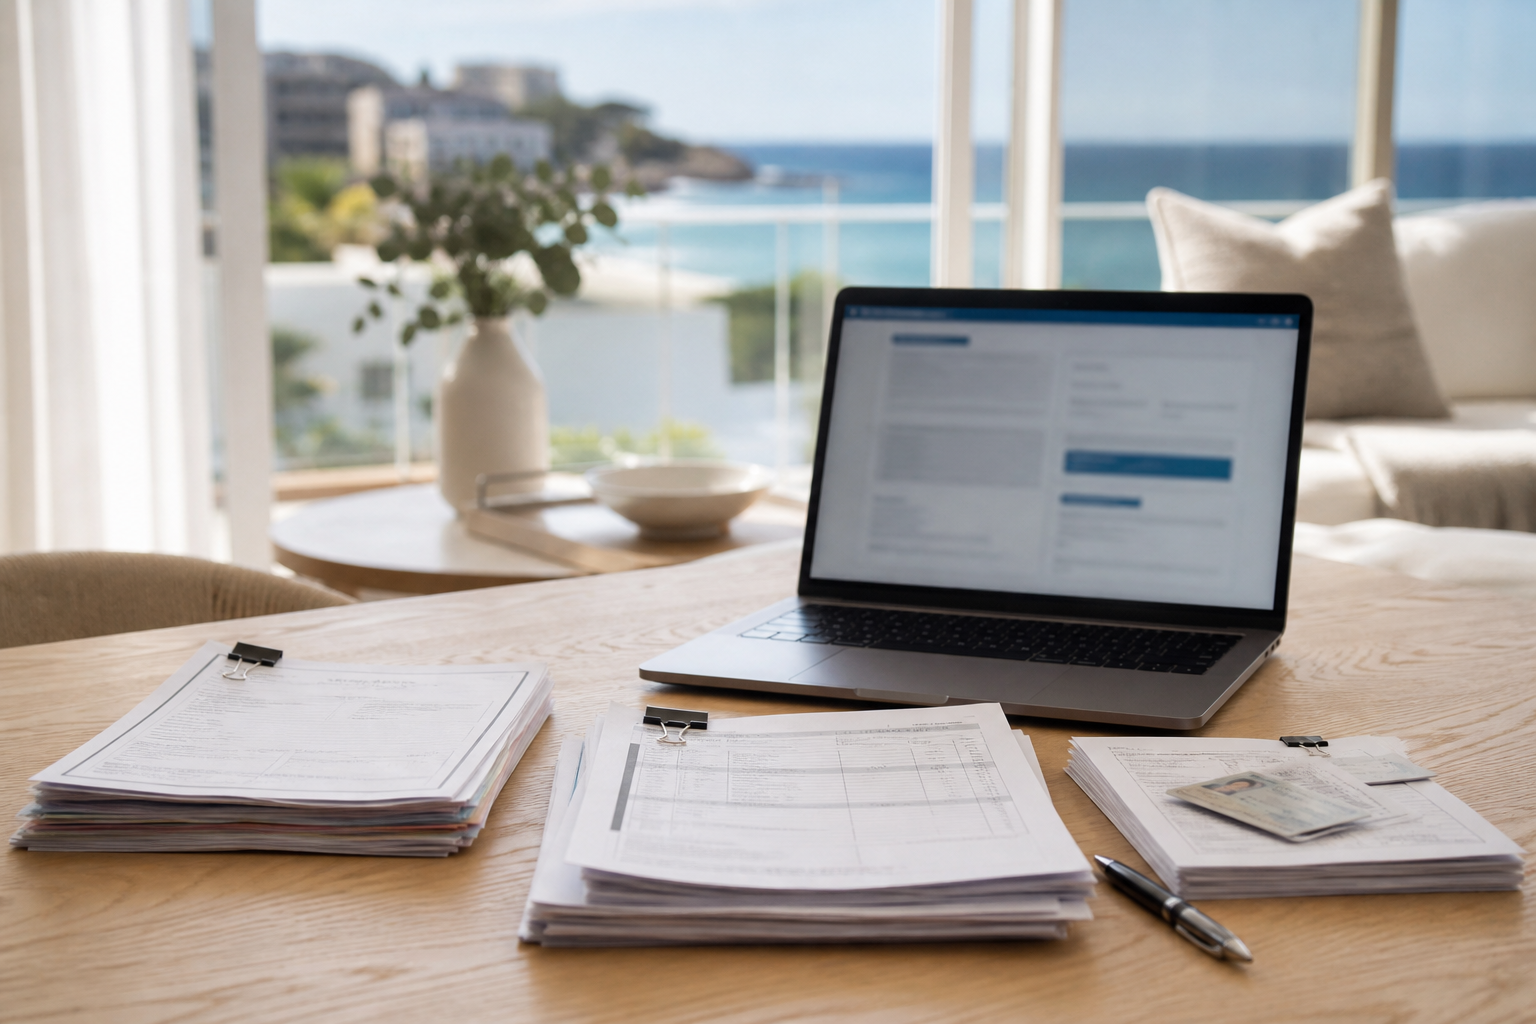
For most Bronte borrowers, your broker will need:
- ID (licence, passport)
- Last 3 months’ payslips and latest PAYG summary or 2 years’ tax returns and NOAs if self‑employed
- Last 3 months’ bank statements (everyday, savings, credit cards)
- Latest super, HECS/HELP, and any personal/vehicle loan statements
- Lease agreements and recent tax return if you have investment properties
Self‑employed or complex income (bonuses, trust distributions, company dividends) usually means more detail – but a suburb‑savvy broker should be used to this.
What the broker actually does with it
Behind the scenes, a good Bronte broker will:
- Clean the data – check your income, add‑backs, and living expenses against lender calculators and HEM benchmarks.
- Pre‑assess with multiple lenders – run your scenario through several lender calculators before lodging anything, to avoid unnecessary declines.
- Map a draft structure – e.g. multi‑splits with at least one offset linked to your non‑deductible home loan, which is particularly effective for larger Eastern Suburbs debts.
If you want the detail of this stage, see the deeper dive in /insights/from-fact-find-to-formal-approval-broker-workflow.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Suburb guides
Planning a Bronte Lifestyle Move: Balancing Beach, Commute and Budget
Suburb guides
Using Stepping‑Stone Suburbs To Eventually Afford A Bronte Home
Suburb guides
Turn Your Bronte Broker Into The Hub Of Your Property Team
Suburb guides
Using Bronte Home Equity Safely For School Fees And Big Life Costs
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.