
Article
How Eastern Suburbs Valuers Really Benchmark Sales For Your Loan
Written and reviewed by James Chee, CPA · Last reviewed
Bank valuers in Sydney’s Eastern Suburbs lean on tightly filtered recent sales, not headline record prices. Here’s how they pick comparables, treat renovations and views, and what that means for your borrowing power, equity release or refinance this year.
Key Takeaway
Bank valuers in Sydney’s Eastern Suburbs benchmark your property using 3–6 recent comparable sales in a tight radius and similar land, size and condition, typically on a conservative mid-range price, which can reduce your usable equity or borrowing power by 5–10%. They discount unapproved works, overcapitalised renovations and one-off record prices. Borrowers can act by sequencing lenders, preparing a one-page sales pack, and avoiding high LVR structures that rely on best‑case valuations.
Watch the short answer
Can you rely on an online pre‑approval certificate?
While you’re working out how valuers judge your place, this video shows whether an online pre‑approval certificate really counts with a lender.
Read the transcript
An online pre-approval certificate generated by a banking app isn't worth the paper it's printed on. It's an automated guess, not a guarantee. With the spring property rush around the corner, you need a fully assessed credit pipeline that stands up under auction pressure. Don't risk your deposit on a glitchy algorithm. DM me 'SECURE' to get your file fully credit vetted by our team this week.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Bank valuers in Sydney’s Eastern Suburbs lean on tightly filtered recent sales, not headline record prices. Here’s how they pick comparables, treat renovations and views, and what that means for your borrowing power, equity release or refinance this year.
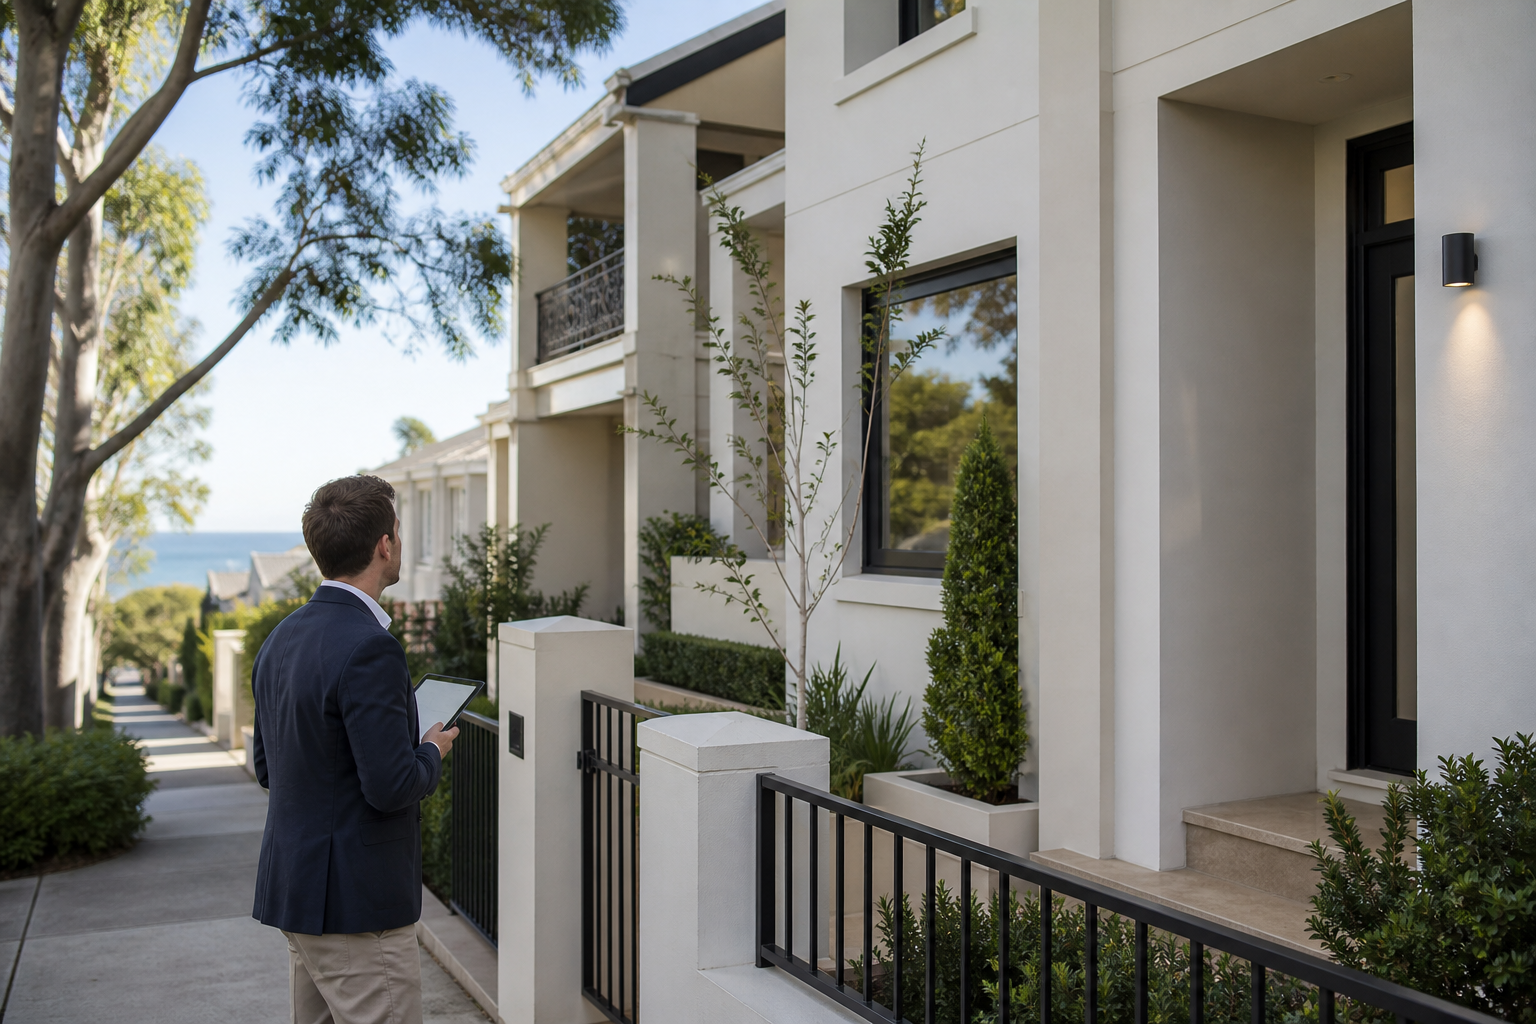
Read the full guide on tailoredloans.sydneyBank valuers in Sydney’s Eastern Suburbs benchmark your property mainly against 3–6 recent, nearby comparable sales – not online estimates, not your last auction headline, and not the agent’s best-case guide.
That conservative figure then drives how much you can borrow, your LVR, whether you pay LMI, and how much equity you can safely release.
How valuers actually benchmark Eastern Suburbs sales
When a lender orders a valuation, the valuer is working for the bank, not you. Their job is to find a supportable, defendable number, not the highest price.
The basic comparable-sales playbook:
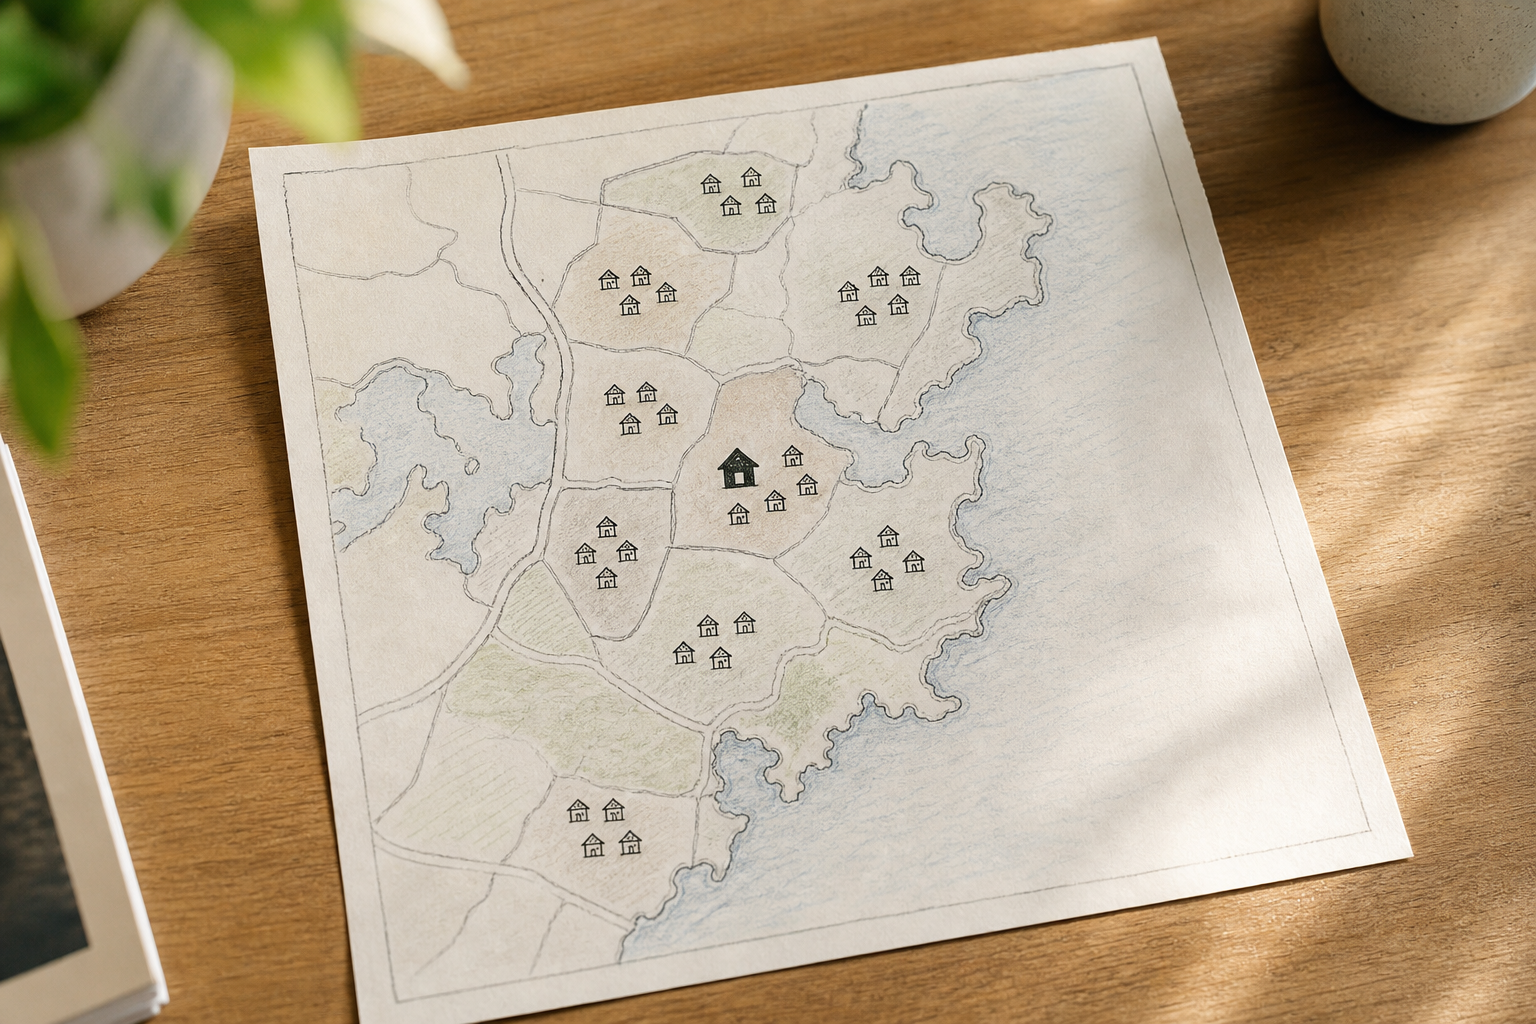
- Tight radius. Usually same suburb and ideally within a few hundred metres – especially in pockets like Bronte, Woollahra, Double Bay and Randwick where street-by-street values swing.
- Recent timeframe. Most weight goes to sales in the last 3 months, sometimes stretching to 6 in slower segments.
- Similar land and dwelling. Same side of the hill, similar land size, aspect, parking and build quality.
- Adjusted for differences. They’ll add or subtract for bedrooms, bath, parking, condition and views.
- Cross-check with trend data. They sanity‑check against suburb medians and hedonic indices, but comparables dominate.
This is why two near-identical homes can value differently if one has three clean comparables last month and the other is in a pocket with no recent, like-for-like sales.
For more on how banks layer this with postcode rules, see /insights/eastern-suburbs-postcode-risk-lists-where-banks-get-cautious.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.