
Article
How Banks Really View Clifftop and Coastal‑Risk Homes in Sydney’s East
Written and reviewed by James Chee, CPA · Last reviewed
Buying or refinancing a clifftop or exposed coastal home in the Eastern Suburbs? Here’s how banks actually assess erosion, insurance and postcode risk – and what to do this week to keep your approval on track.
Key Takeaway
Banks will lend on clifftop and coastal‑risk properties in Sydney’s Eastern Suburbs, but usually with tighter rules: lower maximum LVRs, conservative valuations, and mandatory proof of ongoing insurance. Some high‑risk streets sit on postcode risk lists that can cut borrowing power by 5–20%. Buyers should obtain insurer quotes early, budget for lower valuations, and structure loans with buffers and flexibility before bidding or waiving cooling‑off.
Watch the short answer
Can you buy a property before your tax return is done?
While you’re weighing up coastal risk and bank rules, this video explains how buying can work if your latest tax return isn’t lodged yet.
Read the transcript
Think you can't buy a property this year because your accountant hasn't finalised your 2026 tax returns? Think again. If you are a freelancer, a contractor, or a growing business, that means months of lost opportunity. We use alternative documentation pathways that completely bypass the ATO delay. We assess your true borrowing capacity using the last 6 months of your business bank deposits, getting you approved while your competitors are still waiting on paperwork. Stop waiting on tax portals to dictate your property goals. Message me 'ALTDOC', to fast-track your FY27 approval.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Buying or refinancing a clifftop or exposed coastal home in the Eastern Suburbs? Here’s how banks actually assess erosion, insurance and postcode risk – and what to do this week to keep your approval on track.
Read the full guide on tailoredloans.sydneyBanks will lend against clifftop and high‑exposure coastal properties in the Eastern Suburbs, but they usually cap LVRs, shade values and insist on strong insurance. Your borrowing power on the same income can drop sharply versus a similar house a few streets back, so you need to know the rules before you sign a 66W or bid at auction.
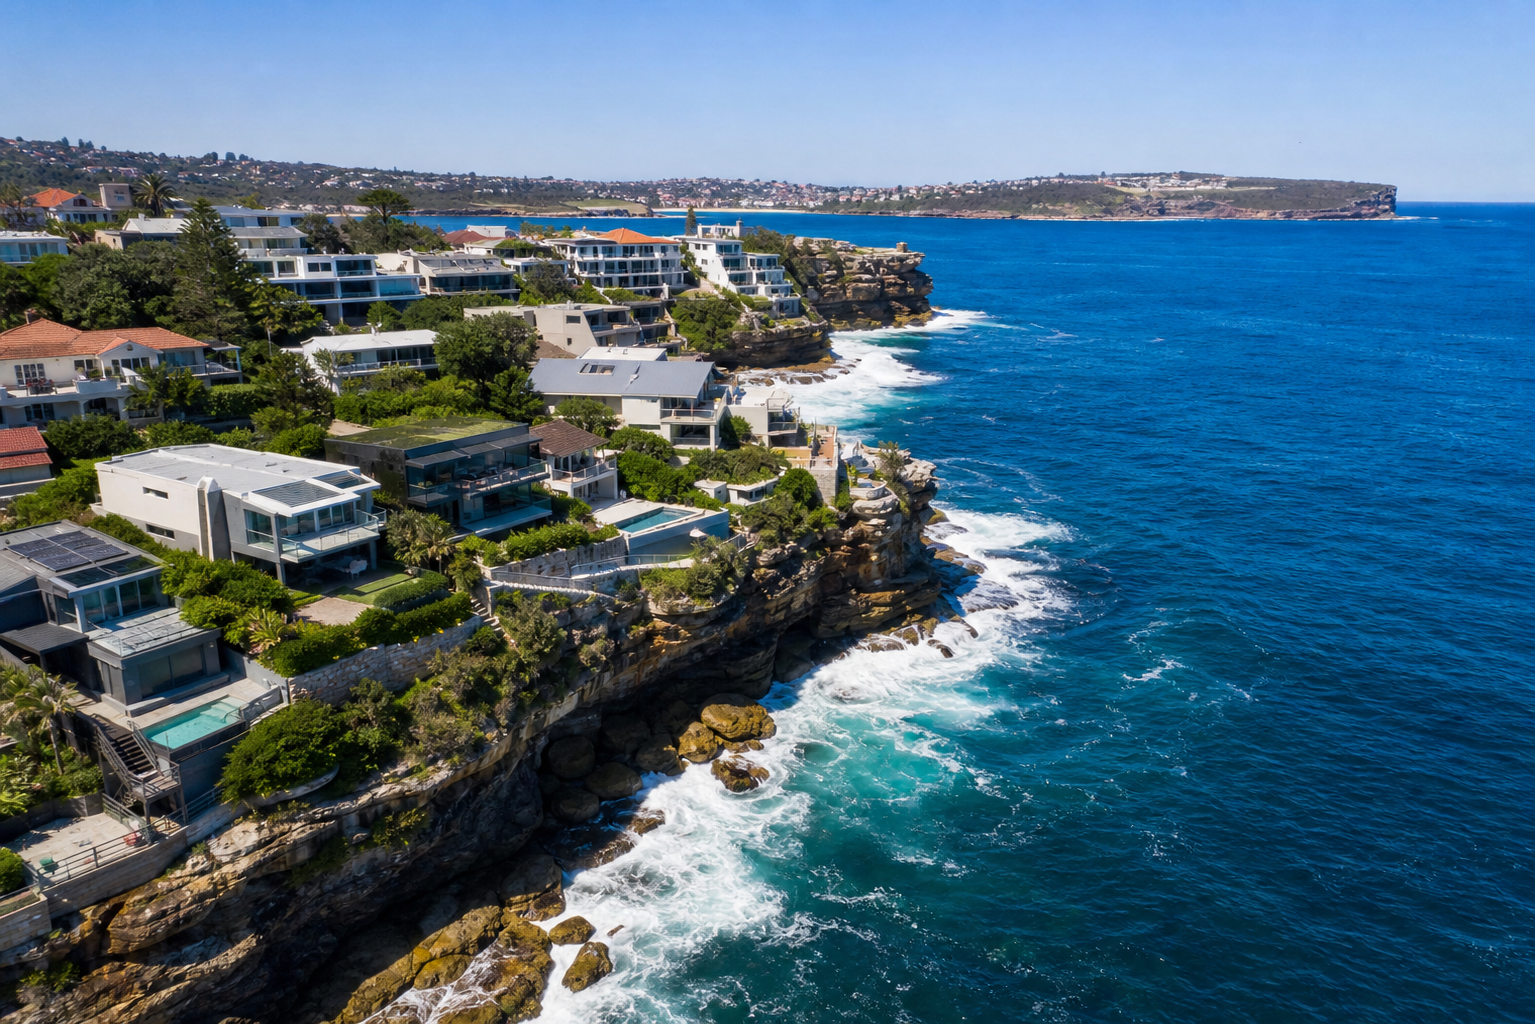
How lenders actually assess clifftop and coastal‑risk homes
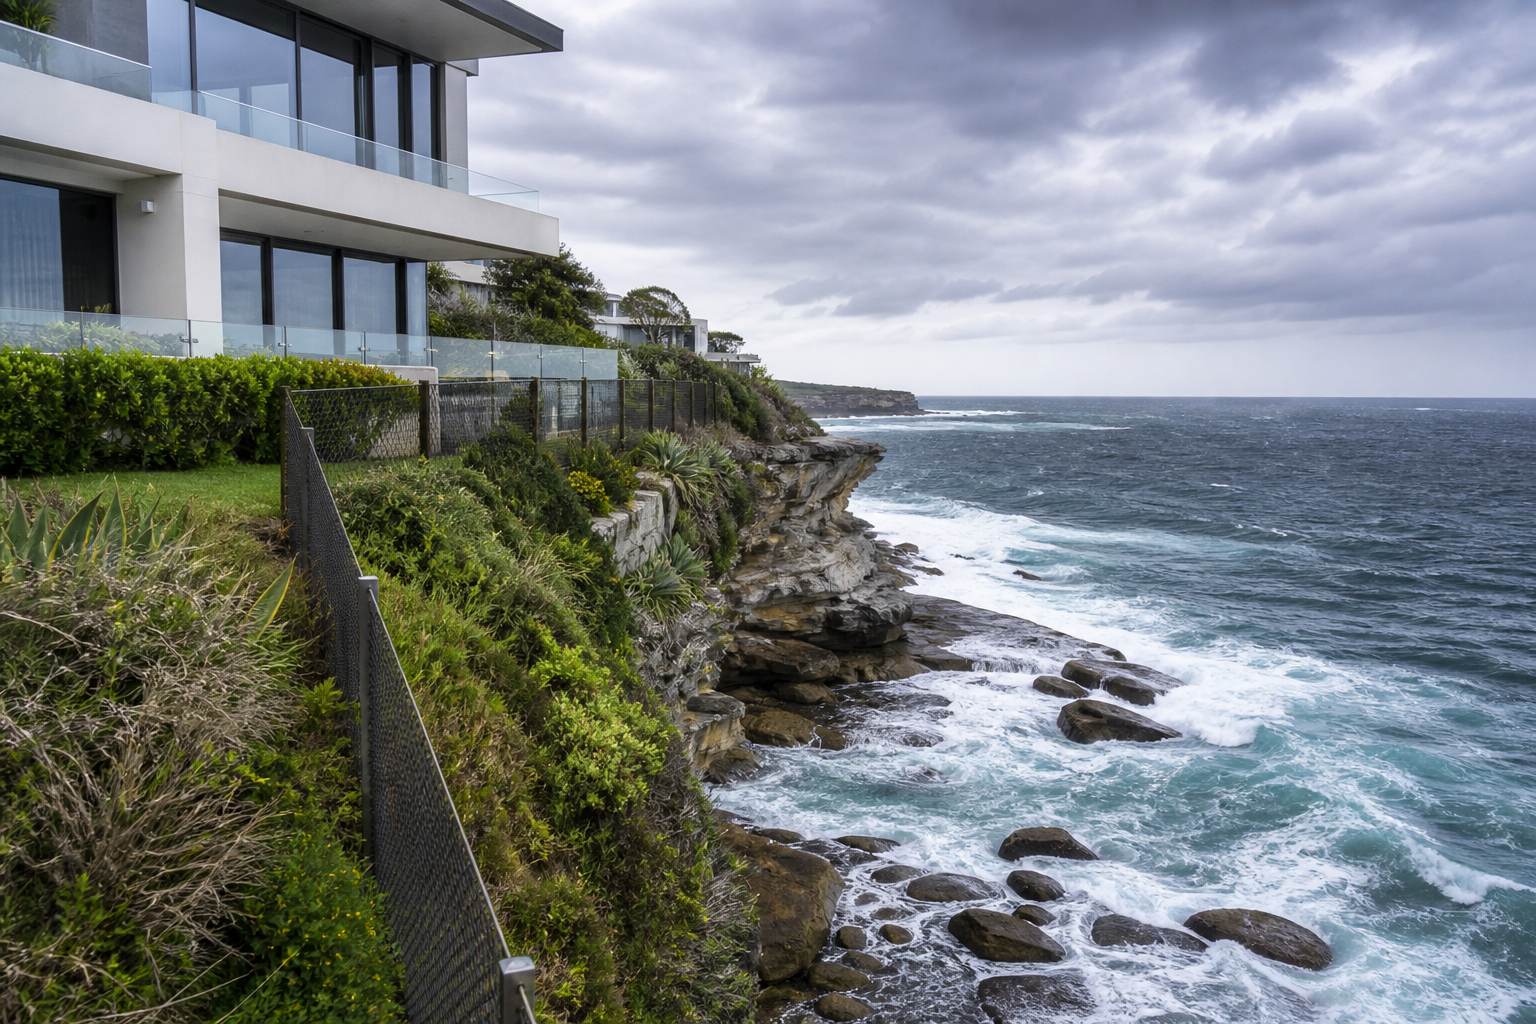
For a coastal‑exposed house in Bondi, Bronte, Tamarama or Dover Heights, lenders focus on three things:
- Security risk – erosion, landslip, storm surge, sea wall failure, access.
- Insurance risk – can you get full replacement cover at a reasonable cost?
- Marketability – how many buyers will bid if they have to sell you up?
Most banks follow similar patterns:
- Lower LVRs on clifftop/erosion‑risk blocks (often 70–80% instead of 90–95%).
- Conservative valuations – valuers discount for erosion, unstable cliffs, or restrictive DA overlays.
- Tighter servicing – APRA’s 3% buffer still applies, and some lenders apply extra shading on variable coastal income (e.g. short‑stay rent).
A clean, full‑doc borrower with 20% deposit and a safe terrace may be fine with most lenders. The same borrower on a highly exposed cliff lot may need 25–30% cash plus a stronger buffer.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.