
Article
Can You Get a Loan on a Coastal‑Risk or Landslip Property?
Written and reviewed by James Chee, CPA · Last reviewed
Buying near the cliffs in Dover Heights or Vaucluse? Lenders will still lend, but coastal‑risk and landslip zoning changes how they value, insure and structure your loan. Here’s the quick‑decision guide you can act on this week.
Key Takeaway
Australian lenders will usually lend on coastal‑risk and landslip‑zone properties in Dover Heights and Vaucluse, but they often reduce the acceptable loan‑to‑value ratio, lean on conservative valuations, and require rock‑solid insurance before settlement. Because environmental risks can materially impact property value and resale, even a 5–10% valuation haircut can force buyers to tip in an extra six‑figure deposit. Buyers should order contract reviews, valuation‑style checks and insurance quotes before signing, and structure finance buffers accordingly.
Watch the short answer
Australian expats investing back home
If you are overseas and eyeing an Australian property, this clip shows how lenders may view your foreign income.
Read the transcript
Australian expats trying to invest back home face an incredibly frustrating barrier. Major banks use massive currency shading models that slash your real foreign income by up to 30% on paper, making you look like you can't afford a loan. We use cross-border specialist lenders who evaluate your actual global earnings without the penalising retail haircuts. Keep building your Australian portfolio. DM me 'EXPAT' to check your true capacity.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Buying near the cliffs in Dover Heights or Vaucluse? Lenders will still lend, but coastal‑risk and landslip zoning changes how they value, insure and structure your loan. Here’s the quick‑decision guide you can act on this week.
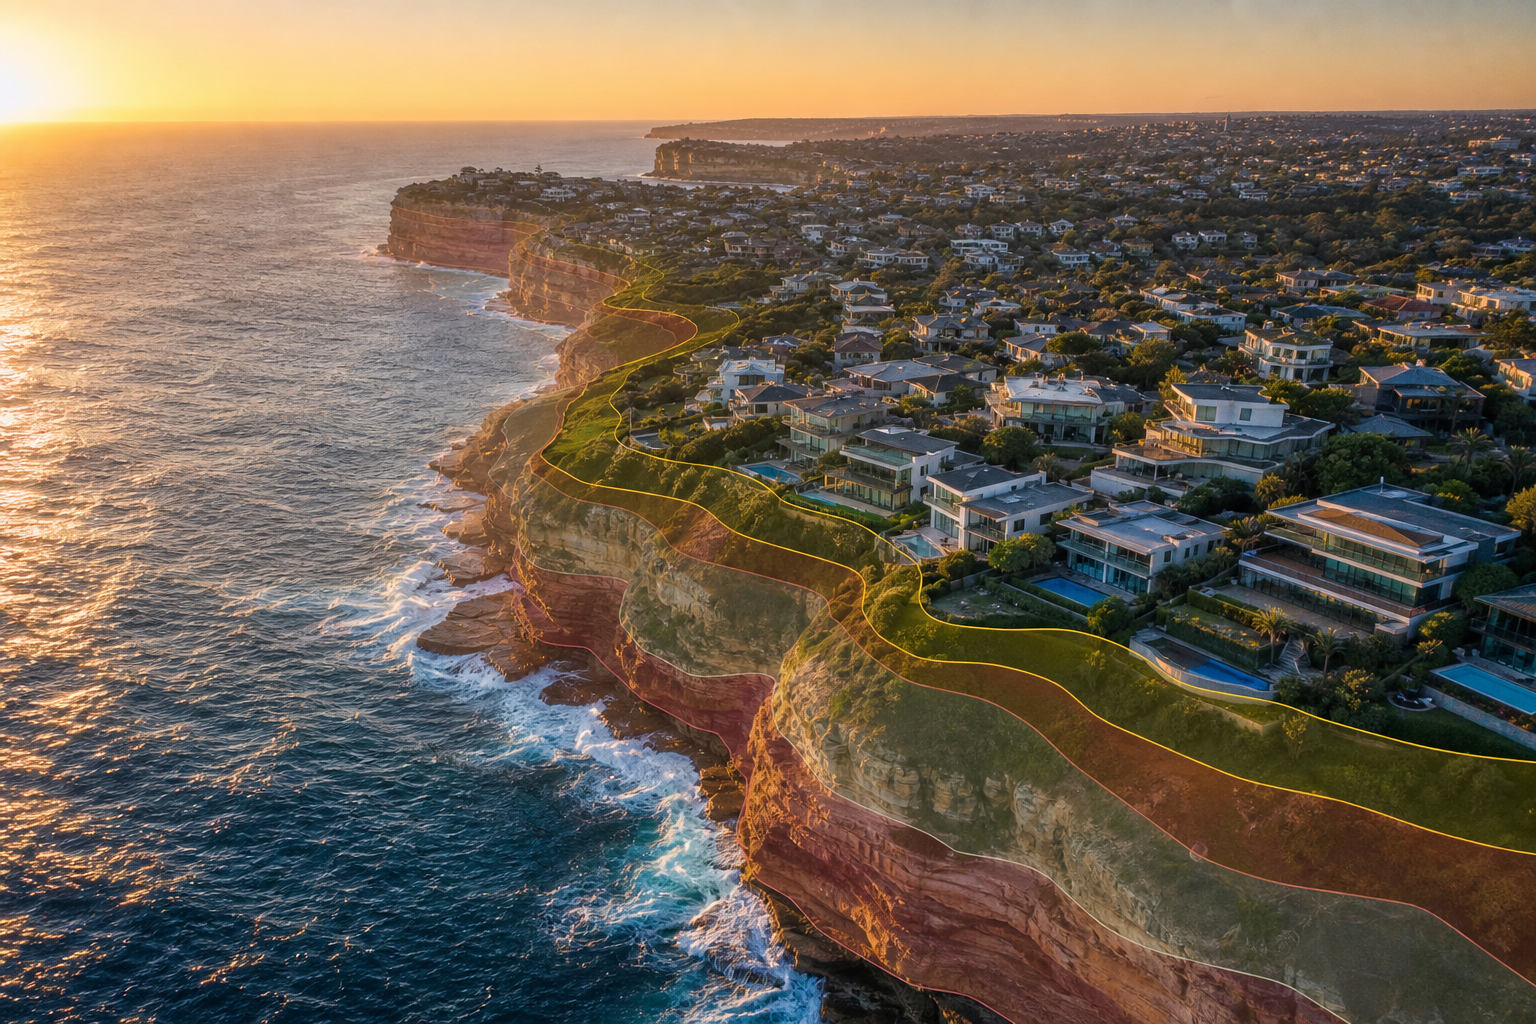
Read the full guide on tailoredloans.sydneyLenders will usually lend on coastal‑risk and landslip‑zone properties around Dover Heights and Vaucluse, but expect tighter valuations, lower LVRs and tougher insurance checks before approval. If the valuer or insurer doesn’t like the site’s stability or erosion risk, the practical impact is you need more cash and a bigger safety buffer to settle.
How banks read cliff, coastal and landslip risk
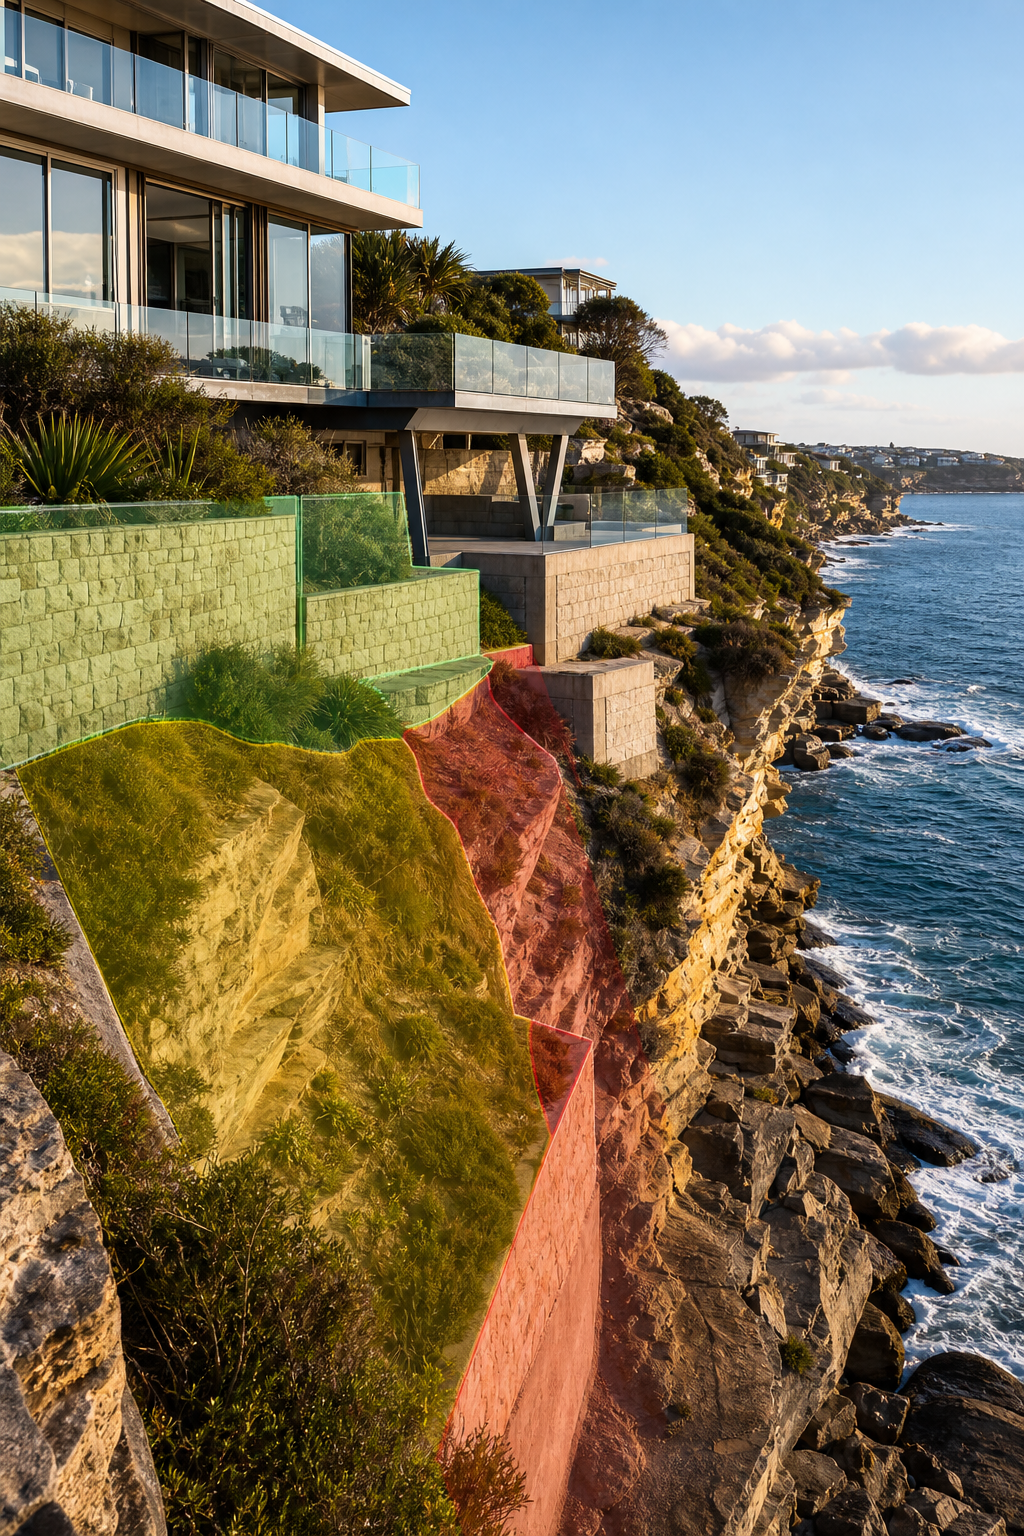
For a Dover Heights or Vaucluse clifftop, the bank’s questions are simple:
- Is the land stable for the life of the loan?
- Could erosion or landslip materially cut resale value?
- Is insurance available at a sensible cost?
If any answer is shaky, the lender still might lend, but will treat it like a higher‑risk postcode (similar to flood or bushfire areas – see /insights/coastal-flood-bushfire-risk-areas-bank-lending-guide).
Typical responses:
- Conservative valuation – valuer discounts for erosion set‑backs, building line or known slip history.
- Lower LVR – e.g. capped at 70–80% instead of 90–95%, often with no LMI waivers.
- Extra conditions – geotechnical report, structural engineer sign‑off, proof of insurability.
On a $4.0m clifftop home, a 10% valuation haircut (to $3.6m) at 80% LVR drops the max loan from $3.2m to $2.88m. You’d suddenly need an extra $320k cash.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.