
Article
Major banks vs second-tier vs non-banks: how a broker helps
Trying to choose between a major bank, second‑tier lender or non‑bank? This guide shows how a good broker compares them on policy, pricing and risk so you can move ahead with a clear, decision‑ready shortlist this week.
Key Takeaway
This article explains how mortgage brokers help Australians choose between major banks, second-tier lenders and non-banks by comparing policy, pricing and risk settings for each group. It notes that over 70% of new Australian home loans now come via brokers and that non-banks are a growing share of credit, according to RBA analysis. The key insight is that a broker can turn this complexity into a clear, decision-ready shortlist aligned to your income, risk tolerance and timeline.
This topic is covered in full on Tailored Loans Sydney
Trying to choose between a major bank, second‑tier lender or non‑bank? This guide shows how a good broker compares them on policy, pricing and risk so you can move ahead with a clear, decision‑ready shortlist this week.
Read the full guide on tailoredloans.sydneyFor most borrowers, the smartest lender isn’t automatically a big‑4, a second‑tier bank or a non‑bank. Each has different rules, risk appetite and pricing. A good broker’s real job is to translate your situation into a short, decision‑ready list across these groups, so you’re not guessing based on ads or headline rates.
Here’s how that works in practice this week.
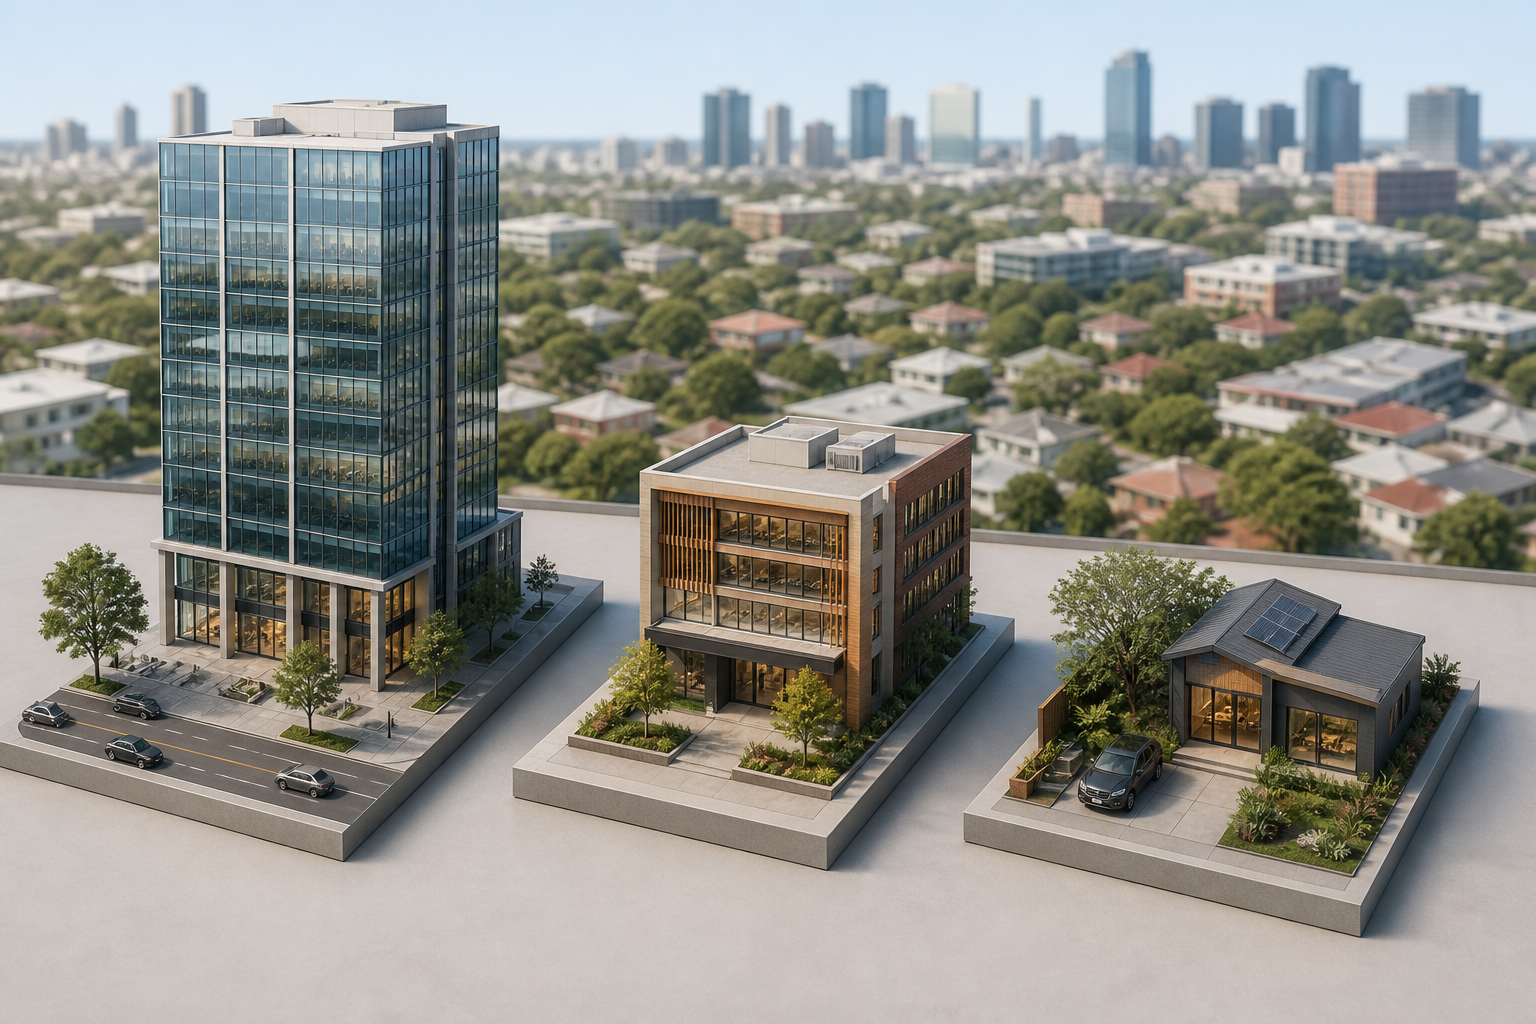
1. The three lender groups in plain English
Major banks (big‑4 and similar)
Think scale, strong brands and tight regulation.
Typical strengths:
- Strong digital banking and offsets
- Sharper pricing for very clean, simple deals
- Often more flexible with large, vanilla loans and private banking
Common limits:
- Stricter on living expenses (HEM plus extras), higher scrutiny of overtime/bonuses
- Tougher on self‑employed and complex income
- Slow to bend policy for edge‑case scenarios
Second‑tier / regional banks
Smaller ADIs with their own funding and deposits.
Typical strengths:
- Often slightly more flexible policy on income types or postcode
- Can be keener on price to win business from majors
- Sometimes better for first‑home buyers or smaller investors
Common limits:
- Fewer niche products or structures
- Slower policy change, occasionally clunkier systems
Non‑banks / alternative lenders
These don’t take deposits. They fund via capital markets and securitisation. The RBA has noted non‑banks’ growing share of credit post‑COVID as funding markets deepened.
Typical strengths:
- More flexible credit policy (e.g. recent self‑employment, short tax history, past credit blips)
- Wider range of alt‑doc options
- Willing to consider scenarios banks won’t touch
Common limits:
- Rates usually higher than majors for the same risk
- Fees can be chunky; exit costs need watching
- You rely more on contract terms than on a long brand history
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.