
Article
Off-the-plan vs established homes: a first-home finance decision
Off-the-plan and established homes are funded very differently. This guide shows first-home buyers the key finance risks, buffers and timelines so you can choose with eyes open this week.
Key Takeaway
For Australian first-home buyers, established homes are usually simpler and lower-risk to finance, while off-the-plan offers time to save but adds valuation and policy risk at settlement. Buyers should stress-test repayments at 3 percentage points above current interest rates and keep them under 30–35% of after-tax income, and plan for a 5–10% valuation shortfall on off-the-plan. The best choice is the one your income, buffers and timing can safely support this year.
This topic is covered in full on Tailored Loans Sydney
Off-the-plan and established homes are funded very differently. This guide shows first-home buyers the key finance risks, buffers and timelines so you can choose with eyes open this week.
Read the full guide on tailoredloans.sydneyChoosing between an off-the-plan apartment and an established home, the safer finance choice for most first‑home buyers is usually an established property, because there’s less valuation, policy and timing risk. Off-the-plan can still work well if you have strong buffers, stable income and treat the build period as a finance project, not just a decorating window.
For either path, a realistic safety test is to model repayments at current mortgage rates plus 3% and keep those stressed repayments under roughly 30–35% of your after‑tax income.
1. How finance actually works for each option
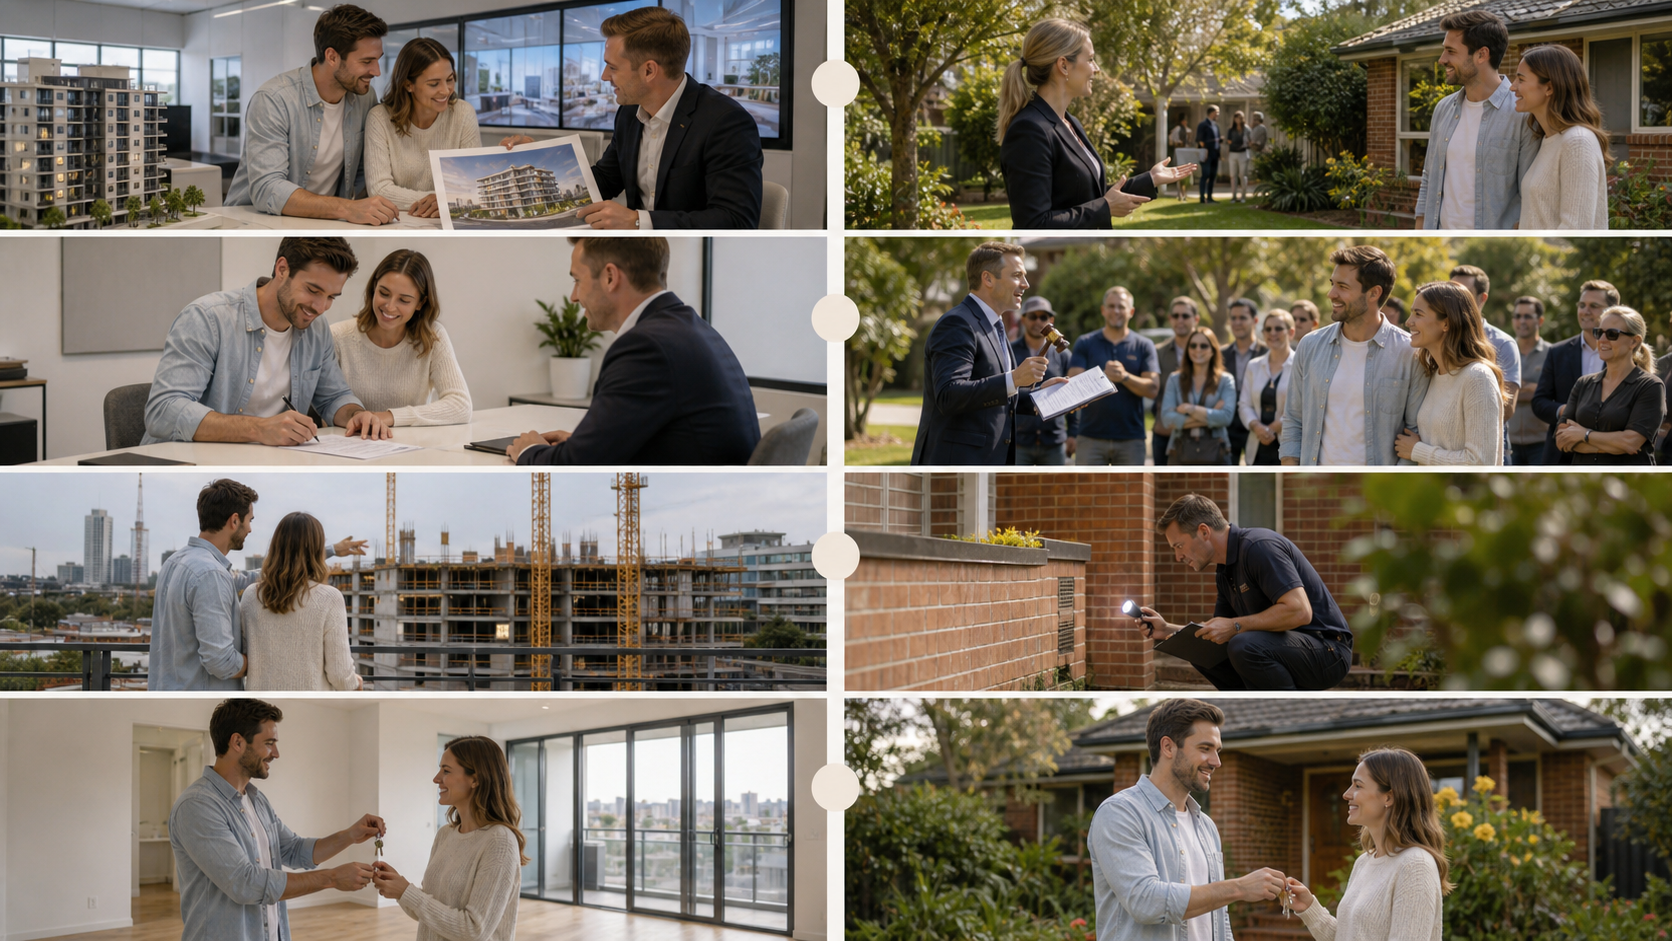
Off-the-plan finance in practice
With off-the-plan, you typically:
- Pay a 5–10% deposit now (cash or deposit bond).
- Wait 1–3 years for completion.
- Apply for your actual loan a few months before settlement.
Key point: your final loan is assessed against your future income, expenses, interest rates and valuation at settlement, not today. Lenders usually lend against the lower of contract price and valuation, so any shortfall immediately cuts your maximum loan.
Established home finance in practice
With an established home you:
- Get a pre-approval now.
- Buy at auction or private sale.
- Go unconditional and settle in 30–90 days.
There’s less time for your situation or bank policy to change. Valuation risk is lower because the property is already built and comparable sales are recent.
2. Finance pros and cons: off-the-plan vs established
At-a-glance comparison
| Factor | Off-the-plan first home | Established first home |
|---|---|---|
| Deposit timing | Smaller deposit now, more time to save | Need full deposit and costs up front |
| Valuation risk | Higher – final value may be 5–10% under contract | Lower – value based on current market |
| Interest rate / policy risk | High – 1–3 years of potential changes before settlement | Lower – changes only over 1–3 months |
| Build / settlement timeline | Long, moving target; risk of delays and sunset clauses | Clear 30–90 day timeline |
| Government grants/concessions | Can work well if timing lined up with rules at settlement | Simpler – schemes applied at or before contract |
| Inspection / defects | Buying from plans; defects found after completion | Can inspect now; known condition |
| Finance complexity | Higher – needs ongoing review and buffers | More straightforward |
If you’re time-poor or your income is borderline for serviceability, the simplicity of an established home often wins.
3. Risk areas that hit your loan approval
3.1 Valuation shortfalls (off-the-plan)
If you sign an off-the-plan contract at $800,000 and, at settlement, the bank valuation comes in at $740,000, most lenders will lend against $740,000.
- At 90% LVR, maximum loan ≈ $666,000.
- You still owe the developer $800,000.
- You now need ≈ $134,000 cash (plus costs), not the $80,000 you planned.
A practical safety rule for off-the-plan is to stress-test a 5–10% valuation drop and check you can still settle. Deposit bonds make this even more important, because you haven’t put real cash in yet.
For a deeper dive on managing this risk, see Avoid These First-Home Off-the-Plan Mistakes Lenders See Every Week.
3.2 Interest rate and policy changes
With a 2–3 year build, interest rates and bank rules can move a lot. APRA’s 3% serviceability buffer means even small rate rises bite into borrowing power.
- If today’s rate is 5.5%, banks may test you at 8.5%.
- If rates lift to 7%, assessment can hit 10%.
That’s why we keep coming back to the same rule: model repayments at 3% above current rates and keep them to 30–35% of your net income, regardless of grants or guarantees.
3.3 Income and life changes
Off-the-plan magnifies normal life risk:
- Job changes or reduced hours.
- Maternity/paternity leave.
- Moving from PAYG to self-employed.
Any of these between contract and settlement can reduce what the bank will lend. With an established home, there’s far less runway for life changes to derail you.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.