
Article
One Broker For Home, Investment And Business Loans Around Alexandria?
Written and reviewed by James Chee, CPA · Last reviewed
If you live or run a business around Alexandria, should one broker coordinate your home, investment and business loans? Here’s when it’s powerful, when it’s risky, and how to set it up safely.
Key Takeaway
Using one broker to coordinate home, investment and business loans around Alexandria usually works best when they centralise strategy but intentionally spread facilities across multiple lenders to reduce contagion risk. Cross‑collateralisation between home, investment and business properties should generally be the exception, as it can force property sales if a business downturn hits. The most actionable step this week is to map all loans, securities and guarantees on one page and have a single adviser stress‑test the structure.
Watch the short answer
Can I get a home or business loan with a 12‑month-old business?
If you’re weighing up one broker for home and business loans, this video shows how lenders view newer businesses when you apply.
Read the transcript
Started a wildly successful business 12 months ago? The bank still thinks you're a startup risk. The standard institutional rule is that you need 2 full years of ABN history to get a mortgage, but if your cash flow is booming right now, you shouldn't have to wait another 12 months to buy a house. At Local Knowledge Finance, we have access to specialist alt doc lenders who will approve your loan with just 6 to 12 months of ABN registration and clean bank statements. Your success shouldn't be penalised by arbitrary timelines. DM me the word 'BUSINESS' to bypass the 2-year rule.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Local Knowledge Finance
If you live or run a business around Alexandria, should one broker coordinate your home, investment and business loans? Here’s when it’s powerful, when it’s risky, and how to set it up safely.
Read the full guide on ding.financialMost people in Alexandria ask the wrong question. It’s not “Should I use one broker for everything?” It’s “Who is actually quarterbacking my whole financial structure so my home, investments and business don’t trip over each other?”
Using one broker for your home, investment and business loans around Alexandria can work brilliantly if they coordinate strategy across multiple lenders, keep your securities cleanly separated, and actively manage risk. It can be dangerous if they simply jam everything with one lender and cross‑collateralise the lot.
What I tell my clients is simple: the more moving parts you have (home, IPs, business, SMSF), the more you need one clear strategy, but not necessarily one lender.
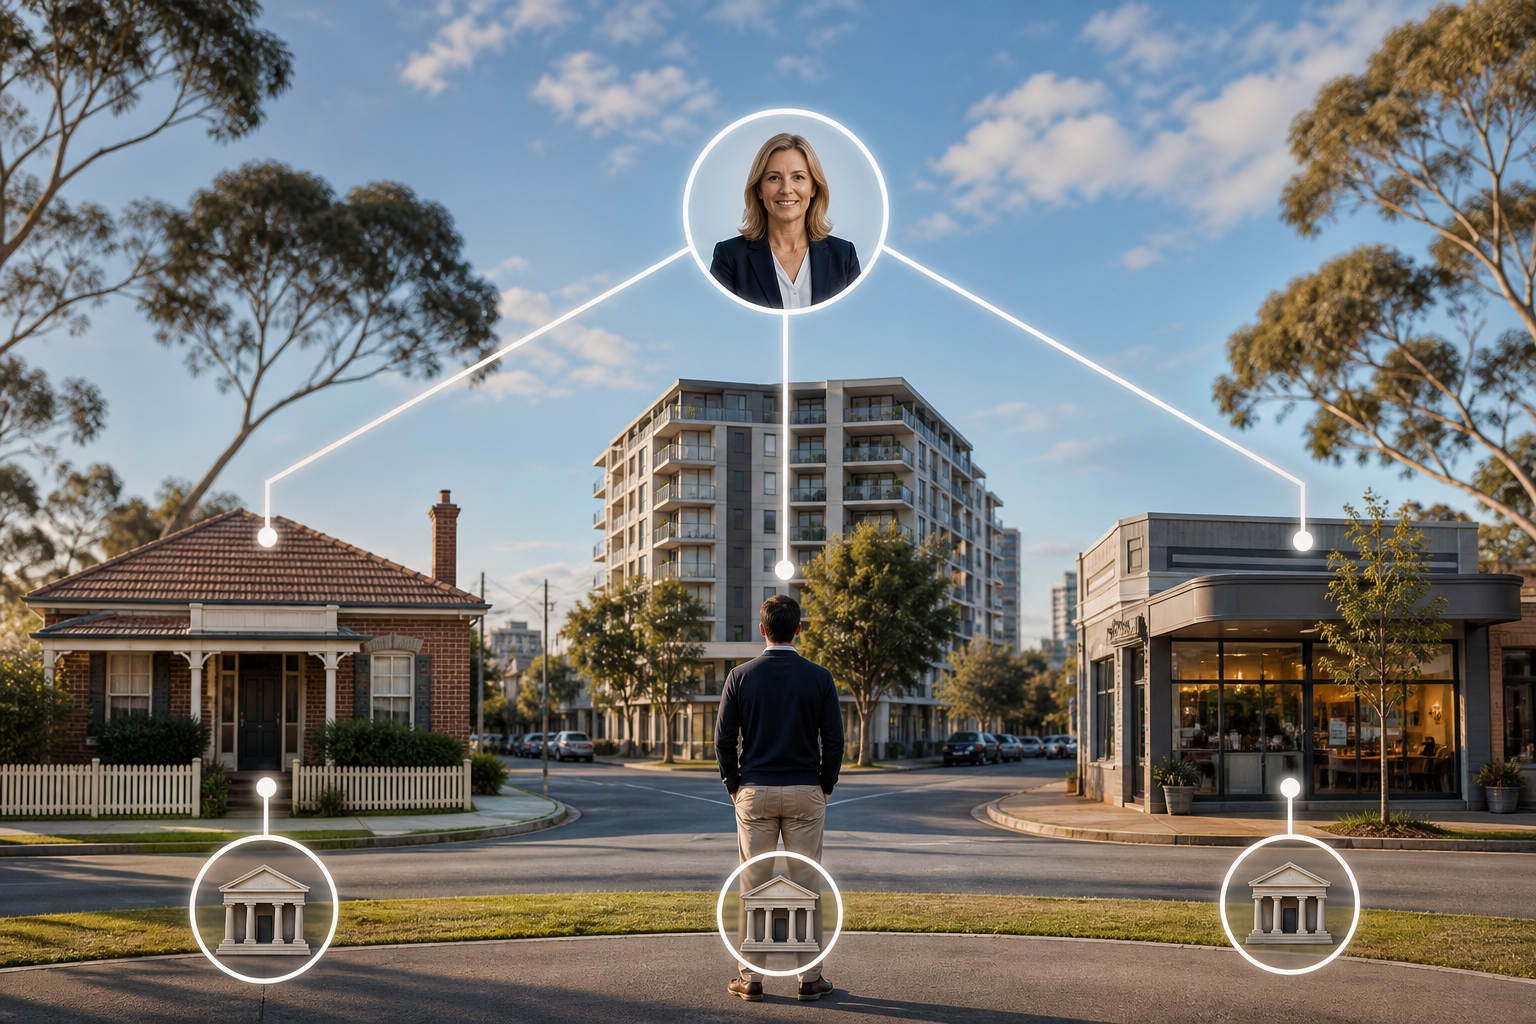
A real Alexandria scenario: everything “with one bank” backfires
A few months ago I met an Alexandria couple: she ran a creative agency on Maddox Street, he worked in tech. They had:
- An apartment in Alexandria
- An investment unit in Mascot
- A growing business that needed working capital
They were proud: “Everything is with one major bank; it’s so simple.” Then the agency hit a six‑month rough patch. The overdraft limit was reached, BAS was late, and suddenly the bank’s tone changed.
Only then did they realise:
- Both properties were cross‑collateralised to home, investment and business facilities.
- The bank could have forced sale of either property to fix the business shortfall.
- Refinancing away was painful because every loan and security was tied together.
The mistake I see most is confusing one point of contact with one giant, entangled loan structure.
One broker vs one lender: get this distinction right
Let’s define terms before deciding what to do this week.
One broker
One broker means a single adviser who:
- Maps and coordinates all your loans (home, investment, business, SMSF)
- Places facilities across multiple lenders where it makes sense
- Keeps a live view of how one loan change affects the rest
For complex borrowers around Green Square and Alexandria, the safest model is often one coordinating broker, multiple lenders, clear separation of securities (a pattern I’ve discussed in depth for neighbouring suburbs like Green Square and Dover Heights).
One lender
One lender means all (or most) debt sits with the same bank or non‑bank. That can be fine for simpler situations, but for self‑employed and investors it can:
- Concentrate power with one credit team
- Make it easier for them to offset losses in one area with equity in another
- Turn a business hiccup into a housing crisis
The sweet spot for many Alexandria clients
For a lot of my inner‑south clients, the sweet spot looks like:
- One strategic broker coordinating everything.
- Home and core investment loans with one or two conservative lenders.
- Business and equipment facilities with one or more different providers.
- Minimal cross‑collateralisation and a written exit plan where it’s unavoidable.
That way you get holistic advice without putting all your eggs in one basket.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 6 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.