
Article
How to Keep Your Business and Property Safe From Each Other’s Risks
Written and reviewed by James Chee, CPA · Last reviewed
A practical guide for Australian business owners to ring‑fence risk between their trading business, home and investment properties – with clear structures you can tighten this week.
Key Takeaway
Australian business owners can protect their business from property risks (and vice versa) by separating ownership structures, loans, guarantees and cash buffers, and by avoiding cross‑collateralisation of properties. Keeping business debt on 3–7 year facilities and not using home loan redraw as working capital reduces both tax complexity and exposure of the family home. A practical first step is to map all guarantees and securities, then refinance or restructure to isolate core assets over the next 6–12 months.
Watch the short answer
Can you still buy a property if your tax isn’t done yet?
While you’re working out how to separate business and property risk, this video covers what happens if your latest tax return isn’t done yet.
Read the transcript
think you can't buy a property this year because your accountant hasn't finalised your 2026 tax returns, think again. If you are a freelancer, a contractor or a growing business, that means months of lost opportunity. We use alternative documentation pathways that completely bypass the ATO delay. We assess your true borrowing capacity using the last 6 months of your business bank deposits, getting you approved while your competitors are still waiting on paperwork. Stop waiting on tax portals to dictate your property goals. message me 'ALTDOC' to fast track your FY27 approval.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Local Knowledge Finance
A practical guide for Australian business owners to ring‑fence risk between their trading business, home and investment properties – with clear structures you can tighten this week.
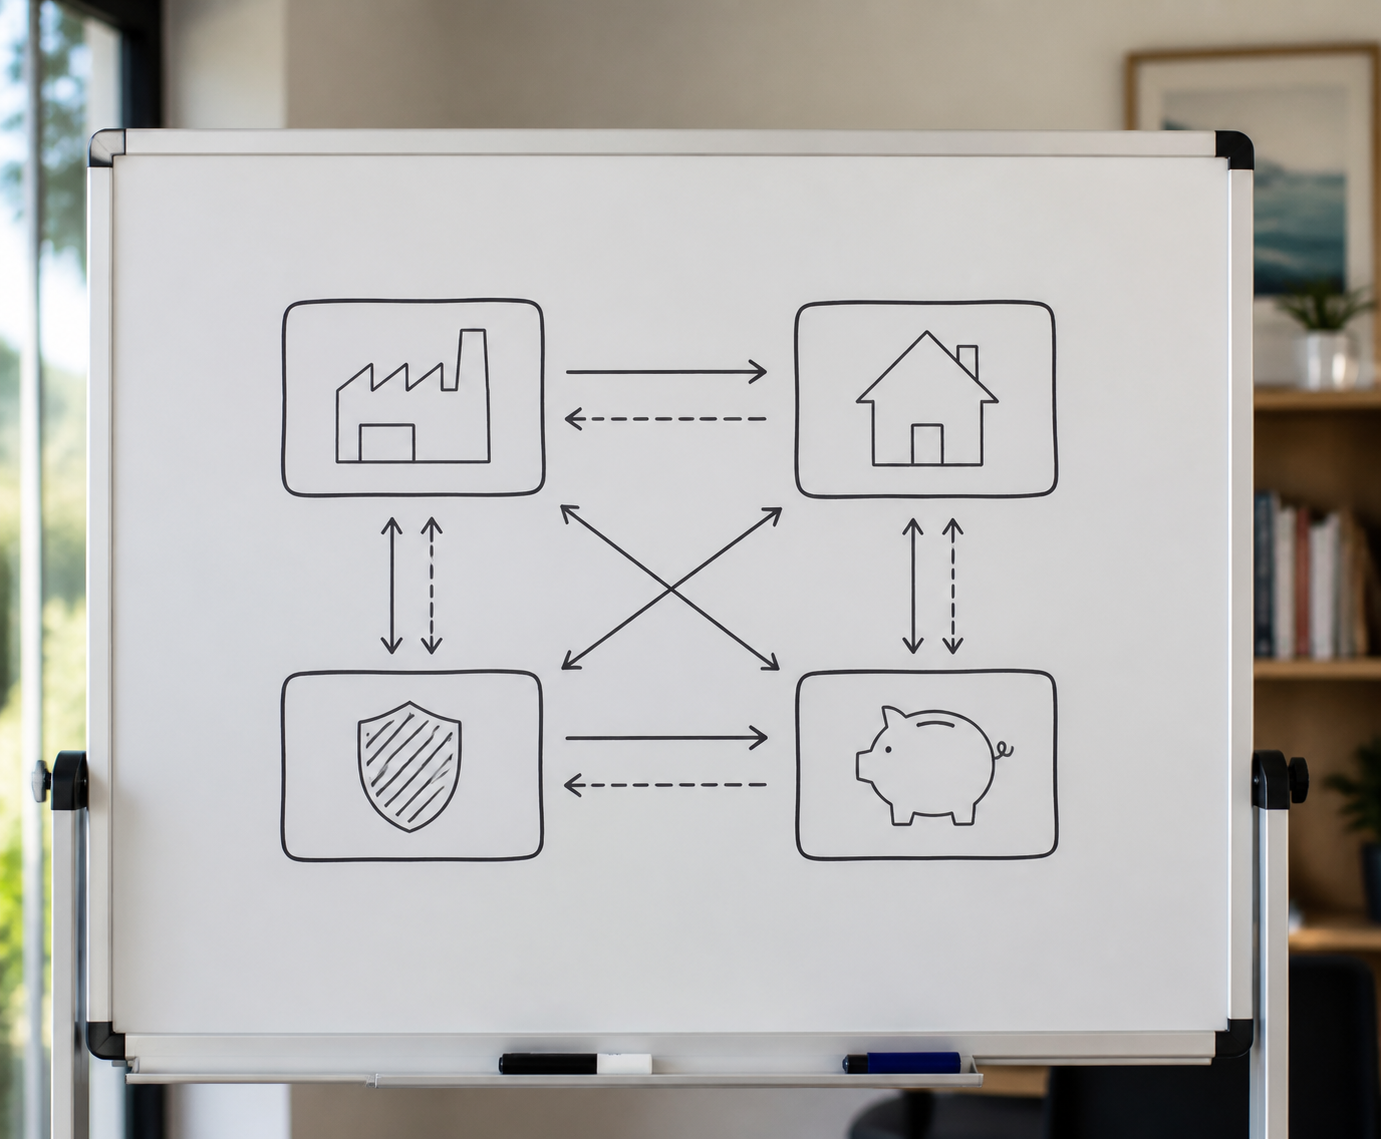
Read the full guide on ding.financialProtecting your business from property risks (and vice versa) means keeping your trading risks, your family home and your investments structurally separate: different entities, separate loans, limited guarantees and no unnecessary cross‑collateralisation. Done properly, a bad year in business shouldn’t automatically endanger your home, and a messy property project shouldn’t drown your business in cash calls.
In practice, that usually means: 1) ring‑fencing the operating business from core assets, 2) matching loan type and term to each asset, and 3) keeping business cash and property cash clearly separate.
1. Why risk separation matters now
With higher interest rates likely to stick around for a while (the RBA’s central case has underlying inflation staying above 3% until around 2027), both business and property cashflow are under more pressure than usual. That makes risk leakage between the two extra dangerous.
For small business owners, the big problems usually appear in three places:
- Cross‑collateralised loans linking business premises, home and investments.
- Personal guarantees that cut through companies and trusts.
- Blurred cashflow – using business working capital for property, or home equity as a recurring business overdraft.
If you fix those three, you’ve handled 80% of the risk.
Quick definition: ring‑fencing risk
Ring‑fencing means putting structural walls around risk. In this context, it’s:
- The business can fail without automatically forcing the sale of the family home.
- A property project can run over budget without instantly choking business cashflow.
You can’t remove all risk, but you can decide where it lands.
2. Structuring ownership: who should own what?
The starting point is simple: risky activity should sit in one entity; wealth should accumulate in another.
Common pattern for business owners
- Trading business in a company or trading trust.
- Family home in personal names (often safest from business creditors, but exposed to lenders if you guarantee everything).
- Investment properties in a separate trust or company, not the trading entity.
That doesn’t magically protect you – most banks still require personal guarantees, as we cover in Personal Guarantees, Wealthy Borrowers and the Asset‑Protection Illusion. But it gives you options when things go wrong.
Business premises and SMSFs
If your SMSF owns the business premises and leases it to your business, you’re wearing a different kind of risk: compliance risk.
- The lease must be commercial: proper rent, documented, paid on time.
- Sloppy records or under‑market rent can trigger ATO penalties or force unwinds.
If that’s you, sanity‑check your setup against Related‑party SMSF leases: keeping your business premises compliant this week.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Commercial & development
Smart Debtor Finance Around Progress Claims For Builders And Tradies
Commercial & development
Construction Cashflow 101: Progress Claims, Retentions And Funding Gaps
Self-employed lending
How to clean up overdrafts and director loans before a home loan
Self-employed lending
Simple Working Capital Setups For Sole Traders That Stay Tax‑Clean
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.