
Article
Smart ways to separate business, investment and personal cashflow
Written and reviewed by James Chee, CPA · Last reviewed
A practical guide for Alexandria homeowners and business owners to separate business, investment and personal cashflow using loan splits, offsets and clean rules so tax, lending and cashflow stay under control.
Key Takeaway
This guide explains how Alexandria homeowners who run a business or invest can separate business, investment and personal cashflow around their home loan. It covers using dedicated loan splits, multiple offset accounts, and separate bank accounts to keep deductible and non‑deductible debt traceable, noting that loan purpose, not security, determines tax deductibility. A worked example and comparison table show how clean structures can protect the family home, reduce audit risk, and support better borrowing power for future loans.
Watch the short answer
How does a default on your credit file affect home loan options?
While you’re sorting clean lines between business and personal cashflow, this video explains how a default on your credit file changes loan options.
Read the transcript
A default on your credit file is like a leak in a boat. Ignore it and your financial goals will sink. Many clients don't even realise they have a default until they apply for a loan and get hit with a rejection. It could be an old utility bill or a disputed commercial invoice. Before you apply for major capital, you need a forensic review of your credit file. We identify the impairments, build the mitigant story, and route you to the specialised lenders who accept rehabilitated credit. Don't let a surprise default ruin your plans. DM me the word 'FILE' for a complete credit health check.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
A practical guide for Alexandria homeowners and business owners to separate business, investment and personal cashflow using loan splits, offsets and clean rules so tax, lending and cashflow stay under control.
Read the full guide on tailoredloans.sydneyIf you run a business or hold investments in Alexandria, the safest way to manage your mortgage is to separate business, investment and personal cashflow with clear loan splits, separate offsets and dedicated bank accounts. That means each dollar of debt has one purpose, every repayment is traceable, and you’re not guessing what’s deductible when the ATO or a lender asks you to prove it.
Here’s how to get that structure in place this week.
1. Why separating cashflow around your Alexandria mortgage matters
Clean lines protect your home, tax position and borrowing power
For business owners and investors, three things are on the line:
- Tax deductibility – The ATO cares about purpose, not which property secures the loan. Mixed‑use loans are harder to trace and audit.
- Risk to your home – If business and personal are blurred, downturns can drag the family home into the mess.
- Future borrowing power – Lenders treat personally guaranteed business debts as personal commitments, so messy structures can sink your next approval.
With higher rates and more households in mortgage stress (Roy Morgan estimates over 28% were ‘at risk’ in early 2026), Alexandria owners don’t have room for sloppy setups.
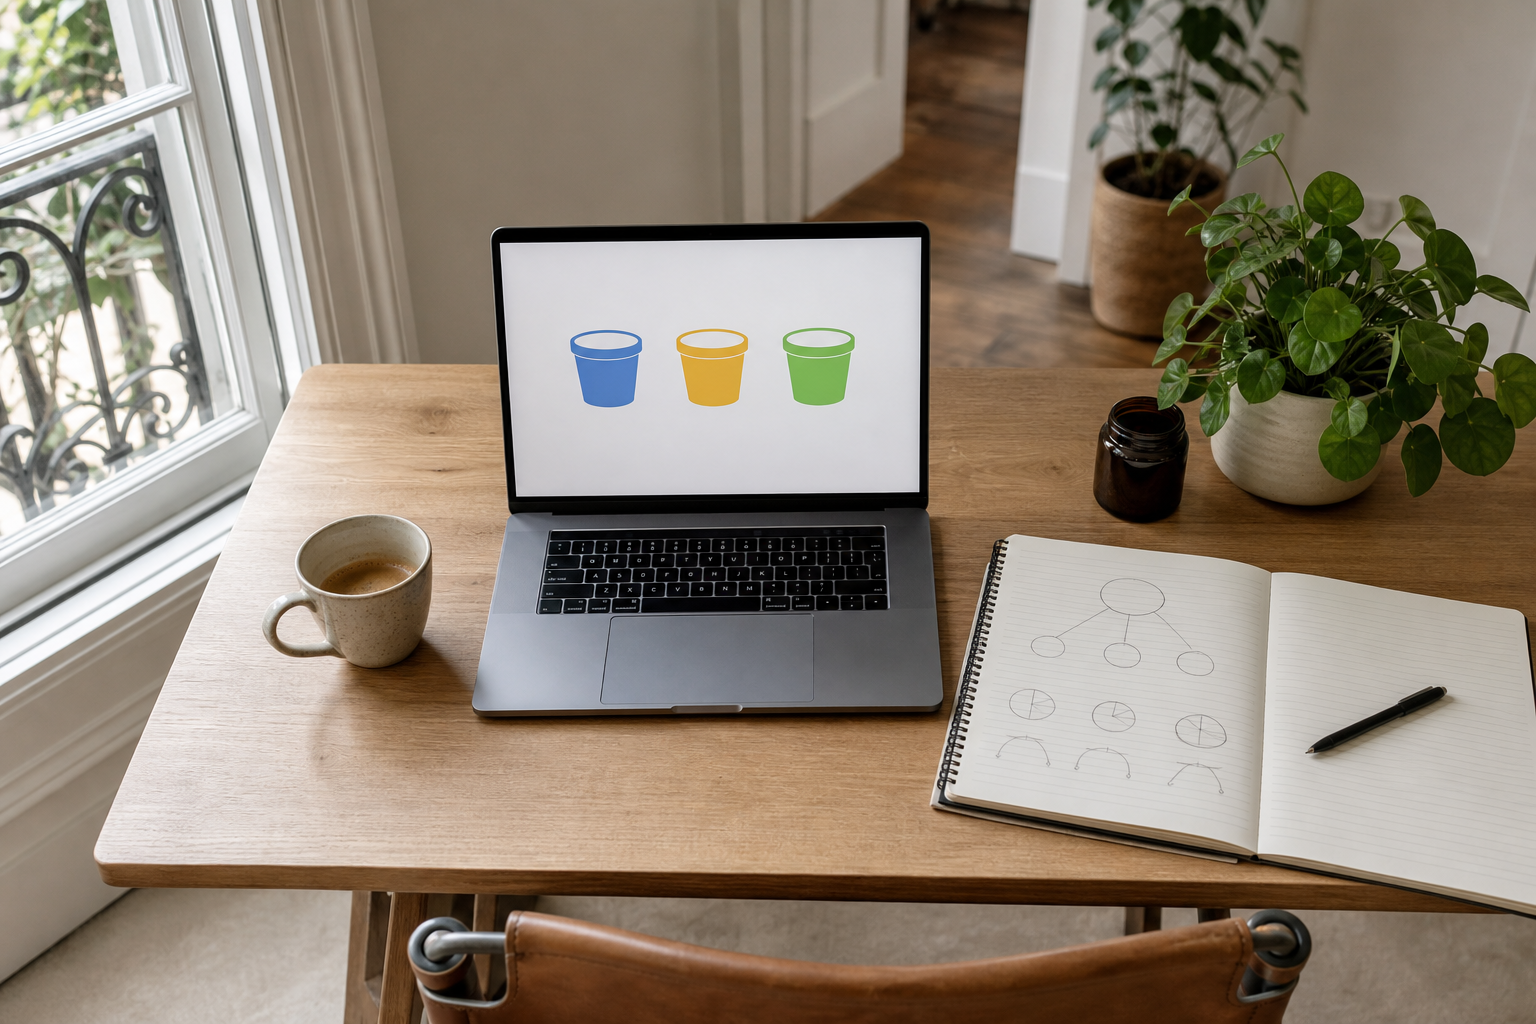
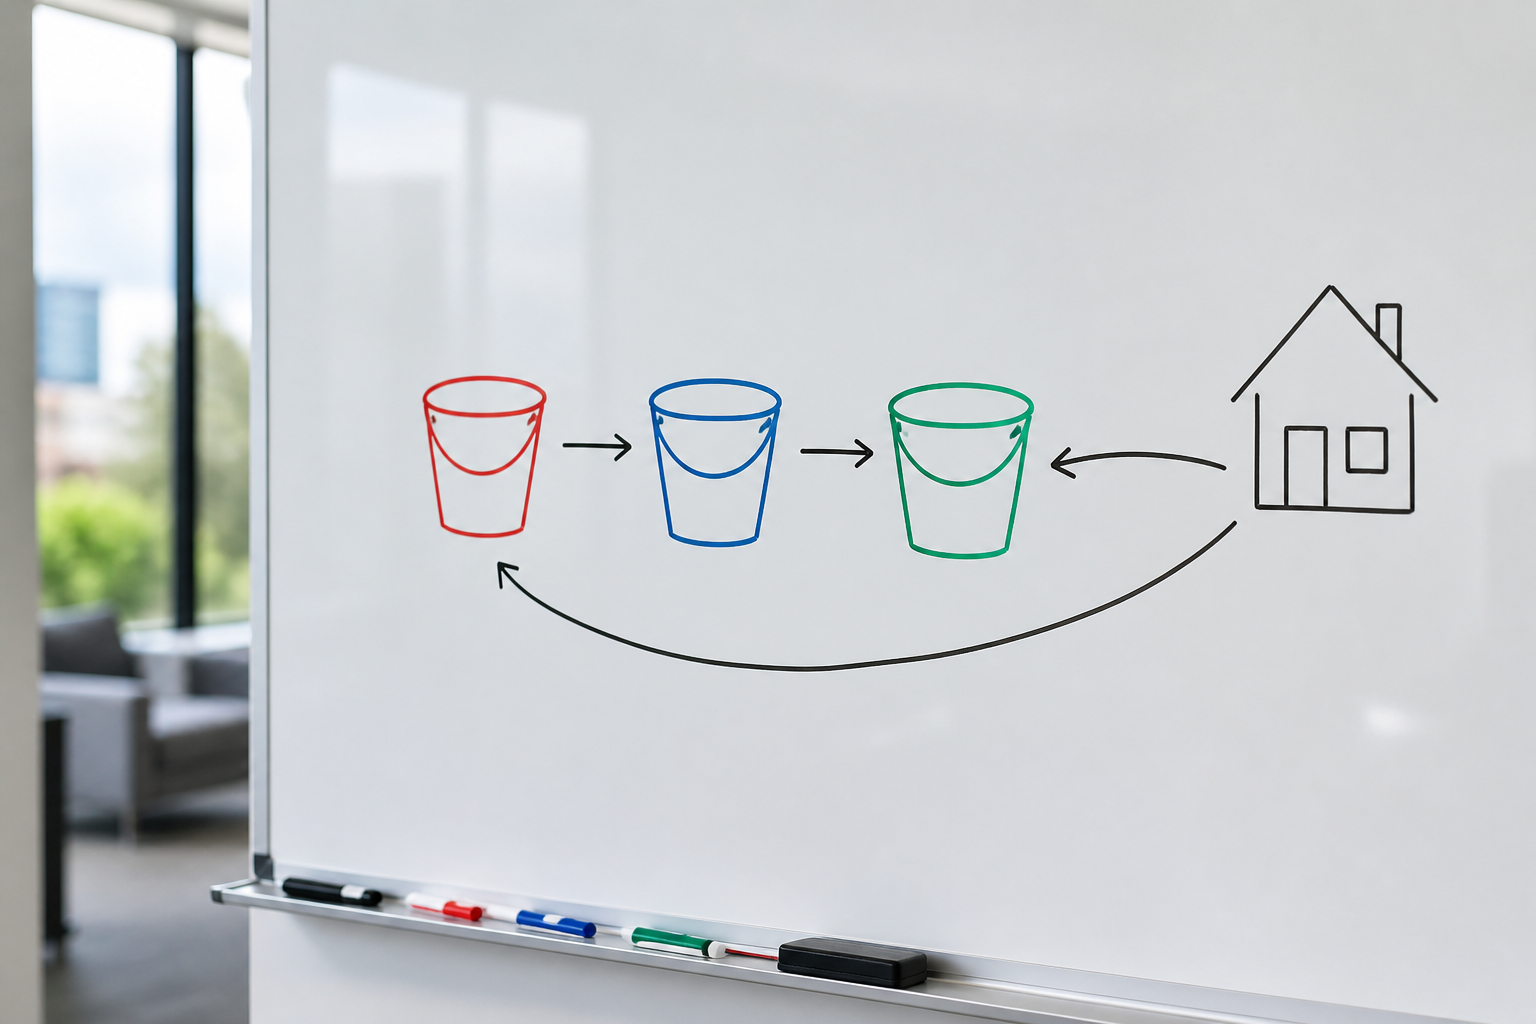
The three “buckets” you must keep separate
Think in buckets, not accounts:
- Bucket 1 – Personal / home: non‑deductible home loan, family expenses, buffers.
- Bucket 2 – Business: working capital, GST / BAS, payroll, business equipment loans.
- Bucket 3 – Investment: investment property loans, share portfolios, debt recycling.
Your goal is a structure where money only moves between buckets when it’s clearly documented and makes sense from both tax and lending perspectives.
2. Structures that keep business, investment and personal money apart
Use loan splits to track deductible and non‑deductible debt
Instead of one big Alexandria mortgage, you can usually split it into separate sub‑loans:
- Split A – Home (non‑deductible)
- Split B – Investment (e.g. deposit for an investment property or shares)
- Split C – Business (e.g. fit‑out or working capital injection)
Each split then has its own repayments and its own story.
For more on how splits work day‑to‑day, see /insights/using-multiple-splits-offset-accounts-large-home-loan.
Use multiple offsets – but keep them “clean”
A simple pattern for business owners:
- Offset 1 – Personal: salary/drawings in, household bills out, emergency buffer.
- Offset 2 – Business: owner drawings out to Offset 1, business expenses only.
- Offset 3 – Investment (optional): rents in, property expenses and interest out.
The key rule: don’t use redraw for living expenses or business cashflow – it contaminates the loan purpose and can break deductibility. Use offsets instead.
Comparison: one mixed loan vs split structure
| Setup | Pros | Cons / Risks |
|---|---|---|
| One big mixed home loan | Simple on paper, one repayment | Messy ATO tracing, hard to refinance just one purpose, higher audit risk |
| Separate splits for each purpose | Clean tax story, easy to target debts | Needs upfront planning, a bit more admin |
The second option is usually safer for Alexandria business owners because it keeps business and investment risk away from the family home as much as possible.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.