Article
How to Check If You Can Really Service Multiple Off‑the‑Plan Loans
Written and reviewed by James Chee, CPA · Last reviewed
Buying more than one off‑the‑plan apartment sounds clever, but can you *actually* service the loans at settlement? This guide shows a fast, decision‑grade way to test your borrowing power across multiple future properties using conservative, lender‑style assumptions – so you know what you can safely sign this week.
Key Takeaway
Borrowers can service multiple off‑the‑plan loans only if all future repayments remain affordable when stress‑tested at interest rates around 3 percentage points above current levels, consistent with APRA buffers. A practical ceiling is keeping total home and investment repayments under 30–35% of after‑tax income, assuming conservative rent and no negative gearing uplift. The key actionable step is to model all properties together under worst‑case assumptions before signing more than one contract.
Watch the short answer
Home loans when you earn through digital platforms or rolling contracts
If your income comes from gigs, contracts or platforms, this video unpacks how lenders really look at that when testing serviceability.
Read the transcript
If you earn your living through digital platforms or rolling contracts, standard banks will treat you like you're unemployed. Retail credit systems are built for the 1990s definition of a 9-to-5 payslip. When they see fluctuating invoices, they panic. At Local Knowledge Finance, we specialise in the modern economy. We utilise lenders who understand digital revenue, creator funds, and specialised contracting. We smooth out your income using advanced alt-doc policies to present a rock-solid case to a human underwriter. Your modern income needs a modern broker. DM me 'CREATOR' to unlock your actual buying power.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Buying more than one off‑the‑plan apartment sounds clever, but can you *actually* service the loans at settlement? This guide shows a fast, decision‑grade way to test your borrowing power across multiple future properties using conservative, lender‑style assumptions – so you know what you can safely sign this week.
Read the full guide on tailoredloans.sydneyYou can sometimes service multiple off‑the‑plan loans, but only if your income, debts and buffers still work when all future properties are tested together at higher rates and lower rent. In practice, that means modelling each loan at interest rates 3% above today, using conservative rental income, and keeping total repayments under roughly 30–35% of your after‑tax income – even if the bank’s calculator says you can borrow more.
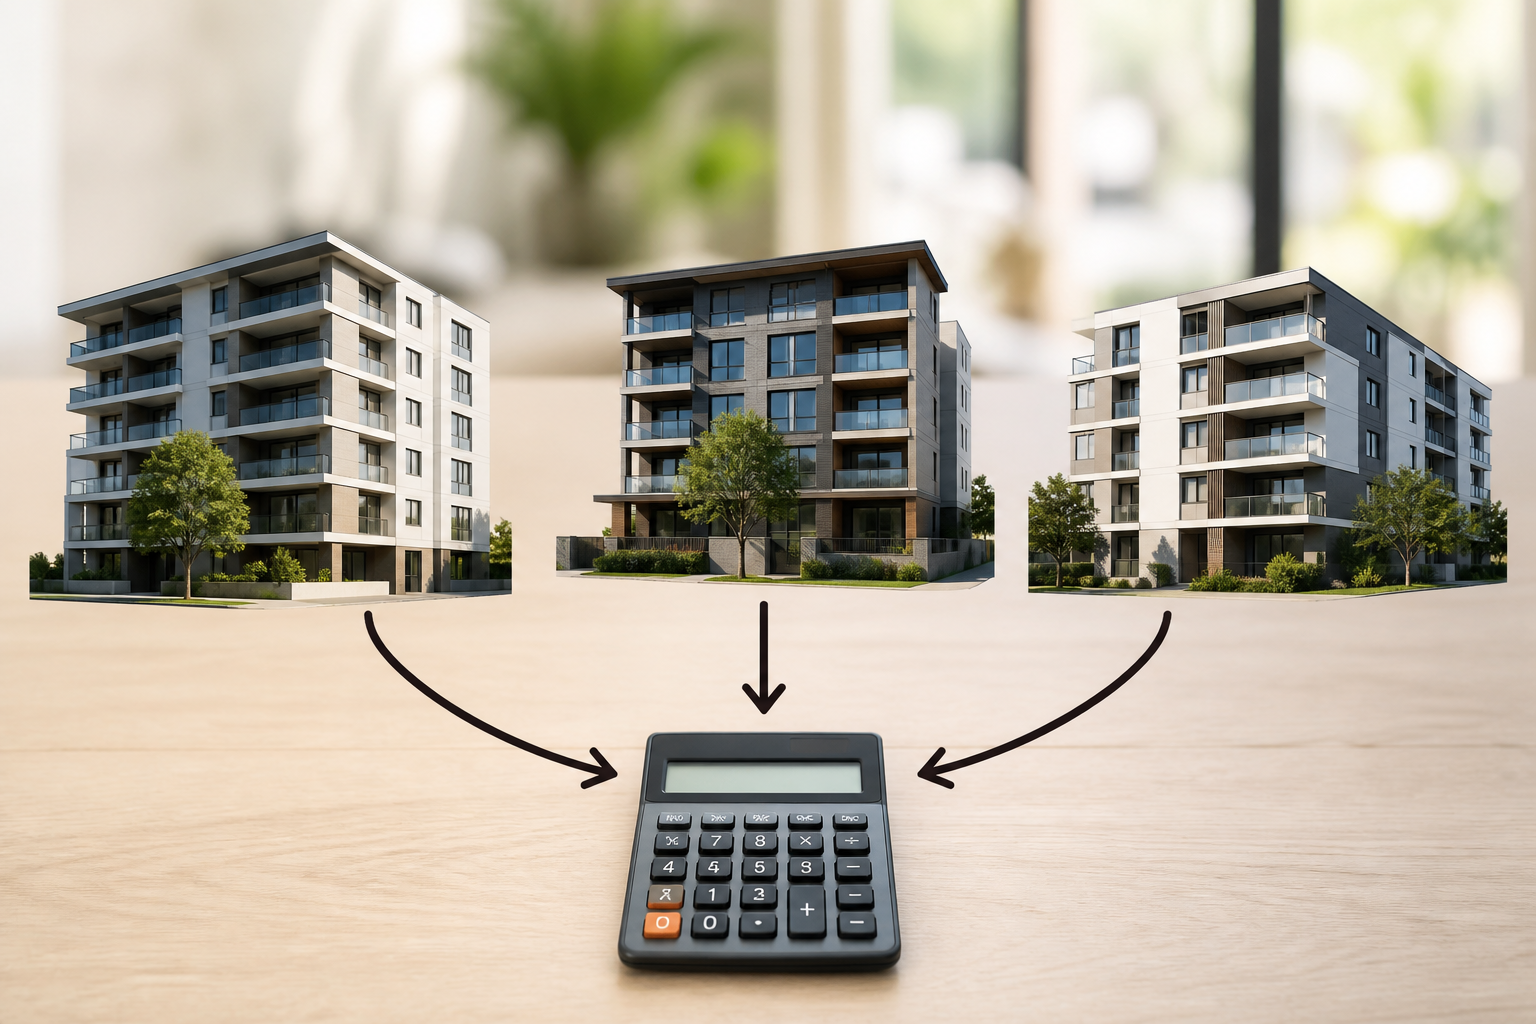
Step 1: Understand how banks stress‑test multiple properties
When you apply for your second or third off‑the‑plan loan, lenders don’t look at each property in isolation. They assess your whole portfolio at once.
Key points:
- APRA buffer: Banks generally test repayments at current rates + 3% on principal‑and‑interest (P&I), even for interest‑only (IO) loans (APRA guidance).
- Conservative rent: Lenders typically shade rent to 70–80% usable to allow for costs and vacancy.
- Living expenses: They plug in at least HEM (Household Expenditure Measure), and often more if your disclosed spending is higher.
- Other debts: Credit cards (even unused limits), car loans, HELP/HECS and business loans all hit your borrowing power.
For responsible investing, mirror that: keep your total P&I repayments under about 30–35% of after‑tax income when modelled at current rates plus 3% (a consistent safety rule across our Eastern Suburbs case studies).
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Business finance
Choosing Interest‑Only or P&I on Strata Loans Without Killing Cashflow
Commercial & development
Commercial strata finance rules: how they differ from residential
Property investors
Refinancing An Investment Property When Your Strata Has A Loan
Property investors
Smart tax decisions on strata loans and levies for owners and investors
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.