Article
Should Your SMSF Own Your Business Premises or Not?
Using your SMSF to buy your business premises can be powerful, but it’s high‑stakes and not right for every owner. This guide shows when it makes sense, when it doesn’t, and what to check this week before you move a cent.
TL;DR
Using your SMSF to buy your business premises can work brilliantly for stable, profitable businesses with solid super balances and long-term plans to stay in the property. It’s risky if you’re early-stage, light on super, or likely to move. This guide gives you a decision checklist you can work through in a week.
Watch the short answer
Why active ATO debt can hurt your business finance options
While you weigh up using your SMSF to own your premises, this video explains how unpaid ATO debt can limit your business finance options.
Read the transcript
An active ATO debt is a massive red flag that triggers an instant computer rejection at every major bank. The Tax Office is the most expensive lender you can have. If you have equity in your property, we can restructure that debt. We use specialist capital channels to clear the ATO entirely, moving that high-stress liability into a single clean facility. Give your business room to breathe. DM me 'CLEAR' to start.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Local Knowledge Finance
Using your SMSF to buy your business premises can be powerful, but it’s high‑stakes and not right for every owner. This guide shows when it makes sense, when it doesn’t, and what to check this week before you move a cent.
Read the full guide on ding.financialShould Your SMSF Own Your Business Premises or Not?
Using your SMSF to buy your business premises can be a smart move, but only if your business is solid, your super balance is strong, and you’re comfortable locking up retirement money in one big asset. For a lot of owners, the risks and complexity outweigh the benefits.
Using your SMSF to buy your business premises can be smart if you have a strong, stable business, plenty of super already saved, and you’re comfortable tying up a big chunk of your retirement money in one property. The SMSF owns the building and your business pays market rent to the fund. It suits profitable, established businesses more than early‑stage or highly volatile ones.
How an SMSF owning your premises actually works
At a high level, you have two hats:
- Your SMSF owns the commercial property.
- Your trading business pays market rent to the SMSF under a normal commercial lease.
If borrowing is involved, the SMSF uses a limited recourse borrowing arrangement (LRBA). The lender’s security is mostly limited to the property itself, which is why SMSF loan rates are usually higher and LVRs lower than regular home loans.
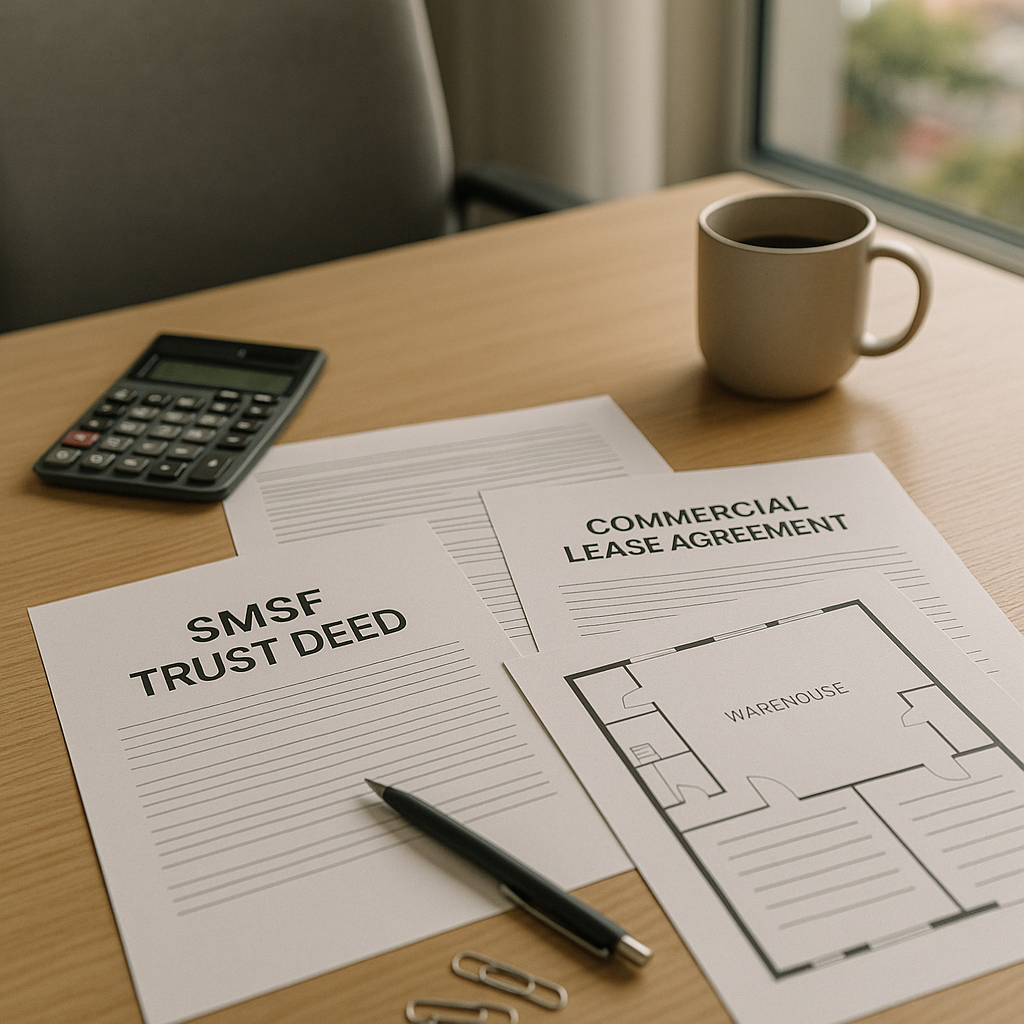
A few hard rules you can’t bend:
- It must be business real property – genuinely used wholly and exclusively in a business.
- The lease must be arm’s length – market rent, proper lease, on-time payments.
- No one can live in it – this is commercial only.
Quick numbers example
Say your SMSF wants to buy a $1.2m warehouse used by your trading company.
- SMSF cash: $500k
- SMSF loan: $700k (58% LVR) at an indicative 7.0% p.a., 20-year P&I
Approximate annual loan repayment: around $65k–$70k.
If market rent is $90k p.a. plus outgoings:
- Rent covers the loan and some property costs.
- Super contributions and any surplus rent build cash and eventually help pay down the loan.
Looks neat on paper – but only if the rent keeps flowing and your fund isn’t starved of diversification or liquidity.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 3 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.