
Article
How To Safely Stagger Contracts And Settlements On Multiple Off‑the‑Plan Apartments
A practical guide to timing contracts and settlements when buying several off‑the‑plan apartments, so you control cashflow, borrowing capacity and risk instead of being surprised by them.
Key Takeaway
Staggering contracts and settlements when buying several off‑the‑plan apartments means deliberately spacing your contract dates, expected completion windows, valuations and loan approvals so cashflow and borrowing capacity aren’t hit at once. Using a 2–3% interest rate buffer and 3–6 months’ expenses as a cash buffer, investors can reduce settlement risk and sequencing risk. The key step is mapping each project’s timeline and only committing to new contracts once you can survive worst‑case overlapping settlements on stressed numbers.
This topic is covered in full on Tailored Loans Sydney
A practical guide to timing contracts and settlements when buying several off‑the‑plan apartments, so you control cashflow, borrowing capacity and risk instead of being surprised by them.
Read the full guide on tailoredloans.sydneyIf you’re buying several off‑the‑plan apartments, you should stagger contracts and settlements so only one major cash event lands in any 3–6 month window and you can still hold a 3–6 month cash buffer (6–12 months if self‑employed). That means spacing contract exchange dates, sunset dates, expected completion and loan approvals so your borrowing capacity, valuations and cash are never tested by two or three projects at once.
This guide shows how to design that timing, check it against your numbers and what to watch before you sign the second contract.
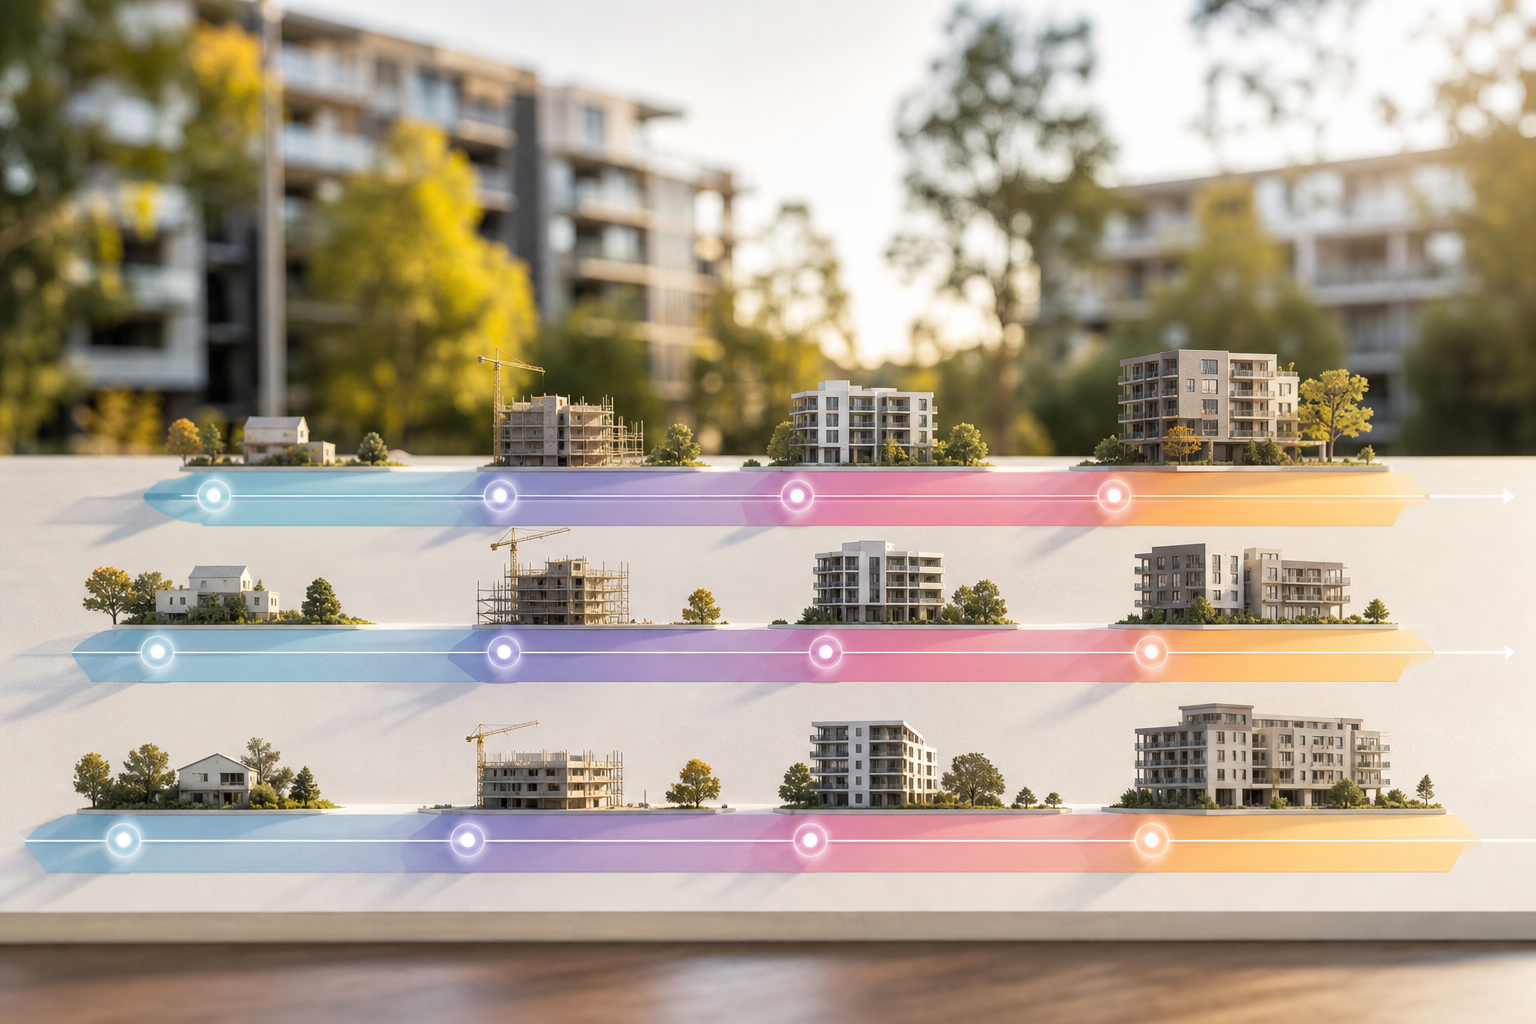
1. What “staggering” really means for multi‑off‑the‑plan buyers
Staggering contracts and settlements is not just “different dates on paper”. It’s a risk strategy where you:
- Avoid overlapping settlements where possible.
- Limit how many deposits are tied up at once.
- Time valuations and loan approvals to protect borrowing capacity.
- Keep buffers intact even under rate and rent shocks.
Think of each project as its own timeline: contract exchange → construction → valuation → loan approval → settlement → leasing. Staggering means you never let those peak‑risk stages bunch up.
Key timing concepts
- Contract date – when you pay deposit and become legally committed.
- Sunset date – latest date the developer must complete (or contract may be terminated).
- Practical completion window – the real‑world period construction is likely to finish.
- Settlement window – the 2–6 week period after completion when you must be ready with finance.
If you line up three projects with similar windows, you’ve accidentally built a “settlement cluster”.
2. Mapping timelines and spotting dangerous overlaps
Start by building a simple timeline for each project in a spreadsheet or on paper.
Step 1: Put dates to each phase
For each apartment, list:
- Contract exchange month and year.
- Stated completion and sunset dates.
- Your realistic completion estimate (often 3–9 months later than glossy brochures).
- When you plan to order the valuation.
- When you’ll submit the loan application.
For valuation timing detail, see When To Order Your Off‑the‑Plan Valuation (And When Not To).
Step 2: Put it all on one page
Create a row for each project and map the risky phases:
- Deposit at contract.
- Valuation + loan approval.
- Settlement.
Then highlight any 3–6 month period where two or more projects hit those phases at once. That’s where you’re most exposed if:
- Rates jump 2–3%.
- One valuation comes in short.
- A lender changes policy.
Quick comparison: tightly vs well‑staggered
| Scenario | A: Clustered risk (bad) | B: Staggered risk (better) |
|---|---|---|
| No. of apartments | 3 | 3 |
| Contract exchanges | All within 2 months | Spread over 12 months |
| Expected settlements | All within 3 months | 6–9 months apart |
| Cash buffer at first settlement | 3 months | 6 months |
| Overlap of loan approvals | Yes, all within 6 weeks | Each ~4–5 months apart |
| Worst‑case: two valuations short | High chance of same‑time stress | More time to repair between events |
| Refinancing / non‑bank options needed | Likely, under time pressure | Optional, with breathing room |
Your goal is to look like Scenario B, even if it means passing on a “great deal” that lands in the wrong window.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.