
Article
When Self‑Employed Mascot Buyers Should Lodge Tax Returns Before a Home Loan
A decision‑grade guide for self‑employed Mascot buyers on when to lodge tax returns, how low tax strategies affect borrowing power, and how ATO debts impact home loan approval.
Key Takeaway
Self-employed Mascot home buyers should generally lodge recent tax returns before applying for a full-doc home loan, because lenders rely heavily on the last two lodged years and often use the lower or averaged income figure for servicing. Aggressive tax minimisation can cut borrowing power by hundreds of thousands of dollars, often outweighing the tax saved. A coordinated plan between accountant and broker lets borrowers time lodgements, clear or structure ATO debts, and choose between full-doc and alt-doc options to maximise both approval odds and long-term safety.
This topic is covered in full on Tailored Loans Sydney
A decision‑grade guide for self‑employed Mascot buyers on when to lodge tax returns, how low tax strategies affect borrowing power, and how ATO debts impact home loan approval.
Read the full guide on tailoredloans.sydneyYou can’t separate tax and borrowing power when you’re self‑employed in Mascot.
For a lender, your lodged tax returns are effectively your payslips. The timing of when you lodge – and how much income you actually declare – will drive how much you can borrow, whether your application sails through, and how the bank views any ATO debt.
This guide shows you, in practical steps, how to decide when to lodge tax returns if you’re self‑employed and planning a Mascot home purchase or refinance.
Fast answer: lodge now or wait?
If you need a standard full‑doc home loan, most lenders will want:
- Your two most recent lodged tax years, and
- BAS or management reports if the latest year is very recent or volatile.
In simple terms:
- If your most recently finished year is stronger, and you can live with the tax bill, lodge early so lenders can use that higher income.
- If the year you’ve just finished is weak (or full of one‑offs) but the previous two years are already lodged and strong, you may delay lodging and apply using the existing returns – within ATO deadlines and with proper advice.
- If you have or expect an ATO debt, you usually need a formal payment plan in place and up to date before most banks will touch your file.
The smarter move is almost always to get your accountant and a mortgage broker talking to each other before you lodge. We’ll unpack how to do that this week, without derailing your tax plan.
1. How banks read self‑employed income in Mascot
1.1 The basics: what lenders want to see
For self‑employed Mascot borrowers (sole traders, company directors, partners, contractors), most mainstream banks will ask for:
- Two years of personal tax returns and Notices of Assessment (NOAs)
- Two years of business financial statements (P&L and balance sheet)
- Business Activity Statements (BAS) where relevant
- Sometimes, year‑to‑date (YTD) figures if the last year has just ended
Key principle: they trust what’s been lodged with the ATO. If it’s not lodged, many lenders pretend it doesn’t exist.
1.2 How they actually calculate usable income
Common approaches:
- Average of last two years’ taxable income
- Lower of the two years if income has dropped materially (e.g. >20%)
- Add‑backs for:
- Non‑cash expenses (like depreciation)
- Once‑off costs (e.g. legal fees for a restructure)
- Some interest costs that will disappear after refinance
Example – basic Mascot scenario:
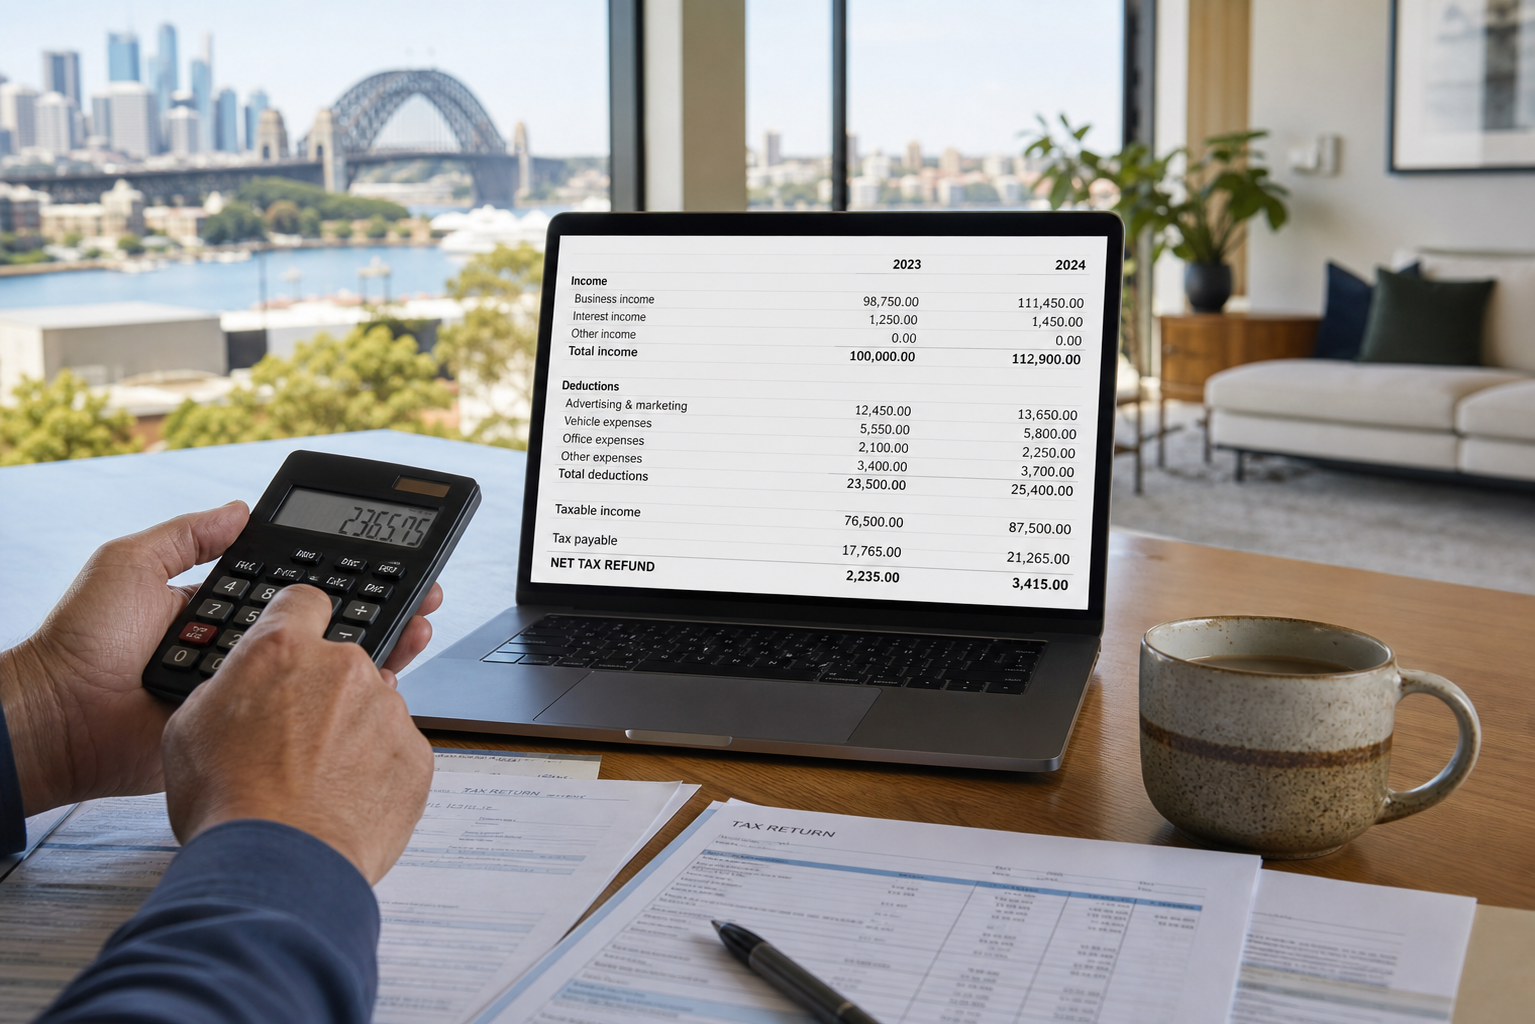
- FY24 taxable income: $110,000
- FY23 taxable income: $80,000
- Most lenders might use: ($110k + $80k) / 2 = $95,000 for servicing.
- If they see a 35% jump and don’t like volatility, they may use $80,000 only.
You can see why we need to know each year’s numbers before you lodge – even a well‑meant tax strategy can cost you $100k+ in borrowing power.
For more on how brokers reshape self‑employed income for banks, see Self‑Employed? How a Skilled Broker Tilts Home Loans In Your Favour.
2. The central trade‑off: low tax vs borrowing power in Mascot
2.1 Why “minimise everything” can backfire
Many Mascot business owners are trained to think:
“Pay as little tax as legally possible.”
That’s understandable. But when you want to buy a $1.0–1.5m unit or townhouse in Mascot, the maths can flip.
Worked comparison – aggressive tax minimisation vs borrowing capacity
Assumptions:
- Company profit before owner’s wage and adjustments: $220,000
- Mascot borrower wants to buy a $1.3m unit with 20% deposit
- Approximate safe debt: 4.5–6 times income (see From Mascot Apartment To Family Home: Your Safe Borrowing Range)
Scenario A – minimise tax
- Wage: $70,000
- Extra profit offset with large deductions and super: $50,000
- Declared taxable income: $70,000
- Tax bill: roughly $14,000–$15,000
- Many lenders: usable income for servicing ≈ $70,000–$85,000 after modest add‑backs
- Rough bank borrowing power: $350,000–$450,000
Scenario B – optimise for home loan, not minimum tax
- Wage: $130,000
- Fewer one‑off deductions and super deferrals
- Declared taxable income: $130,000
- Tax bill: roughly $33,000–$35,000
- Many lenders: usable income ≈ $130,000–$145,000 with add‑backs
- Rough bank borrowing power: $650,000–$850,000
Difference:
- Extra income declared: $60,000
- Extra tax: ≈ $18,000–$20,000
- Extra borrowing power: $300,000–$400,000
In Mascot prices, that can be the difference between a tired unit on a main road and a good‑quality, family‑friendly townhouse.
The question becomes: Is saving ~$20k in tax worth losing ~$300k+ in borrowing power for the next 2–3 years?
In many cases, the answer is no.
2.2 Multi‑year consequences
Remember, lenders often look at two years of data.
If you aggressively minimise tax over two consecutive years while you’re also planning to buy, you can lock in:
- Lower borrowing capacity across multiple lending cycles, and
- A forced reliance on alt‑doc/low‑doc lenders, usually at higher rates and tighter terms.
That doesn’t mean you go to the other extreme and pay unnecessary tax. It means:
- You pick your battles in the two years leading up to a planned purchase or refinance.
- You build a joint plan with your accountant and broker, instead of each working in isolation – an approach we reinforced in our guide on complex professional income at [/insights/partners-directors-practice-owners-structure-income-banks-lend].
3. Timing options: when to lodge returns around a Mascot purchase
3.1 Four common timing patterns
There are four typical scenarios for self‑employed Mascot borrowers.
Scenario 1 – Strong last year, not lodged yet
- FY23 lodged: $95,000 taxable income
- FY24 (draft accounts): $140,000 taxable income
Options:
- Lodge FY24 early. Lenders can now use an average of ~$117,500 or, with some, the latest year’s $140,000 if the story is consistent.
- That might lift borrowing capacity by $150k–$250k+ compared with using FY23 alone.
When this makes sense:
- You’re ready to buy or refinance within the next 3–12 months.
- You’re comfortable with the higher tax bill and can fund it without draining your home deposit or buffer.
Scenario 2 – Weak last year, strong prior years
- FY22 lodged: $130,000 taxable income
- FY23 lodged: $125,000 taxable income
- FY24 draft: $80,000 taxable income (sickness, one‑off downtime)
Options:
- Many lenders will let you apply now using FY22 and FY23.
- If you lodge FY24 at $80k, some lenders will instead:
- Use the lowest year ($80k); or
- Average FY23 and FY24: ($125k + $80k)/2 = $102,500.
If you’re targeting a Mascot upgrade or refinance soon, lodging FY24 too early could cut borrowing power by $100k–$200k.
You might deliberately:
- Apply now using FY22/FY23, and
- Lodge FY24 only after your purchase settles, staying inside ATO due dates and late‑lodgement risk.
Scenario 3 – No recent lodgements, behind with ATO
- Last lodged year: FY21 or older
- You want to buy a Mascot unit in the next 6–12 months
Reality check:
- Major banks will generally not lend without up‑to‑date returns.
- You may find a niche alt‑doc lender, but you’ll often face:
- Higher interest rates
- Lower maximum LVRs (e.g. 70–80%)
- Extra scrutiny on ATO debts
Your priority becomes:
- Get returns lodged in a logical sequence (oldest first) with your accountant.
- Coordinate with a broker who can flag when you’ve done enough to open up reasonable lending options.
For guidance on turning messy accounts into a bank‑ready story in a week, see Turn Chaotic Self‑Employed Accounts Into a Bank‑Ready Story Fast.
Scenario 4 – Expecting a large tax bill
- You’ve run strong profit and paid minimal PAYG instalments.
- Draft numbers show a large ATO bill coming once you lodge.
You need to model:
- Your post‑tax cash position after paying or structuring that bill.
- Whether you’ll still have:
- Deposit + stamp duty + costs, and
- A 6–12 month buffer for self‑employed borrowers (see multiple guides, including [/insights/debt-red-flags-unsustainable-what-to-do-early]).
If paying a big tax bill will wipe your buffer to zero, you may need to:
- Reduce your purchase price target;
- Sequence it: lodge → agree a payment plan → rebuild buffer → then buy; or
- Accept that this may be a 12–18 month plan, not a 3‑month sprint.
4. ATO debts and home loans: what Mascot buyers need to know
4.1 How banks treat ATO liabilities
Most lenders treat ATO debt as a real liability, just like a credit card or personal loan.
They will usually want:
- Confirmation the return is lodged and assessed
- Evidence of an ATO payment plan in place
- Bank statements showing you are meeting that plan on time
Depending on the size and type of debt, a lender may:
- Treat the monthly ATO repayment as a commitment in your servicing calculation
- Ask you to clear the debt before or at settlement (using savings or equity)
- Decline the loan if they see the debt as symptom of poor financial control
4.2 Example: ATO debt impact on Mascot borrowing power
Assume:
- Mascot borrower’s usable income (after shading, etc.): $130,000
- No other debts; targeting a $900,000 loan
- Indicative P&I repayment at stressed rate 8% over 30 years ≈ $6,606/month
- This is ~61% of after‑tax income (~$128k net ≈ $10,666/month), too high for most lenders.
They might cap the loan around $650,000–$750,000, to keep stressed repayments closer to 35–45% of after‑tax income (see From Mascot Apartment To Family Home: Your Safe Borrowing Range).
Now add an ATO payment plan:
- ATO debt: $40,000, on a 3‑year payment plan
- Monthly payment ≈ $1,111
The bank now assesses:
- Home loan stressed repayment + ATO repayment
- That may cut loan capacity by $80,000–$150,000, depending on lender tolerances.
4.3 Should you pay ATO in full before you buy?
There’s no one‑size answer, but you need to balance:
-
Clearing the ATO debt:
- Pros: boosts servicing; cleans up your story.
- Cons: may shrink your deposit and buffer too much.
-
Keeping an ATO payment plan:
- Pros: preserves cash for buffer and stamp duty.
- Cons: reduces borrowing power; not all lenders like it.
In most Mascot cases, we aim for:
- No unarranged ATO debt at the time of application.
- Either:
- A manageable, well‑documented payment plan included in servicing; or
- A partial pay‑down so the residual ATO debt plus home loan still fits a safe repayment limit.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 8 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.