
Article
How Self‑Employed Aussies Turn Lumpy Income Into Bank‑Ready Borrowing Power
Self‑employed income doesn’t need to be smooth for you to get a home loan. It just needs to be translated into a story banks can trust. Here’s how to do that in practical steps you can start this week.
Key Takeaway
Self-employed borrowers can turn lumpy or seasonal income into stable borrowing power by demonstrating consistent earnings over 12–24 months, using tools like two‑year averaging, add‑backs, and carefully chosen full‑doc or alt‑doc policies. Lenders in Australia typically apply a 3% serviceability buffer and will shade variable income, but structuring drawings, BAS, and cash buffers can materially lift assessable income. The key actionable step is to map your last 24 months of income and choose a lending path before lodging your next tax return.
This topic is covered in full on Tailored Loans Sydney
Self‑employed income doesn’t need to be smooth for you to get a home loan. It just needs to be translated into a story banks can trust. Here’s how to do that in practical steps you can start this week.
Read the full guide on tailoredloans.sydneyMost self‑employed people don’t miss out on home loans because they earn too little. They miss out because their income looks too lumpy and chaotic on paper. Turning irregular income into bank‑ready borrowing power is about translation and timing, not pretending your business is a PAYG job.
In Australian lending, lumpy self‑employed income becomes stable borrowing power when you can show (1) a consistent or explainable pattern over 12–24 months, (2) reliable minimum earnings after business costs and tax, and (3) enough buffer to handle the APRA‑mandated 3% interest rate buffer lenders use for serviceability testing.
I’ll walk through how I do this with clients every week, and what you can realistically change in the next month – not just over the next three financial years.
A real client with ‘ugly’ income and a strong borrowing story
A few months ago I worked with a café owner whose numbers, on the surface, looked terrible:
- Year 1: COVID recovery, taxable income only $68,000
- Year 2: Bounce‑back year, taxable income $190,000
- Actual cash in her pocket in Year 2 was much higher once we stripped out one‑off expenses.
Her accountant had legitimately minimised tax in Year 1. Great for the ATO bill, terrible for a home loan. The mistake I see most is assuming the bank will intuitively ‘get’ that this year was better than last.
What we did instead:
- Chose a lender that would use the latest year only (not a two‑year average).
- Identified about $40,000 of valid add‑backs (non‑recurring legal fees, depreciation, and interest on a business loan being refinanced away).
- Had her accountant sign off on a steady‑state income letter backed by BAS and bank statements.
On paper, we turned a two‑year average of ~$129,000 into a bank‑assessed income of just over $230,000. Same business. Same café. Better story.
That’s what I mean by turning lumpy income into stable borrowing power.
How banks actually read lumpy self‑employed income
The three big lenses lenders use
Whether you’re a sole trader, partnership or director, most lenders will look at:
-
Timeframe
- Typically your last two years of tax returns and financials.
- Some will use latest year only if it’s higher and the uplift is explainable.
- Alt‑doc lenders might lean on 12 months BAS or 6–12 months bank statements.
-
Stability and trend
- Is income rising, flat or falling?
- If Year 2 is sharply higher, they’ll ask why. If Year 2 is lower, many will average or even just use the lower figure.
-
Stress‑tested affordability
- Your assessed income is tested against repayments at current rates plus at least 3% (APRA buffer).
- Even if the bank approves more, I encourage clients to keep total home and investment loan repayments under 30–35% of after‑tax income when modelled at that buffered rate. That rule of thumb comes up again and again across our work with self‑employed borrowers.
How ‘variable’ income gets shaded
Lenders don’t treat all dollars equally. The more volatile something looks, the more they’ll shade it:
- Base business profit: usually taken close to 100% (after adjustments).
- Overtime/extra shifts for contractors: may be shaded to 80%.
- Bonuses, commissions, seasonal spikes: they’ll average over 1–2 years.
- New contracts or sudden growth: often ignored unless there’s a clear track record.
Your job is to push as much of your real, recurring income into that first bucket – steady, explainable profit – and to document the rest.
For a deeper dive on choosing between cleaning up for full‑doc or using alt‑doc policies, see /insights/maximising-borrowing-power-self-employed-low-doc-vs-full-doc.
Step 1: Map your last 24 months – turn chaos into a pattern
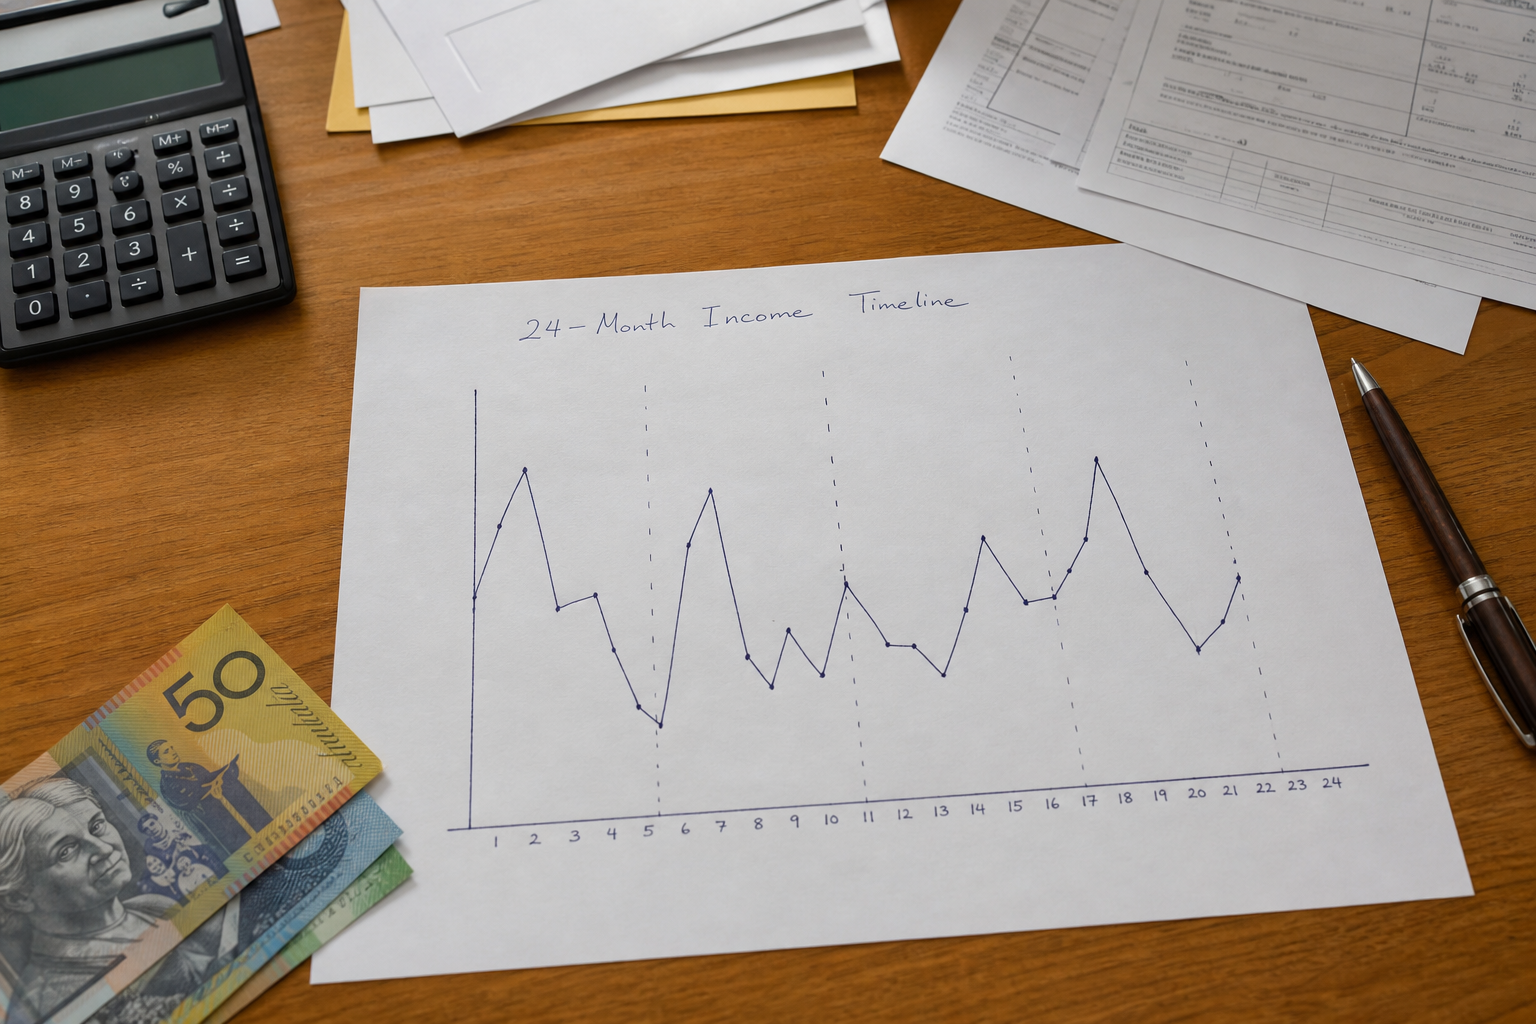
Build a simple income timeline
What I tell my clients: before we talk lenders, we need a single page that tells the story of your income.
Create a 24‑month timeline with:
- Monthly business income (sales or fees invoiced).
- Key costs (rent, staff, big one‑offs).
- What you actually paid yourself (drawings, wages, dividends).
- Major events (COVID, a contract loss, a move, renovation, new staff, new equipment).
You’ll usually see one of three patterns:
- Seasonal: big quarters, slow quarters (tradies, tourism, agriculture).
- Project‑based: long quiet periods then big invoices (consultants, creatives, IT).
- Growth curve: weak first year, sharp ramp‑up (start‑ups, new practices).
Each pattern has a different best‑fit lending strategy.
Translate irregular into a minimum safe level
Banks don’t care about your record month. They care about your floor.
Ask yourself:
- Across the last 24 months, what’s the lowest rolling 3‑month average you earned, after business expenses?
- Is that level repeatable in a bad year?
That figure, not your best year, should anchor your safe borrowing limit. Then you can layer growth on top as upside, not as something you must have to survive.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 6 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.