Article
Why Smart Investors Use Different Lenders Across Their Portfolio
Written and reviewed by James Chee, CPA · Last reviewed
Using multiple lenders across your property portfolio can preserve borrowing power, reduce risk, and keep exit options open. Here’s how to structure it safely in Australia.
Key Takeaway
Using different lenders across a geared property portfolio helps protect borrowing power, reduce cross-collateralisation risk, and keep refinancing options open as tax rules on negative gearing tighten. By splitting securities and serviceability across banks, investors can often access 5–20% more usable capacity over time than concentrating with one lender, especially when combined with purpose-specific loan splits. A one-week review with a CPA-grade broker can map which loans to separate, refinance, or leave untouched for maximum flexibility.
Watch the short answer
Is Your Accountant Only Looking Backwards at Your Tax Papers?
While you’re weighing up using different lenders across your portfolio, this video shows how old tax returns can still shape what’s possible now.
Read the transcript
If your accountant is still working on your past tax papers, traditional bank branch staff will tell you that you cannot apply for a loan. They're wrong. We use alternative documentation frameworks that allow us to verify your true financial trajectory using your active rolling business bank statements. Don't let backlogged accounting portals freeze your personal wealth. DM me 'ALTDOC' to run your assessment today.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Using multiple lenders across your property portfolio can preserve borrowing power, reduce risk, and keep exit options open. Here’s how to structure it safely in Australia.
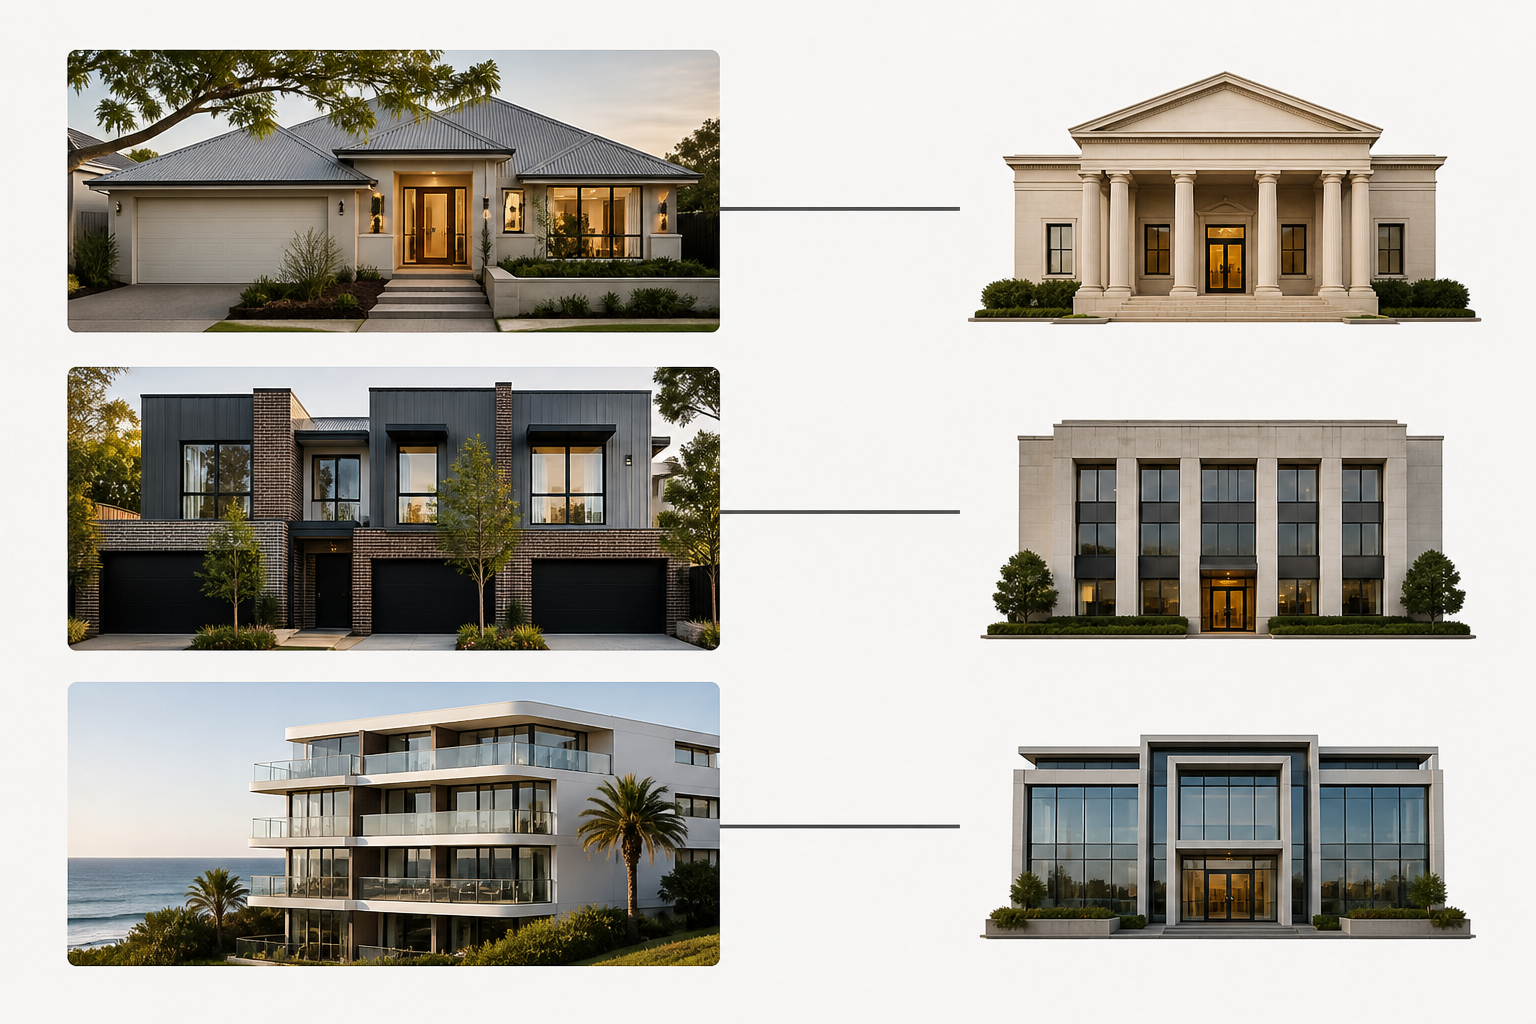
Read the full guide on tailoredloans.sydneyMost geared investors are safer using different lenders across their portfolio, rather than stacking every loan with one bank. Spreading loans and securities helps protect borrowing power, reduce the risk of being “hostage” to one credit policy, and makes it far easier to sell, refinance or regear individual properties later.
In the current environment of tighter investor tax settings and APRA’s 3% serviceability buffer, lender diversification is now a core portfolio risk tool, not a nice-to-have.
Why spreading loans across lenders protects your borrowing power
1. Serviceability rules differ more than you think
Each bank applies its own flavour of the APRA rules. They all:
- Stress-test repayments at ~3% above your rate (APRA buffer).
- Apply Household Expenditure Measure (HEM) benchmarks.
- Shade rental income (often 70–80% usable).
But there are key differences:
- Some accept higher proportions of bonus/commission or self-employed income.
- Some are harsher on existing investment debt or short-stay income.
- Some load higher “assessment rates” on interest-only loans.
Using multiple lenders lets you match each property or purchase to the lender whose policy best fits that specific deal.
2. One bank can quietly cap your future plans
If all your loans sit with one big four bank and they tighten policy, your entire portfolio’s borrowing power can fall overnight.
You might:
- Fail serviceability for your next purchase even though your cashflow is fine.
- Be unable to refinance an underperforming loan.
- Be forced onto less competitive pricing because you can’t move.
With two or three lenders, a “no” from one doesn’t end the conversation. As outlined in /insights/bank-said-no-investment-refinance-what-to-do, a decline from one bank is often a signal to restructure, not to stop.
Multiple lenders vs one bank: what actually changes?
Comparison: single-lender vs multi-lender portfolio
| Feature / risk | All loans with one bank | Loans spread across 2–3 lenders |
|---|---|---|
| Borrowing power over time | Capped by one policy and HEM settings | Can sequence deals around different lender policies |
| Cross-collateralisation risk | High unless carefully structured | Easier to keep each property as standalone security |
| Ability to sell one property | Bank may force multiple loans to be repaid | Usually can release or reshape just that property’s loan |
| Pricing negotiations | One take-it-or-leave-it discussion | Competing banks create real leverage |
| Exposure to system/IT failures | Full portfolio impacted | Only part of portfolio impacted |
| Admin and statements | Simple, one portal | Slightly more complex, needs a tracking system |
For most geared investors, the extra admin is a small price for structural protection.
How to decide which loan goes to which lender
1. Anchor your home, diversify your investments
A common approach:
- Family home: with a mainstream “anchor” lender offering sharp owner-occupier rates and good offset functionality.
- First couple of investments: with different lenders, each secured only by the specific investment property where possible.
Keeping one primary loan per property with minimal cross-collateralisation is critical, as we’ve covered elsewhere: it lets you sell or refinance a single property without unravelling everything.
2. Use purpose-based loan splits at each lender
Even when using multiple lenders, you still need clear, purpose-based splits:
- Home
- Investment
- Business
Australian tax deductibility follows the purpose of the borrowed funds, not the security property. Clean splits, as discussed in several of our guides, make it far simpler to refinance or move a single split to another lender later without contaminating tax outcomes.
3. Play to each lender’s strengths
Examples:
- Lender A: sharper on owner-occupier P&I, conservative on rent.
- Lender B: more generous with rent, but higher investment rates.
- Lender C: flexible with self-employed income or complex trusts.
You might:
- Keep your PPOR and its offset with Lender A.
- Park a high-yield regional investment with Lender B.
- Place a mixed-use or short-stay property with Lender C, after checking local land tax and short-stay rules as outlined in /insights/land-tax-investment-short-stay-rules-finance-impacts-states.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Business finance
Safely Using Investment Property Equity To Support Your Business
Business finance
Refinancing Investment Loans to P&I Without Killing Your Cashflow
Business finance
How To Combine Negative Gearing, Offsets And Debt Recycling Safely
Home equity in retirement
Use Home Equity For Your Next Investment Without Breaking ATO Rules
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.