
Article
Smart Ways To Use Loan Splits And Offsets When Refinancing
Written and reviewed by James Chee, CPA · Last reviewed
How to use loan splits and multiple offsets when refinancing an investment portfolio so you protect tax deductibility, boost cashflow and keep capacity for your next purchase.
Key Takeaway
Using loan splits and offsets when refinancing an investment portfolio means separating each loan by purpose and linking offsets to key investment and buffer splits, which protects interest deductibility and improves cashflow. Because deductible interest depends on how funds are used, not which property secures the loan, clean splits avoid ATO contamination issues and simplify future changes. The actionable step is to map each existing balance to a single purpose and redesign your structure before you sign any new refinance documents.
Watch the short answer
Can you buy a property before your tax return is done?
While you’re weighing up loan splits and offsets for your refinance, this video shows how your latest tax return timing affects your next buy.
Read the transcript
Think you can't buy a property this year because your accountant hasn't finalised your 2026 tax returns? Think again. If you are a freelancer, a contractor, or a growing business, that means months of lost opportunity. We use alternative documentation pathways that completely bypass the ATO delay. We assess your true borrowing capacity using the last 6 months of your business bank deposits, getting you approved while your competitors are still waiting on paperwork. Stop waiting on tax portals to dictate your property goals. Message me 'ALTDOC', to fast-track your FY27 approval.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
How to use loan splits and multiple offsets when refinancing an investment portfolio so you protect tax deductibility, boost cashflow and keep capacity for your next purchase.
Read the full guide on tailoredloans.sydneyUsing loan splits and offsets when refinancing an investment portfolio means separating each loan by purpose and linking offsets to the right splits so you protect tax deductibility, improve cashflow and keep flexibility for your next purchase.
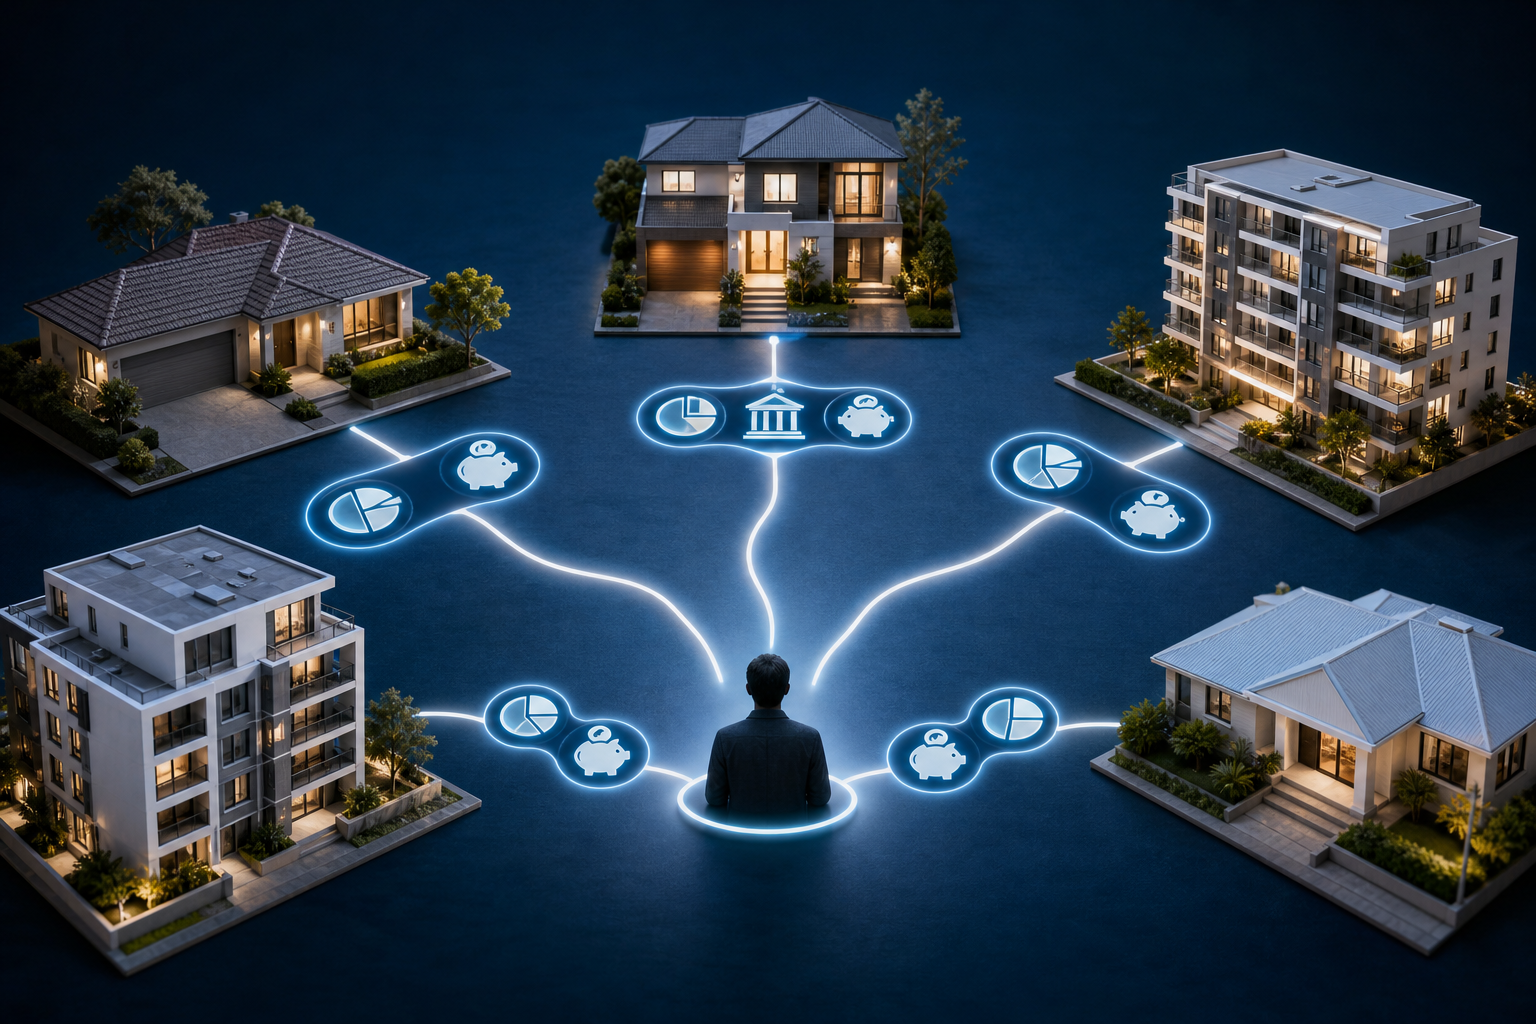
In practice, that looks like one main loan per property, separate equity‑release splits for each purpose, and offsets under the loans where cashflow matters most. Done properly, you can often lift buffers and reduce risk without increasing total debt.
1. What are loan splits and offsets in a portfolio refinance?
1.1 Key definitions
Loan split: one facility broken into multiple sub‑loans, each with its own limit, repayments and purpose (e.g. Property A loan, Property B reno, investment buffer).
Offset account: a transaction account linked to a specific loan split where every dollar reduces the interest charged, but doesn’t change the loan’s tax purpose.
ATO guidance is clear: deductible interest depends on how the borrowed money is used, not which property secures it. Separate splits for each purpose keep this tax tracing clean and support the principles in [/insights/ato-traps-investment-loan-refinance-how-to-avoid].
1.2 Why structure matters more than rate
When you refinance an investment portfolio, you’re deciding:
- Which debts you want gone first.
- How much buffer you need in cash or offset.
- How easy it will be to sell or reshuffle properties later.
A slightly higher rate on a clean, flexible structure often beats the absolute cheapest rate on one messy, cross‑collateralised loan.
2. Core principles: splits, offsets and tax safety
2.1 Keep one main loan per property, then add purpose-based splits
Across our portfolio work, a consistent rule has emerged (see also [/insights/refinancing-3-5-property-portfolio-step-by-step-lvr-lmi-game-plan]):
- One primary loan per property (secured only by that property where possible).
- Extra equity‑release splits for each distinct purpose (deposit, reno, business, buffers).
- No mixed‑purpose redraw.
This lines up with the existing fact base that each new equity release should sit in its own labelled split with a single purpose.
2.2 Offsets beat redraw for flexibility and tax clarity
From a tax perspective, redraw is new borrowing every time you take money out. Use redraw for private purposes and you instantly create a non‑deductible portion that must be apportioned going forward.
By contrast, parking cash in an offset does not change the loan’s tax purpose, even if you later spend that cash privately. That’s why we typically recommend:
- Use offsets for all cash buffers and surplus rent.
- Leave redraw alone on investment loans unless funds are for the same investment purpose.
This approach supports the principles outlined in [/insights/tax-impact-changing-investment-loan-repayments-ato-rules].
2.3 IO vs P&I splits alongside offsets
For many investors, the right mix is:
- Home (non‑deductible) debt on faster P&I with minimal offset.
- Investment debt often on IO with bigger offsets to manage risk.
The detail sits in our IO/P&I guides at [/insights/refinancing-multiple-investment-properties-portfolio-io-vs-p-and-i] and [/insights/smart-io-p-and-i-splits-home-investment-loans]. Here we’re focused on how splits and offsets support that strategy.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.