
Article
Untangling Business, Trust And Personal Debt Before You Apply
Written and reviewed by James Chee, CPA · Last reviewed
Banks now look at your whole group – personal, business and trust – when assessing a loan. Here’s how they actually treat each debt, and what to fix this week before you apply.
Key Takeaway
Australian lenders typically assess business, trust and personal debts on a consolidated basis, with most personally guaranteed facilities treated as personal liabilities for serviceability. This can materially reduce borrowing capacity, especially for directors with multiple entities and SMSFs. By mapping entity structures, clarifying guarantees, and cleaning up short‑term facilities 6–12 months before applying, borrowers can present a clearer income and debt story and preserve capacity for premium property purchases.
Watch the short answer
Using business cash when you’re self‑employed and need finance
If you’re sorting out business, trust and personal debts, this video shows how business cash in your account can support a home loan.
Read the transcript
If you're self-employed, the money sitting in your business transaction account can actually help you buy a house. Business owners often leave heavy cash in their operating accounts for liquidity. Standard business lenders ignore this, but we utilise specialist policies that allow your business account balances to offset or support your personal mortgage application. It's about looking at your complete financial ecosystem, leveraging your business strength to secure your personal wealth. Make your business cash work harder. DM me the word 'LEVERAGE' for a structural review.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Local Knowledge Finance
Banks now look at your whole group – personal, business and trust – when assessing a loan. Here’s how they actually treat each debt, and what to fix this week before you apply.
Read the full guide on ding.financialWhen your business, trust and personal borrowing collide, banks don’t pick and choose – they usually assess the whole group together and treat personally guaranteed debts as yours. If you’re a director, trustee or guarantor, business and trust loans can bite hard into home‑loan or investment‑loan capacity unless they’re structured and documented well.
Below is how the assessment actually works – and what you can fix this week.
1. How lenders really see your “group” debt
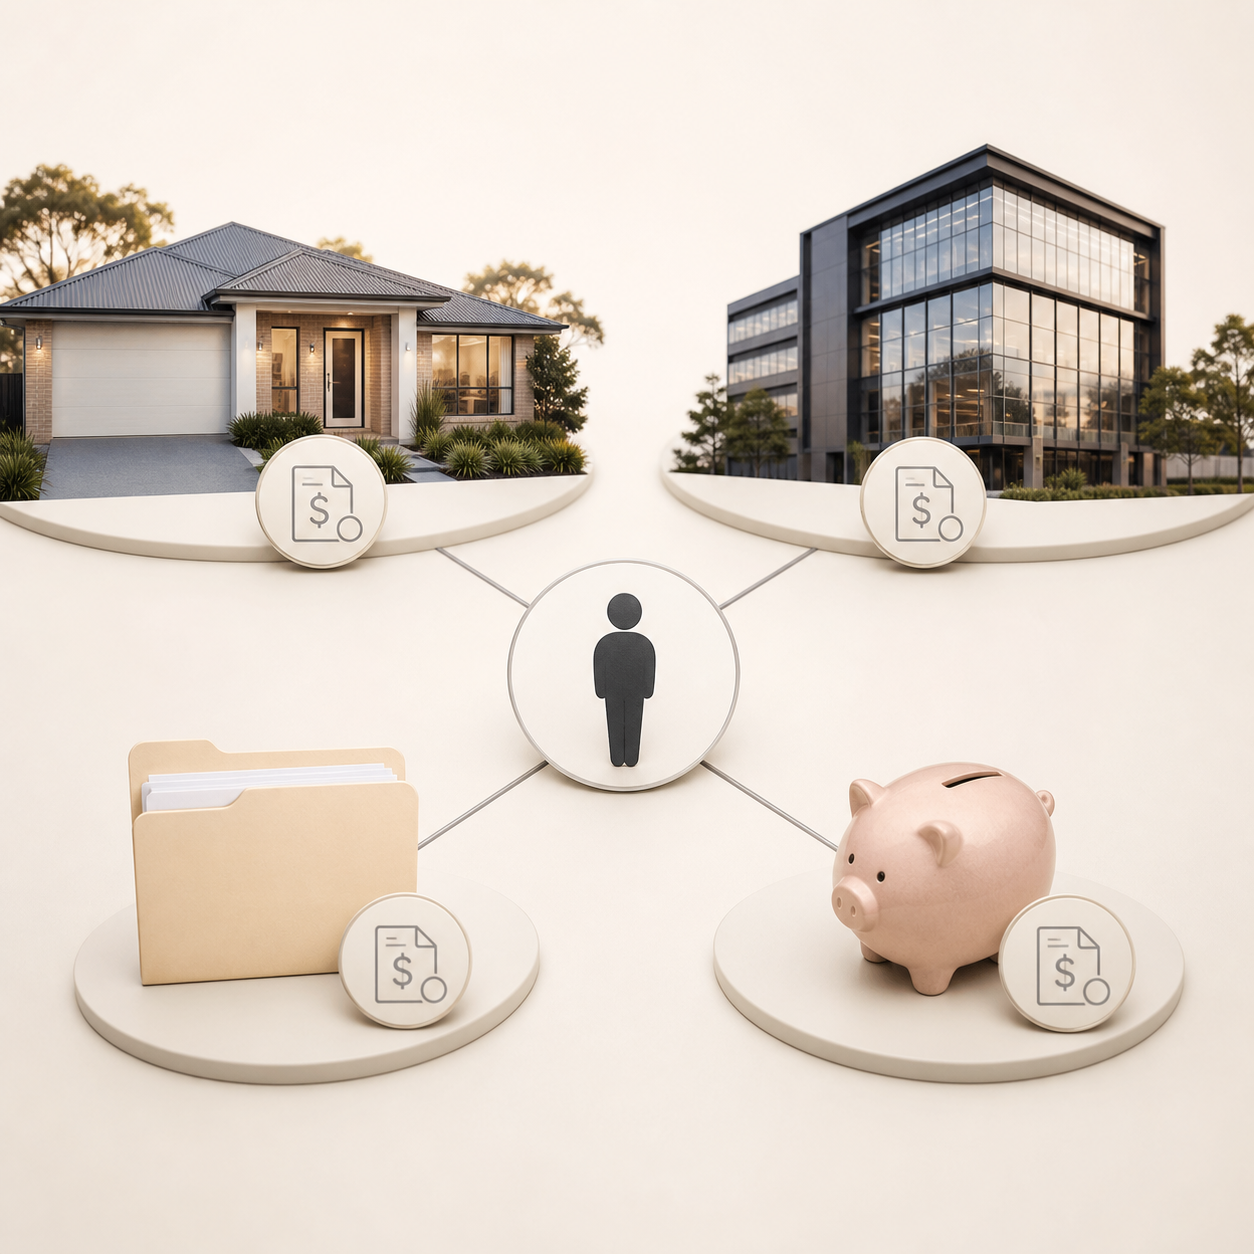
For complex borrowers, most mainstream lenders now:
- Map your structure – personal, companies, trusts, SMSF.
- Pull all ATO, credit file and bank information they can.
- Identify any facility with a personal guarantee and pull it into your personal picture.
- Apply at least a 3% serviceability buffer (APRA) to most variable and short‑term debts.
Key points:
- Personally guaranteed business loans, overdrafts and equipment finance are typically treated as personal commitments in home‑loan assessments.
- Loans to companies or trusts with personal guarantees are almost always counted in your serviceability calculations.
- SMSF and trust properties that “wash their face” on paper can still drag capacity because of buffers on those loans and shade on rental income.
For more detail on how lenders read small‑business numbers, see /insights/how-lenders-view-alexandria-small-business-home-loan.
2. What actually gets counted in serviceability
Here’s how common facilities are usually treated.
| Facility type | Where it sits | How banks often treat it |
|---|---|---|
| Director home loan | Personal | Full repayments assessed with 3% buffer |
| Business overdraft with PG | Company, PG by you | Limit or assessed repayment counted as your personal debt |
| Equipment finance with PG | Company, PG by you | Monthly repayment counted personally |
| Trust investment loan with PG | Trust, PG by you | Full debt + shaded rental counted in your file |
| SMSF limited recourse loan | SMSF | SMSF loan + shaded rent can still reduce personal capacity |
| ATO payment plan (business or personal) | Entity or you | Treated like a term loan with required monthly repayments |
PG = Personal Guarantee.
Income side – the other half of the collision
On the income side, lenders usually:
- Prefer stable salary or director fees over lumpy dividends or trust distributions.
- Average two years of business income, often shading down for volatility.
- Look hard at how much cash actually leaves the business to you after tax.
If your group is geared across a company, trust and SMSF, each extra loan can mean extra buffers and shading, even where the structure looks tax‑efficient.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 3 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Commercial & development
Smart Debtor Finance Around Progress Claims For Builders And Tradies
Commercial & development
Construction Cashflow 101: Progress Claims, Retentions And Funding Gaps
Self-employed lending
How to clean up overdrafts and director loans before a home loan
Self-employed lending
Simple Working Capital Setups For Sole Traders That Stay Tax‑Clean
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.