
Article
Real Numbers: After‑Tax Cashflow on Investment Loans Before and After Reforms
Written and reviewed by James Chee, CPA · Last reviewed
Clear worked examples of how the 2026–27 negative gearing reforms change after‑tax cashflow on investment loans, so you can decide what to buy, hold or sell this week.
Key Takeaway
This article explains how after‑tax cashflow on Australian investment loans changes before and after the 2026–27 negative gearing reforms, using simple worked examples. It compares a typical negatively geared unit and a near‑neutral townhouse under current rules versus quarantined loss rules that apply to many established properties from 1 July 2027. The worked figures show how a pre‑tax loss of around $8,000 can flip from a $2,600 tax refund to a full cash outlay, highlighting the need for updated property cashflow modelling before committing to new debt.
Watch the short answer
Can you buy a property before your tax return is done?
While you weigh the post‑reform cashflow, this video explains how buying before your latest tax return is lodged actually works.
Read the transcript
Think you can't buy a property this year because your accountant hasn't finalised your 2026 tax returns? Think again. If you are a freelancer, a contractor, or a growing business, that means months of lost opportunity. We use alternative documentation pathways that completely bypass the ATO delay. We assess your true borrowing capacity using the last 6 months of your business bank deposits, getting you approved while your competitors are still waiting on paperwork. Stop waiting on tax portals to dictate your property goals. Message me 'ALTDOC', to fast-track your FY27 approval.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Clear worked examples of how the 2026–27 negative gearing reforms change after‑tax cashflow on investment loans, so you can decide what to buy, hold or sell this week.
Read the full guide on tailoredloans.sydneyFor most investors, after‑tax cashflow on an investment loan will be weaker after the 2026–27 negative gearing reforms, especially for established properties bought after 12 May 2026 that won’t be able to offset rental losses against salary from 1 July 2027. You need to model pre‑ and post‑reform cashflow before you buy, restructure or sell.
Here’s the quick rule of thumb:
If your investment was relying on a big tax refund to feel affordable, assume that refund shrinks or disappears under the new rules and check whether the property still works on its own numbers.
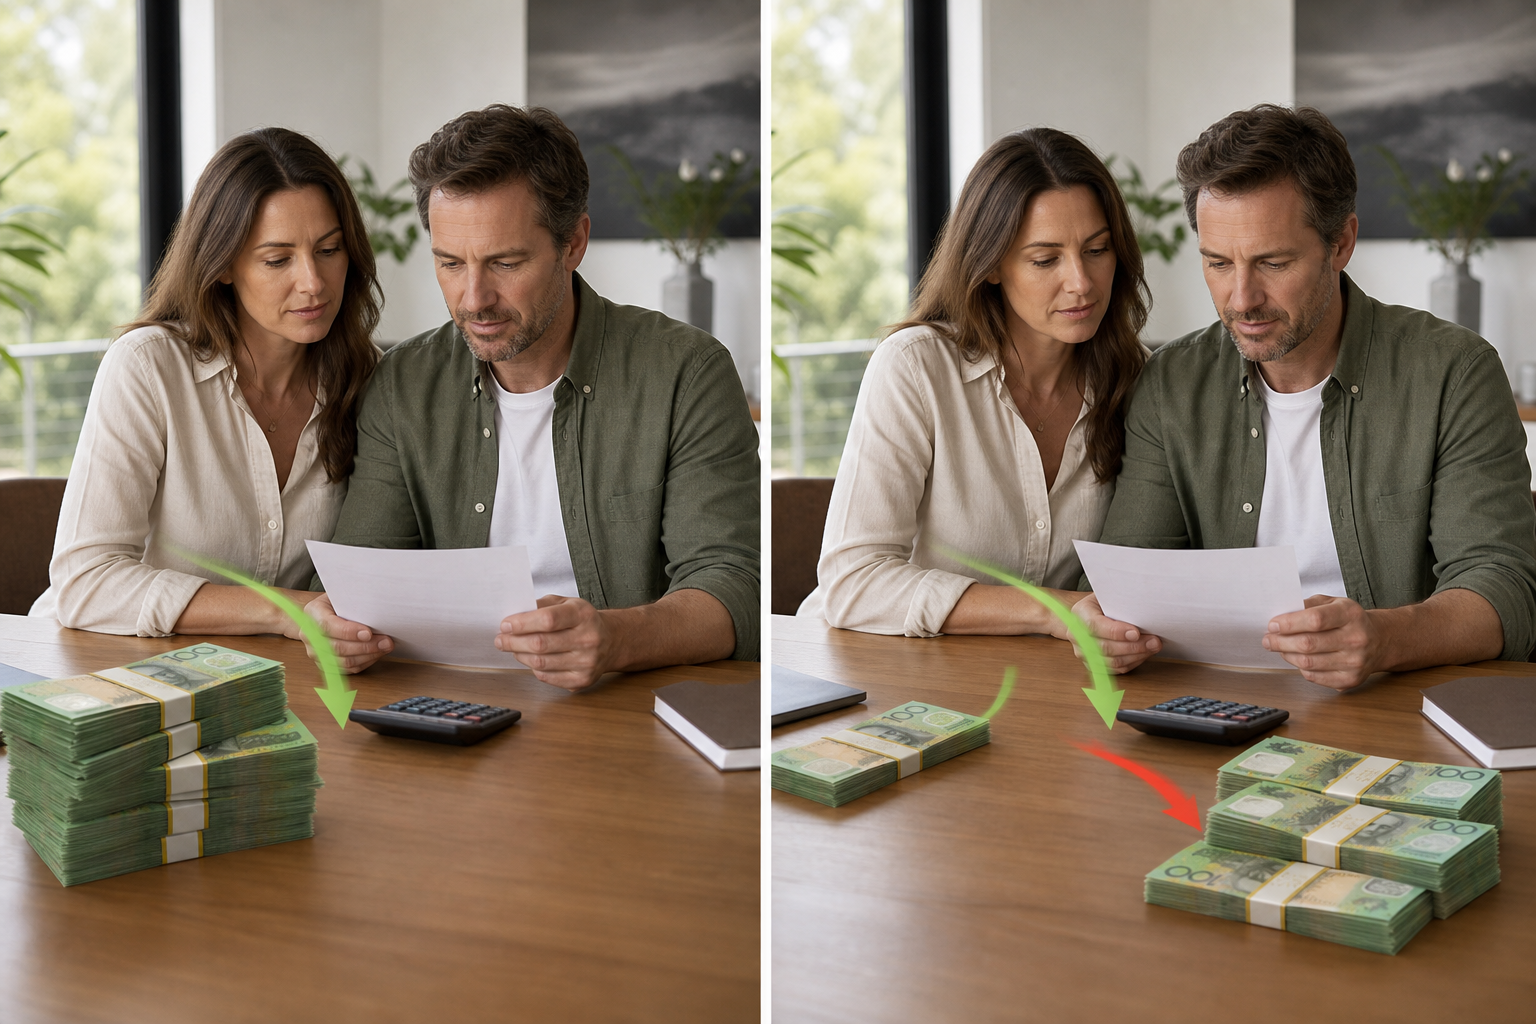
Example 1: Negatively geared unit – before vs after reforms
Assumptions (illustrative only):
- Purchase price: $800,000 established unit (settles July 2026)
- Loan: $720,000 interest‑only, 6.5% p.a.
- Gross rent: $750 per week = $39,000 p.a.
- Non‑finance costs (rates, strata, insurance, maintenance, management): $12,000 p.a.
- Depreciation and capital allowances: $4,000 p.a.
- Investor on marginal tax rate ~37% + Medicare (assume 39%).
Step 1: Pre‑tax cashflow
- Interest: 6.5% × $720,000 = $46,800
- Non‑finance costs: $12,000
Cashflow before tax and depreciation:
- Rent: $39,000
- Less interest and cash expenses: $46,800 + $12,000 = $58,800
- Pre‑tax cashflow (actual dollars): -$19,800 p.a.
This is the real out‑of‑pocket cost before tax and non‑cash deductions.
Step 2: Tax position under current rules
For tax, you also deduct depreciation:
- Deductible expenses for tax: $58,800 + $4,000 = $62,800
- Taxable rental loss: $39,000 − $62,800 = -$23,800
At a 39% marginal rate:
- Tax saving from negative gearing: 39% × $23,800 ≈ $9,282
After‑tax cashflow:
- Pre‑tax cashflow: -$19,800
- Plus tax saving: +$9,282
- After‑tax cashflow (current rules): about -$10,500 p.a. (~-$200 per week)
The investor is still cashflow negative, but the tax refund softens the blow.
Step 3: Tax position after reforms (loss quarantined)
Under the reforms (per the 2026–27 Budget and the Tax Reform No.1 Bill), many established residential properties bought after 12 May 2026 will have rental losses quarantined. In simple terms, you can’t use the loss to reduce your salary; it can usually only offset future rental income or gains from that property.
Mechanically, your pre‑tax cashflow stays exactly the same:
- Still -$19,800 p.a. out of pocket.
But now, the loss no longer produces a $9,282 refund against your wages.
So:
- After‑tax cashflow (loss quarantined): about -$19,800 p.a. (~-$380 per week)
That’s almost $180 per week worse purely from the tax rule change, with the same rent, rate and expenses.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 3 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Business finance
Safely Using Investment Property Equity To Support Your Business
Business finance
Refinancing Investment Loans to P&I Without Killing Your Cashflow
Business finance
How To Combine Negative Gearing, Offsets And Debt Recycling Safely
Business finance
Where To Hold Your Business Premises: SMSF, Property Company or Trust?
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.