
Article
How Coastal Premiums Shape Your Borrowing Power In Sydney’s East
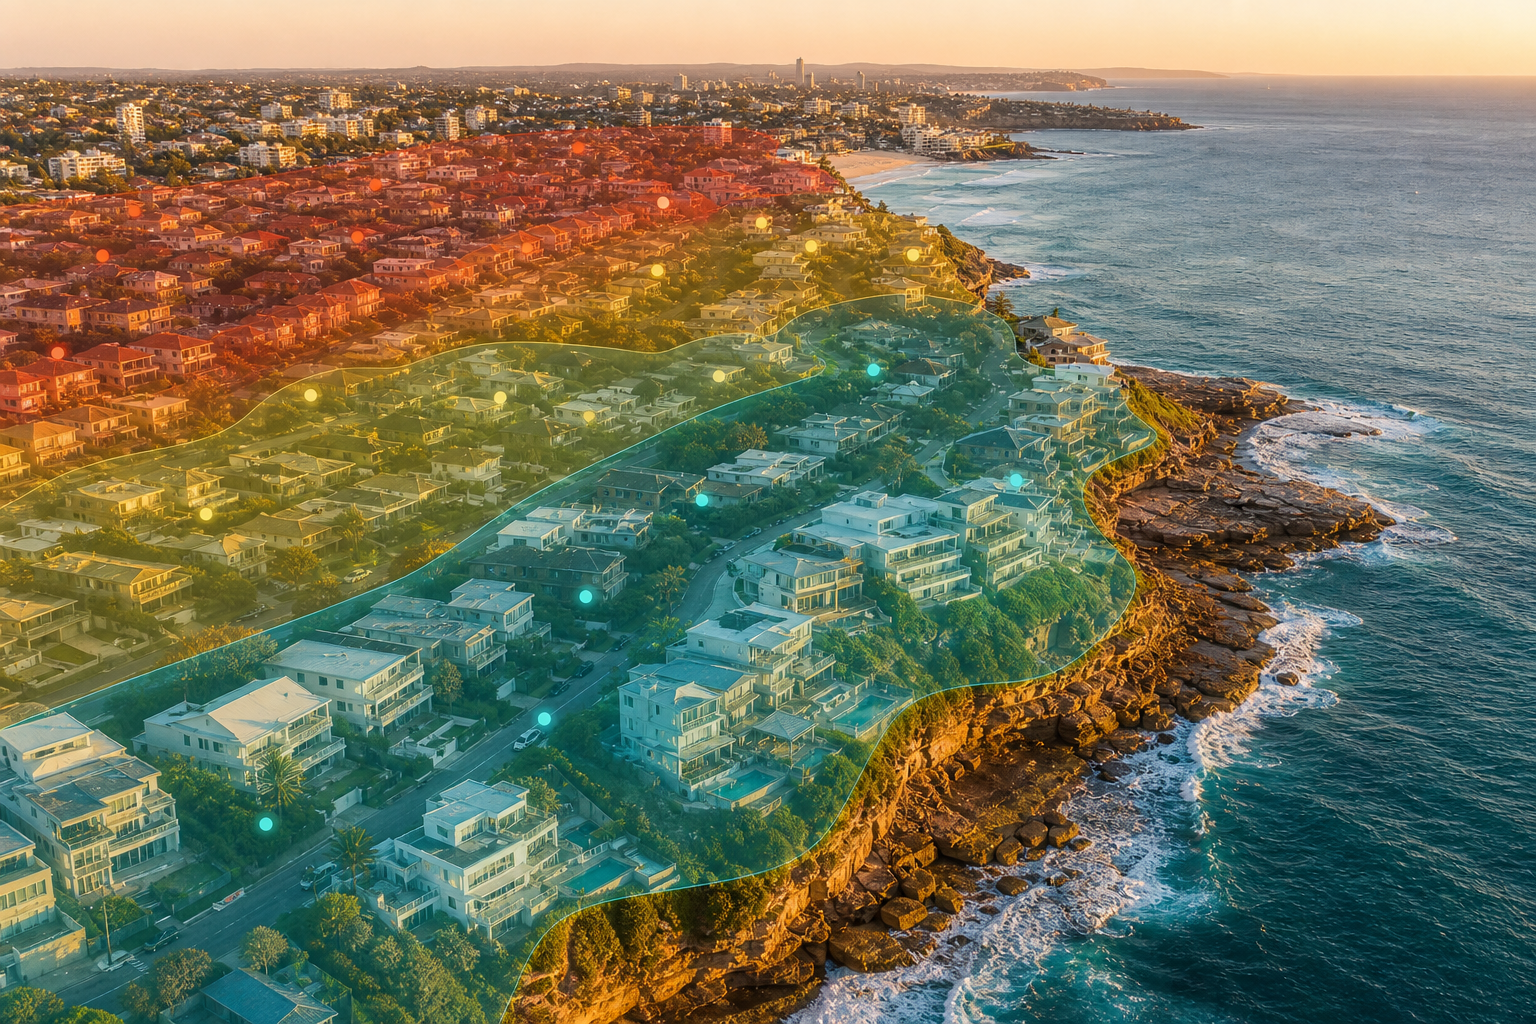
Beachfront and harbour-view pockets in Sydney’s Eastern Suburbs can add hundreds of thousands to a price tag—but also change how banks size your loan. This deep dive turns lifestyle premiums into borrowing numbers so you can act safely this week.
Key Takeaway
This article explains how beachfront and harbour-view premiums in Sydney’s Eastern Suburbs can add 15–40% to property prices but don’t always translate into full bank valuation, directly affecting borrowing power and loan structure. It outlines typical price gaps between beachside and non-coastal pockets, shows how lenders apply a 3% serviceability buffer and shade volatile premiums, and provides numeric examples. Readers learn how to stress-test budgets and select safer streets and loan splits before bidding.
This topic is covered in full on Tailored Loans Sydney
Beachfront and harbour-view pockets in Sydney’s Eastern Suburbs can add hundreds of thousands to a price tag—but also change how banks size your loan. This deep dive turns lifestyle premiums into borrowing numbers so you can act safely this week.
Read the full guide on tailoredloans.sydneyBuying near the beach or with harbour views in Sydney’s Eastern Suburbs almost always costs more – and that premium directly changes how much you can safely borrow.
In practical terms, the coastal premium is the extra price you pay for being on or near the water, or having a strong view line, compared with a similar property a few streets back. Banks and valuers recognise that premium, but they also see it as more volatile. That means your borrowing power, risk profile and loan structure should be different on the coast than inland.
This guide turns that lifestyle premium into numbers you can actually use this week.
1. What “coastal premium” really means in Sydney’s East
1.1 Working definition you can apply this week
For lending purposes, think of the Eastern Suburbs coastal premium as:
The additional amount – often 15–40% – that a buyer pays to be beachfront, within a few hundred metres of the sand, on a clifftop, or with a strong, protected water view, compared with a similar property in the same suburb without those features.
That premium shows up in three ways:
- Absolute price – higher purchase price for similar internal size.
- Price per square metre – especially for units and small blocks.
- Valuation risk – more chance a bank valuer comes in below contract.
The closer you are to the sand or a protected harbour outlook, the more those numbers matter.
1.2 Typical premium ranges by micro-location
Indicative ranges (based on recent Eastern Suburbs sales patterns – not live data, just realistic bands):
- True beachfront unit (Coogee, Bondi, Tamarama) vs similar unit 600–900m back:
- Often +20–35% price.
- Uninterrupted harbour-view apartment (Rose Bay, Dover Heights, Vaucluse) vs same block but low, no view:
- Often +15–30%.
- Clifftop house with panoramic views (Dover Heights, Vaucluse) vs similar house a few streets inland:
- Often +25–40%, sometimes more.
These percentages are exactly what you feel at auction – and exactly what banks quietly discount for risk.
If you haven’t yet, it’s worth reading how lenders see different pockets in the East overall: Finding Real Value in Sydney’s Eastern Suburbs: A Lender’s Street‑Level View.
2. How coastal premiums hit your borrowing power
2.1 The basic arithmetic: higher price, same income
Banks calculate borrowing power primarily from:
- Your after‑tax income.
- Your existing debts and living costs.
- A serviceability test rate – usually your actual rate plus a 3% buffer, in line with APRA guidance.
From your side, our house view – repeated across many Eastern Suburbs profiles – is simple:
Keep total home + investment loan repayments to around 25–35% of after‑tax income, stress‑tested at a rate 3% above today’s rate, even if the bank would lend you more.
If you stretch an extra $400k just to get closer to the sand, that extra debt must still fit comfortably under that 25–35% after‑tax income guardrail.
2.2 Numeric example: beachside stretch vs second‑row sensibility
Assume:
- Household after‑tax income: $260,000 p.a. (~$21,666 per month).
- Comfortable guardrail: 30% of net income on home loan repayments.
- Current home loan rate: 5.9% p.a. P&I.
- Stress‑test rate: 8.9% p.a. (5.9% + 3%).
- 30‑year term.
Scenario A – Second‑row unit (not beachfront)
- Purchase price: $2.0m.
- 20% deposit + costs from savings/equity.
- Loan amount: $1.6m.
At 5.9%, P&I over 30 years:
- Approx repayment: $9,500/month.
At 8.9% stress rate:
- Approx repayment: $12,700/month.
- As % of net income: 58.6% – too high.
So even the second‑row option is already pushing past a 30–35% guardrail at stress‑test rates. You’d likely moderate loan size, extend term, or increase deposit.
Scenario B – Beachfront unit with 25% premium
- Purchase price: $2.5m.
- Same 20% deposit.
- Loan amount: $2.0m.
At 5.9%, P&I:
- Approx repayment: $11,900/month.
At 8.9% stress rate:
- Approx repayment: $15,900/month.
- As % of net income: 73.4% – clearly unsafe.
In other words, the extra 25% price premium blows your safe borrowing envelope, even though a bank calculator might technically approve it, especially if it assumes lower living expenses.
2.3 Why valuers don’t always follow the auction
Coastal premiums are also where bank valuers become conservative. They know from past downturns that:
- View and prestige premiums can compress quickly.
- Investor and holiday‑home demand can evaporate.
- Developers sometimes overpay for land with view potential.
It’s common to see a valuer come in 2–10% below a hot auction result in premium pockets – particularly if there are few recent comparable sales.
On a $3.0m cliffside house, a 7% shortfall is $210,000 – money you may need to tip in as extra cash or restructure from another property.
For more on how different postcode types behave in a downturn, see Eastern Suburbs Postcodes That Hold Value Best When Prices Fall.
3. Price gaps: beach, near‑beach and inland in the East
3.1 Mapping the typical “distance from sand” gradient
Indicative price relationships in many Eastern Suburbs beach pockets look like this:
| Micro‑location (illustrative) | Typical premium vs 1km+ inland | Who usually competes there |
|---|---|---|
| Absolute beachfront / on the promenade | +30–50% | Lifestyle buyers, prestige upsizers, offshore |
| 0–400m from beach, clear aspect | +20–35% | Upgraders, downsizers, some investors |
| 400–900m walk, partial outlook / good street | +10–20% | Families, professionals, balanced OO/investor mix |
| 1km+ inland, still in same suburb | Base level | Value buyers, yield‑focused investors |
These are patterns, not rules. But they give a quick sense of how many extra hundreds of thousands you pay just to move a couple of streets.
3.2 Worked comparison: Coogee‑style unit
Imagine two otherwise similar 2‑bed units in a beach suburb:
- Unit A – Cliff‑top, panoramic view
- Price: $2.1m.
- Strata: $1,800/qtr (lift, older block, higher maintenance).
- Unit B – 800m back, no view, renovated
- Price: $1.7m.
- Strata: $1,100/qtr.
The $400k price difference plus $700/qtr extra strata materially changes your monthly cashflow and serviceability.
3.3 Where coastal premiums run hardest – and softest
In complementary guides, we’ve broken Sydney’s East into family strongholds, investor pockets, prestige strips and downsizer enclaves. Along the coast, you’ll usually see:
- Hardest premiums:
- Tight, blue‑chip enclaves with limited stock (Tamarama, North Bondi headlands, certain Dover Heights streets).
- Hybrid lifestyle + prestige corridors described in Navigating $3m+ Prestige Home Loans In Sydney’s Eastern Suburbs.
- Softer, more negotiable premiums:
- Larger, mixed‑stock suburbs where you can move just outside the core “glory street” and save 10–15%.
- Pockets more popular with investors chasing yield – see Where Investors Actually Win In Sydney’s East: Yields, Risk, Loan Tactics.
4. Harbour and ocean views: how banks really see them
4.1 View quality vs bank valuation
Not all “water views” are equal in valuer language. Roughly:
- Premium‑rated views
- Wide, uninterrupted harbour or ocean outlook.
- Protected sightlines (e.g. elevated, front row, height restrictions below).
- Minimal road noise, no immediate development threats.
- Discounted or volatile views
- Peek‑a‑boo glimpses between buildings.
- Views across significant road or commercial roofs.
- Likely to be built out.
Valuers look for recent, comparable sales with similar view quality. If they can’t find strong comps, they may dial back part of the premium, especially in a fast‑moving or speculative market.
4.2 Example: two Rose Bay apartments, two different lender reactions
Assume two 2‑bed units, same building:
| Feature | Apartment 3A – Harbour panorama | Apartment 1C – garden view only |
|---|---|---|
| Sale price | $2.4m | $1.9m |
| Advertised water views | Full-width balcony, 180° | None |
| Comparable recent view sales | Few in last 12 months | Several in last 6 months |
| Bank valuation (illustrative only) | $2.25–2.30m | $1.88–1.92m |
| Implied valuer discount to contract | ~5–6% | ~1% |
The buyer of 3A may face a $100–150k shortfall between contract and valuation, while 1C sails through. Same building, same lender, different view risk.
This is a core theme from Finding Real Value in Sydney’s Eastern Suburbs: A Lender’s Street‑Level View: hyped streets with thin evidence of support often get the toughest treatment.
4.3 Clifftop and prestige strips: double volatility
In clifftop and prestige pockets, the view premium sits on top of:
- Larger land components.
- Architect or builder “brand” premiums.
- Prestige fixtures and fit‑out.
That layered premium is precisely why many lenders treat $3m+ coastal loans as a separate risk tier. As explained in the prestige lending guide, you’ll often see:
- More conservative LVR caps (e.g. 70–80% rather than 90–95%).
- Tougher income verification for bonuses and distributions.
- More scrutiny of short‑term rental or bonus income.
If you’re shopping in those brackets, read Navigating $3m+ Prestige Home Loans In Sydney’s Eastern Suburbs before you set your limit.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 9 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.