Article
Pools, Garages and Add‑Ons: Will They Help Your Rose Bay Loan?
Written and reviewed by James Chee, CPA · Last reviewed
How pools, garages and extras in Rose Bay really affect your bank valuation, borrowing power and loan approval – and which improvements to prioritise this week.
Key Takeaway
Pools, garages and add‑ons affect Rose Bay home loan approval through bank valuation, local comparable sales, and ongoing cost impacts. Lenders typically prefer secure parking and quality, council‑approved additions, while some pools or over‑capitalised works may add less value than they cost. With 32.5% of borrowers nationally now ‘At Risk’ of mortgage stress, borrowers should prioritise features that improve both valuation and cashflow, maintain a 6–12 month buffer, and structure loans by purpose to protect future refinancing options.
Watch the short answer
Why investors stress over their numbers on Sunday evenings
This short clip explains why investors often worry over numbers and when to review your loan costs.
Read the transcript
Sunday evenings is when most investors look at their numbers and stress. If you haven't audit tested your interest rates in the last 12 months, you are quietly paying a loyalty tax to your bank. Lenders keep their best pricing for new customers, leaving existing ones to slowly bleed on higher variable margins. Tomorrow morning, force them to compete. DM me 'AUDIT' and let's run a reality check across your current files.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
How pools, garages and extras in Rose Bay really affect your bank valuation, borrowing power and loan approval – and which improvements to prioritise this week.
Read the full guide on tailoredloans.sydneyIf you’re buying or refinancing in Rose Bay, pools, garages and add‑ons only help your loan when they lift the bank valuation more than they lift your costs or debt. Lenders look at how buyers locally value those extras, how much they cost to run, and whether your total debt still fits safely under APRA’s 3% serviceability buffer.
In practical terms: secure parking and well‑designed, council‑approved additions usually help; some pools and over‑capitalised works can actually hurt your borrowing power.
1. How banks really view extras in Rose Bay
1.1 Three levers that decide your approval
For Rose Bay loans, pools, garages and add‑ons move three key levers:
- Bank valuation – what a valuer thinks the property is worth today, based on recent local sales.
- Serviceability – whether you can afford the debt tested at a rate 3% above current (APRA buffer).
- Risk profile – build quality, compliance, maintenance costs and resale appeal.
If an extra ticks all three, it’s usually a positive. If it helps valuation but damages serviceability (for example, high strata or maintenance), the lender may shade the value or cap your borrowing.
For why two similar‑looking properties can value very differently, see /insights/why-two-eastern-suburbs-properties-valued-so-differently.
1.2 Rose Bay vs Bronte: similar rules, different land
The same broad principles we covered for Bronte in /insights/pools-garages-add-ons-bronte-loan-approval apply in Rose Bay, but land and parking scarcity differ street‑by‑street. In some Rose Bay pockets, off‑street parking is almost mandatory for strong resale. In others, prestige views can outweigh the lack of a garage.
Valuers anchor to recent comparable sales: if buyers have recently paid a premium for garaging or a pool in your micro‑area, your valuation benefits. If not, the bank may treat the extra as almost cost‑neutral.
2. Pools: when they help and when they hurt
2.1 Valuation impact of a pool in Rose Bay
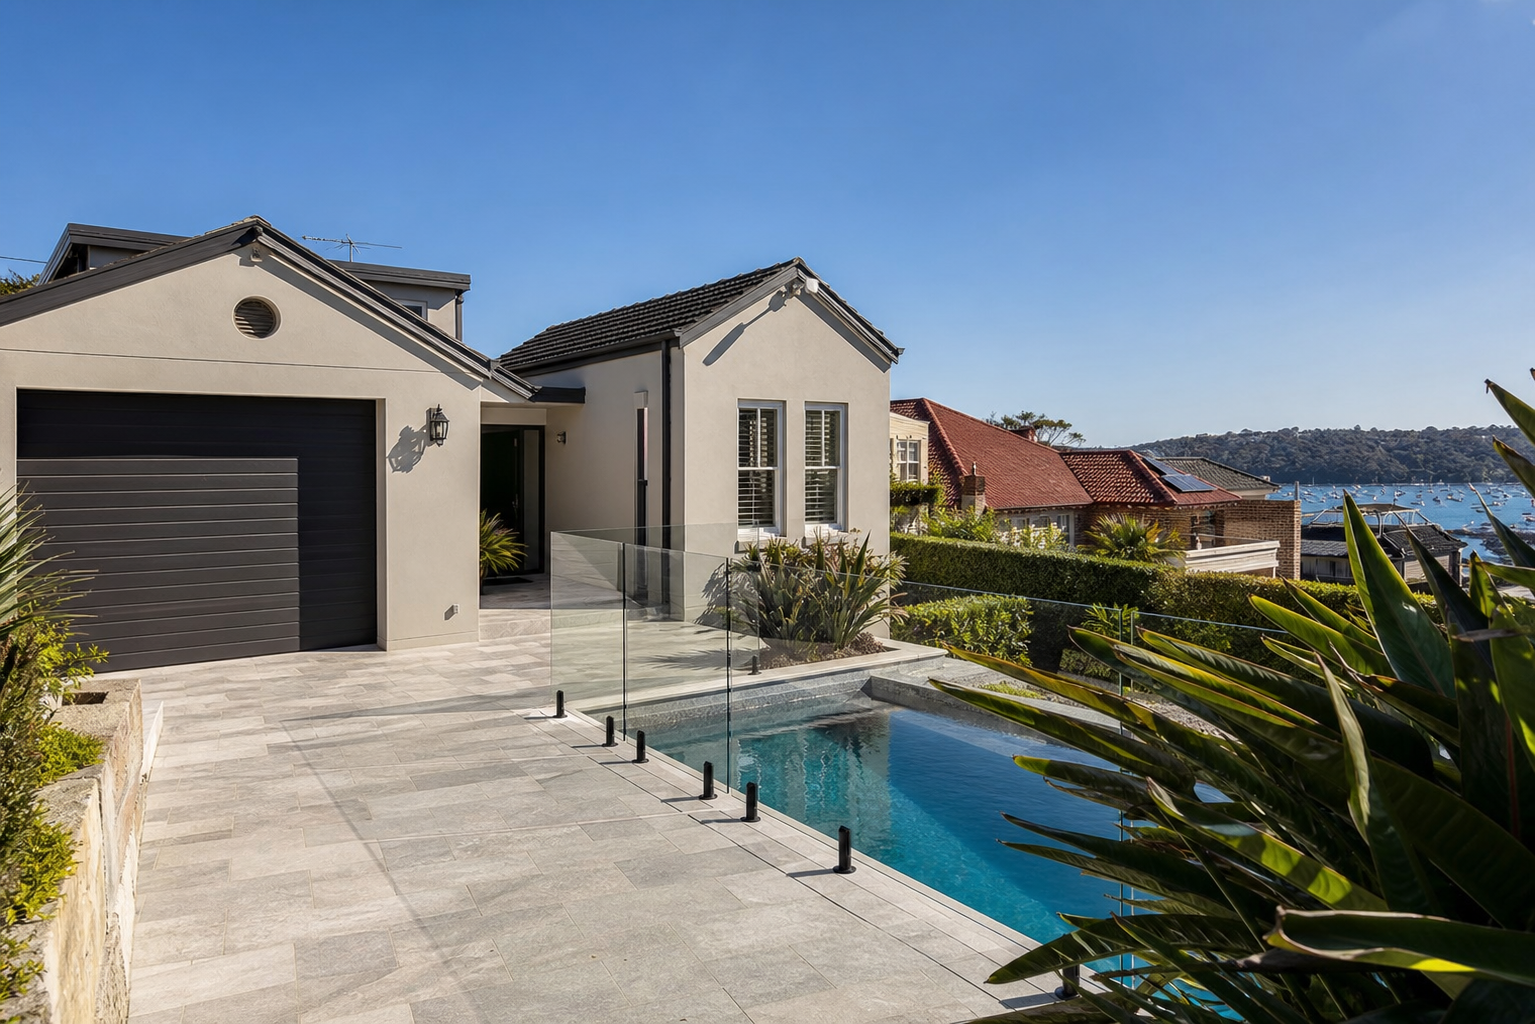
A pool can add strong value on certain Rose Bay streets, especially for family homes with level access and private gardens. But lenders care about evidence, not emotion.
Typical patterns:
- Freestanding homes on good blocks: a modern, well‑landscaped pool can improve buyer demand and valuation.
- Tight sites / difficult access: construction risk, drainage and neighbour issues may worry valuers.
- Units with shared pools: depends on how buyers see the complex and whether the strata fees look reasonable.
2.2 Ongoing costs and mortgage stress
Pools bring running costs – power, chemicals, servicing, possible repairs. With Roy Morgan estimating around 32.5% of Australian mortgage holders ‘At Risk’ of stress in 2026, banks are very sensitive to any feature that lifts your cost base.
Lenders won’t line‑item pool costs, but they do rely on HEM‑based living expenses and test your loan 3% above current rates. That’s why we consistently recommend maintaining 6–12 months of stressed repayments plus essential living costs in cash or offset for Eastern Suburbs properties.
2.3 Example: buying a Rose Bay house with a pool
- Purchase price: $4,000,000 (including a quality pool)
- Deposit: 20% = $800,000
- Loan: $3,200,000
- Rate tested at: current 6% + 3% buffer = 9% (illustrative only)
- P&I over 30 years at 9%: about $25,800 per month
Add even a modest $400–$500 per month of pool and garden upkeep and you can see why banks want your total repayments below roughly 30–35% of after‑tax income.
If you’d be near the edge, consider downgrading the property or negotiating price, not skipping the buffer.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Suburb guides
Heritage overlays in Bellevue Hill, Vaucluse and Rose Bay: risk or edge?
Suburb guides
Financing Rose Bay Homes With Marinas, Moorings And Shared Waterfront
Suburb guides
Helping Family With Rose Bay Equity While Protecting Your Future
Suburb guides
Online Broker vs Local Rose Bay Specialist: How To Choose This Week
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.