
Article
Retail and eCommerce Working Capital: Funding Stock Without Strain
Written and reviewed by James Chee, CPA · Last reviewed
Clear, decision‑grade guide for Australian retailers and eCommerce owners on funding stock, managing sales cycles and discounting without frying cashflow or risking the family home.
Key Takeaway
Australian retail and eCommerce working capital should be structured around stock days on hand, payment terms and discounting plans, not guesswork. Inventory, marketing and fulfilment often tie up 45–120 days of cash, so expensive merchant‑style advances (often 25–35% effective annual cost) are usually poor long‑term funding choices. Owners should map their cash conversion cycle, cap stock cover, and align overdrafts or stock finance limits to a realistic turnover multiple to protect both business resilience and home‑loan plans.
Watch the short answer
Why using cash for tools and vehicles can hurt your business
While you’re weighing up how to fund stock safely, this video shows how financing tools and vehicles can help protect your cash flow.
Read the transcript
Stop using your liquid cash to buy tools, machinery, or work vehicles. When you drain your operating account to buy equipment outright, you look safe to your accountant, but you look highly illiquid to a mortgage underwriter. Use specialised asset finance to keep your cash in your business account where it preserves your personal borrowing. Keep your assets working and your cash liquid. DM me 'FLEET' to protect your cash flow.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Local Knowledge Finance
Clear, decision‑grade guide for Australian retailers and eCommerce owners on funding stock, managing sales cycles and discounting without frying cashflow or risking the family home.
Read the full guide on ding.financialRetail and eCommerce working capital is the cash you need to pay for stock, marketing, freight and platforms before customers actually pay you. Get it wrong and you’re constantly short, on discount panic, or leaning on high‑cost cash‑advance loans that quietly kill profit.
Quick answer: map your cash cycle, cap how much stock you carry, and match the right facility (overdraft, stock finance, short‑term loan) to each part of that cycle.
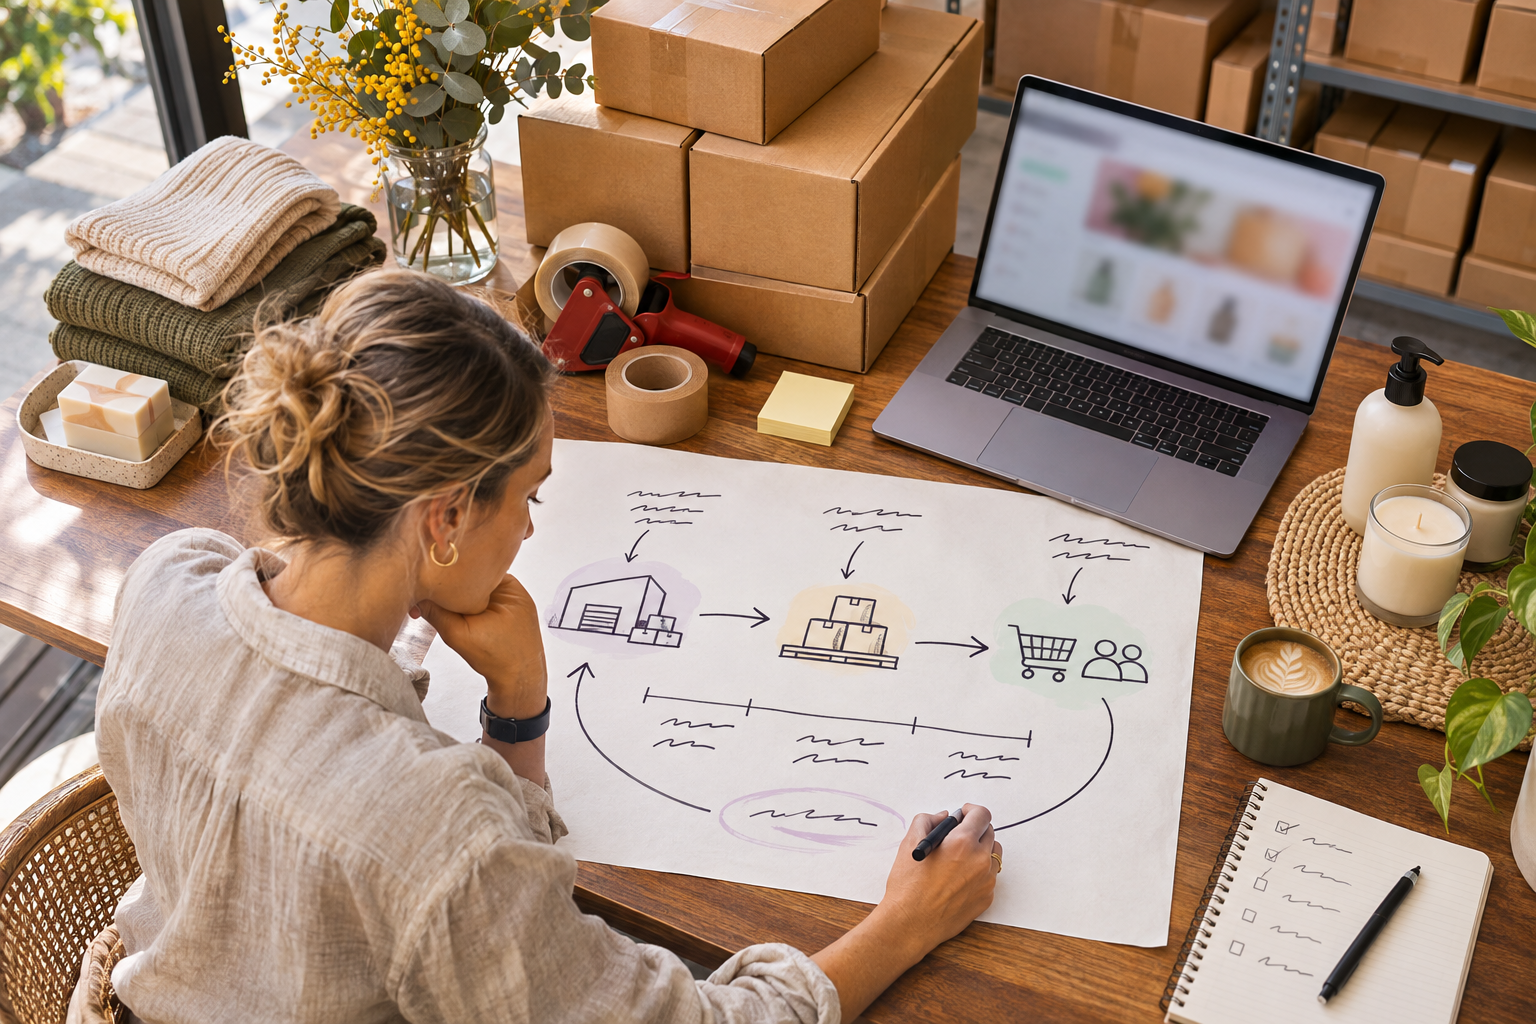
Step 1: Map your retail and eCommerce cash conversion cycle
You can’t choose funding until you know how long your cash is tied up.
At a minimum, write down four numbers:
- Supplier terms: days from ordering stock until you must pay (e.g. 30 days EOM).
- Stock days on hand: average days stock sits before selling (based on recent sales, not hope).
- Customer payment lag: how quickly you get cash (card and online are near‑instant; wholesale accounts may be 30–45 days).
- Returns/discounting drag: extra weeks stock hangs around due to returns, exchanges or heavy markdown cycles.
Add them up and you’ve got your cash conversion cycle.
Quick worked example
An online apparel store:
- Pay suppliers 30 days after invoice.
- Hold 75 days of stock.
- Get paid by customers immediately.
Cash is tied up ~105 days. On $120k of monthly cost of goods, average working capital tied in stock is about:
$120k ÷ 30 days × 105 days ≈ $420k
If you’re funding that on a 30–40% effective annual cost merchant cash advance, most of your margin is disappearing in interest.
If this feels unfamiliar, read Working Capital Basics: Structures, Costs And Safe Limits For SMEs for the core concepts, then come back to the retail specifics here.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Related articles
Commercial & development
Smart Debtor Finance Around Progress Claims For Builders And Tradies
Commercial & development
Construction Cashflow 101: Progress Claims, Retentions And Funding Gaps
Self-employed lending
How to clean up overdrafts and director loans before a home loan
Self-employed lending
Simple Working Capital Setups For Sole Traders That Stay Tax‑Clean
Talk to a broker who is a CPA and Registered Tax Agent
Free consultation, plain-English advice tailored to your situation.