
Article
Turn Planning Maps Into Finance Power: Stress-Test Any Property Fast
How to use council and state planning data to stress‑test any Australian property purchase before you sign. Practical steps, worked examples and finance angles you can act on this week.
Key Takeaway
Australian buyers can stress-test a property by checking local government and state planning data before signing, focusing on zoning, overlays, development approvals and infrastructure plans that affect bank valuations and rental risk. In a market where around 32.5% of borrowers are now ‘At Risk’ of mortgage stress (Roy Morgan, 2026), understanding these planning signals is critical. A systematic check of zoning, development pipeline and local rules lets buyers adjust price expectations, loan structure and buffers or walk away before committing their deposit.
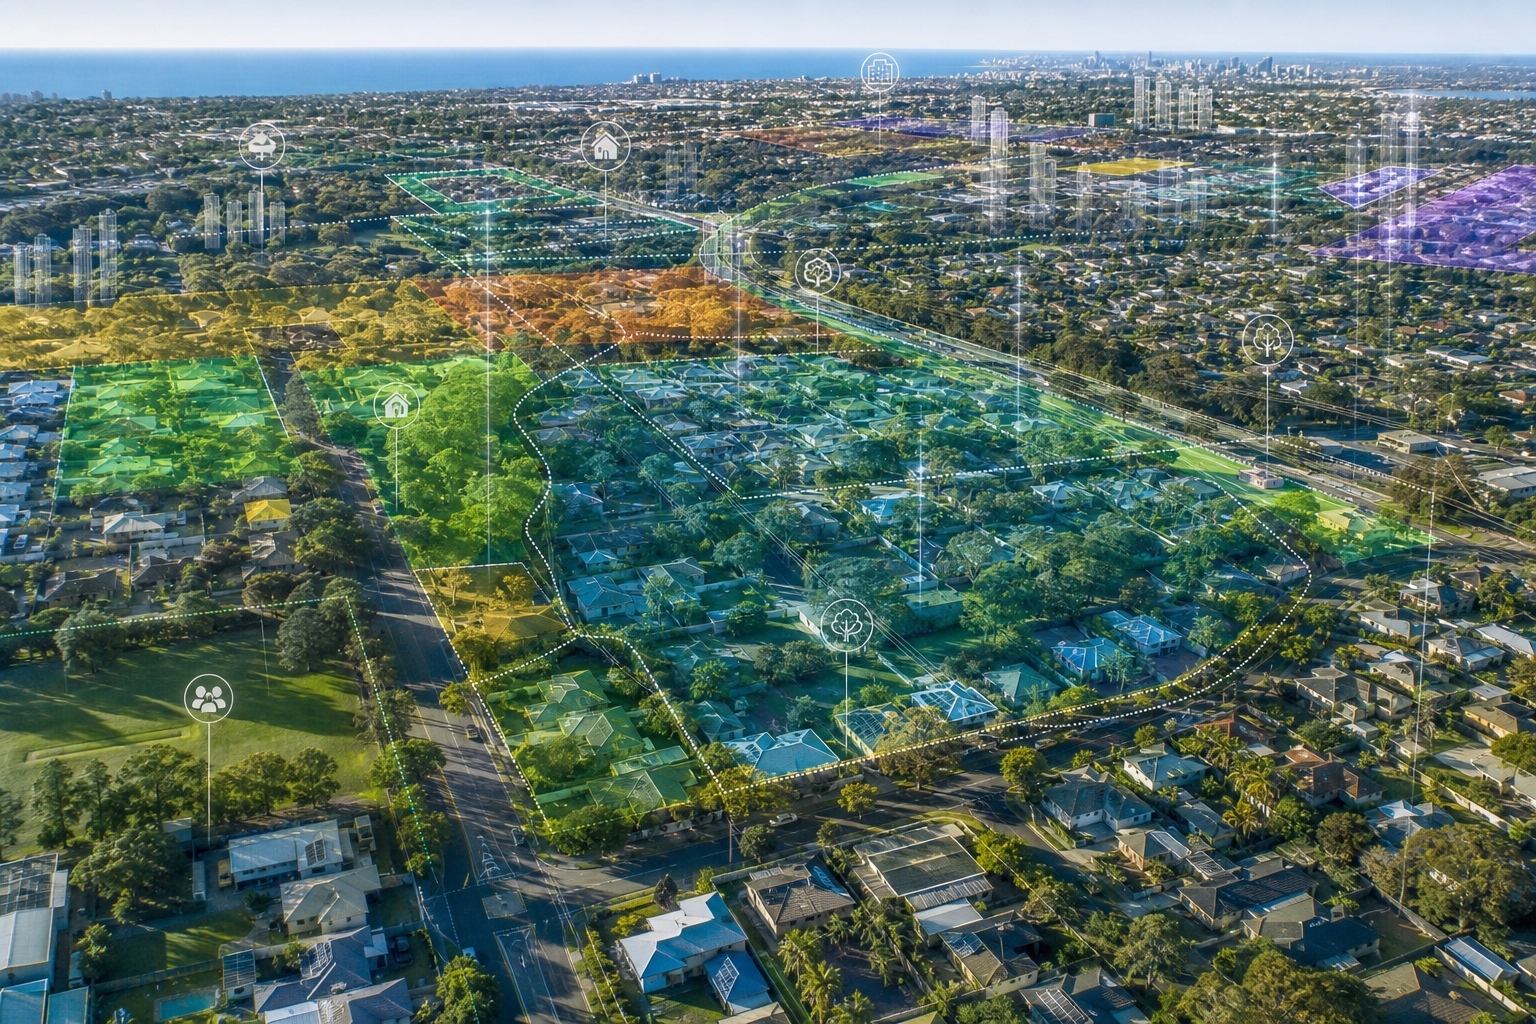
Using council and state planning data to stress‑test a property means checking how zoning, overlays, nearby developments and infrastructure plans might change your home’s value, liveability and finance risk over the next 5–20 years. You’re not trying to become a town planner; you’re running a practical, finance‑grade due diligence pass before your deposit is on the line.
Do this well and you either:
- Buy with more confidence (and better negotiation arguments), or
- Decide to walk away early, before bank valuation issues or mortgage stress become your problem.
This guide is designed so a busy buyer can act on it this week.
1. Why planning data belongs in your finance stress test
Most people look at a property and think bedrooms, kitchens and school zones.
Banks, valuers and councils look at it and think zoning, overlays, easements, flooding and flight paths.
1.1 The link between planning risk and mortgage stress
Roy Morgan’s July 2026 data shows about 32.5% of Australian owner‑occupier borrowers are ‘At Risk’ of mortgage stress, and 22% ‘Extremely At Risk’, driven by higher interest rates and softer incomes.
You can’t control RBA decisions. You can control whether you buy a property that’s:
- Likely to face valuation surprises at settlement or refinance
- Exposed to local shocks (big new developments, loss of amenity, flood overlays)
- Sitting in a zone that banks or insurers quietly treat as higher risk
Planning data is one of the best early warning systems before you commit to a contract.
For a broader lens on local risk, combine this article with the local risk stress‑testing framework in /insights/stress-testing-loans-local-vacancy-tourism-construction-risk.
1.2 What we mean by “planning data” in practice
For this article, planning data means:
- Zoning (residential, mixed use, industrial, rural, etc.)
- Overlays and constraints (flood, bushfire, heritage, airport noise, character)
- Permitted and prohibited uses (what you and your neighbours can and can’t do)
- Development approvals and applications (what’s already coming)
- State or regional plans (major infrastructure corridors, urban renewal)
- Local strategies and structure plans (town centres, density, new roads, school expansions)
Every state brands these slightly differently – LEPs in NSW, Planning Schemes in VIC and QLD, Development Plans/Code in SA, etc. But the logic is the same.
1.3 How lenders indirectly use this information
Lenders rarely talk about planning details in marketing material, but they show up via:
- Valuation risk – comparable sales, stigma (flood/fire), future oversupply
- Location policy – postcode restrictions, maximum LVRs in flood‑prone or mining areas
- Marketability – whether the property would be easy to sell under mortgagee‑in‑possession
That’s why this article sits under the same hub as “State Taxes, Grants and Legal Rules: Why Your Address Matters”. Address choices ripple into tax, land tax, short‑stay rules, and now planning‑driven risk.
2. The core planning checks to run on every property
You don’t need to read the entire Planning Scheme. You need a sharp, repeatable checklist.
2.1 The five non‑negotiable checks
For any house or unit in Australia, run at least these:
- Zoning and permitted uses
- Overlays and constraints (flood, bushfire, heritage, character, contamination)
- Nearby development pipeline (DAs and approvals within ~500 m–1 km)
- State and regional plans (major roads, rail, rezoning, urban renewal)
- Local land‑use quirks (short‑stay rules, land tax nuances, minimum lot sizes)
2.2 Where to find the data (state by state)
Most of this is free online.
| State/Territory | Typical tool name (examples only) | What you can usually see |
|---|---|---|
| NSW | ePlanning Spatial Viewer, council DA tracker | Zoning, overlays, DAs, height limits |
| VIC | VicPlan, council planning maps, Greenlight DA | Zones, overlays, heritage, local policies |
| QLD | City Plan / Planning Scheme maps, DA tracker | Zoning, overlays, neighbourhood plans, DAs |
| SA | PlanSA mapping | Zones, overlays, Code policies |
| WA | Local Planning Scheme maps, state mapping | Zoning, development control, precinct plans |
| TAS/ACT/NT | State/Territory mapping portals + council pages | Zoning, overlays, DAs (varies) |
Always confirm you’re on the official government or council site, not a third‑party listing tool.
2.3 A 15‑minute data‑gathering routine
For each shortlisted property, before inspections if possible:
- Plug the address into the state planning map.
- Note the zone code (e.g. R2 Low Density Residential, General Residential Zone GRZ1).
- Export or screenshot the map showing your block and immediate neighbours.
- Turn overlays on and off – note anything in a legend: flood, bushfire, heritage, noise, character areas.
- Open the local council DA tracker – search the address and adjacent streets for last 3–5 years.
- Open the state/regional plan viewer – look for transport routes, growth areas, urban renewal precincts.
Save everything in a folder for each property. Your broker, solicitor and accountant can then layer their advice over the same evidence.
3. Zoning: what it really means for value and finance
Zoning is the foundation. It shapes what you can do, what your neighbours can do, and how banks and valuers think about the property.
3.1 Common residential‑adjacent zones and their implications
| Zone type (illustrative) | Typical character | Key finance & valuation implications |
|---|---|---|
| Low density residential (R2/NRZ) | Predominantly detached homes, low rise | Often seen as stable, family‑friendly; limited upside from extra development potential |
| General / medium residential (R3/GRZ/MR) | Mix of houses, townhouses, small-medium apartments | More development potential; check for overshadowing, traffic and supply risk |
| High density / mixed use | Taller apartments, retail at ground | Higher valuation and vacancy risk; sensitive to oversupply and incentives |
| Light industrial / business adjacent | Warehouses, small factories, bulky goods | Noise, truck traffic; banks may treat as slightly higher risk for owner‑occupiers |
| Special use / precinct areas | Universities, hospitals, airports, ports | Tight use controls; strong job anchors but also noise/traffic/parking issues |
Banks want properties that are broadly marketable. Unusual or highly restrictive zones can make a property harder to value or sell.
For investors, zoning is a double‑edged sword. Extra development potential can be good – but it also increases the chance that someone else builds next door and steals your views or tenants. See /insights/zoning-changes-urban-renewal-finance-opportunities for a deeper zoning‑opportunities lens.
3.2 Worked example: house zoned general residential vs mixed use
Assume you’re considering two $1,100,000 properties in the same suburb:
- Property A: 3‑bed house in General Residential (GRZ1)
- Property B: 3‑bed terrace in Mixed Use zone near a commercial strip
Both properties would require around $220,000 deposit plus costs at 80% LVR.
Key planning‑driven questions:
- Could the mixed‑use street evolve into a late‑night hospitality strip?
- Are there height controls that allow taller buildings beside Property B?
- Will valuers see more long‑term family demand for the quieter GRZ1 street?
If planning maps show 5–8 storey permissible heights next to Property B and only 2 storeys near Property A, that’s a real, quantifiable risk. A high‑rise next door can:
- Increase overshadowing and privacy concerns
- Change the tenant mix
- Add traffic and parking stress
For a long‑term home buyer, you may decide that:
- You’ll pay no premium for Property B’s current cafe proximity, and
- You want an extra 0.5%–1.0% borrowing capacity buffer before choosing B, in case future valuations lag comparable houses in quieter streets.
3.3 How zoning feeds into your loan structure
Even though lenders don’t underwrite your purchase based on your interpretation of zoning, your understanding helps you:
- Choose a more conservative maximum purchase price in high‑change zones
- Decide whether to leave extra cash buffer for short‑term construction or vacancy shocks
- Choose between principal & interest vs interest‑only and how quickly you want to de‑risk
This interacts with the practical stress‑testing rules we’ve discussed in other articles – e.g. modelling at least a 3% rate rise, flat rents and some vacancy (/insights/stress-testing-home-investment-loans-with-broker).
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 8 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.