Article
Strata repairs: raise levies, strike a special levy or borrow?
Got big strata works coming and no cash? This guide compares ordinary levies, special levies and strata loans with simple numbers so your committee can choose a funding mix this week.
Key Takeaway
This article explains how to choose between higher ongoing levies, one‑off special levies, and strata loans to fund major building works. It compares cashflow impact, timing, arrears risk and owner hardship, noting that a $1m strata loan can add $500–$1,000+ per lot per quarter over 10–15 years. It recommends modelling per‑lot costs under each option and often using a mix (smaller loan plus staged levies) to balance urgency, equity and stress, then documenting the rationale before voting.
Watch the short answer
Why active ATO debt can hurt your business finance options
See why lenders treat unpaid ATO debts differently to other business liabilities.
Read the transcript
An active ATO debt is a massive red flag that triggers an instant computer rejection at every major bank. The Tax Office is the most expensive lender you can have. If you have equity in your property, we can restructure that debt. We use specialist capital channels to clear the ATO entirely, moving that high-stress liability into a single clean facility. Give your business room to breathe. DM me 'CLEAR' to start.
General information only, not personal advice. Your situation is assessed before any recommendation.
When big strata works land, your real choice is: raise ongoing levies, strike a special levy, take a strata loan – or some mix.
The best option is the one that: 1) gets the work done on time, 2) keeps per‑lot cashflow tolerable, and 3) doesn’t blow up arrears or future lending options. That means running numbers for each path and stress‑testing them before you vote.
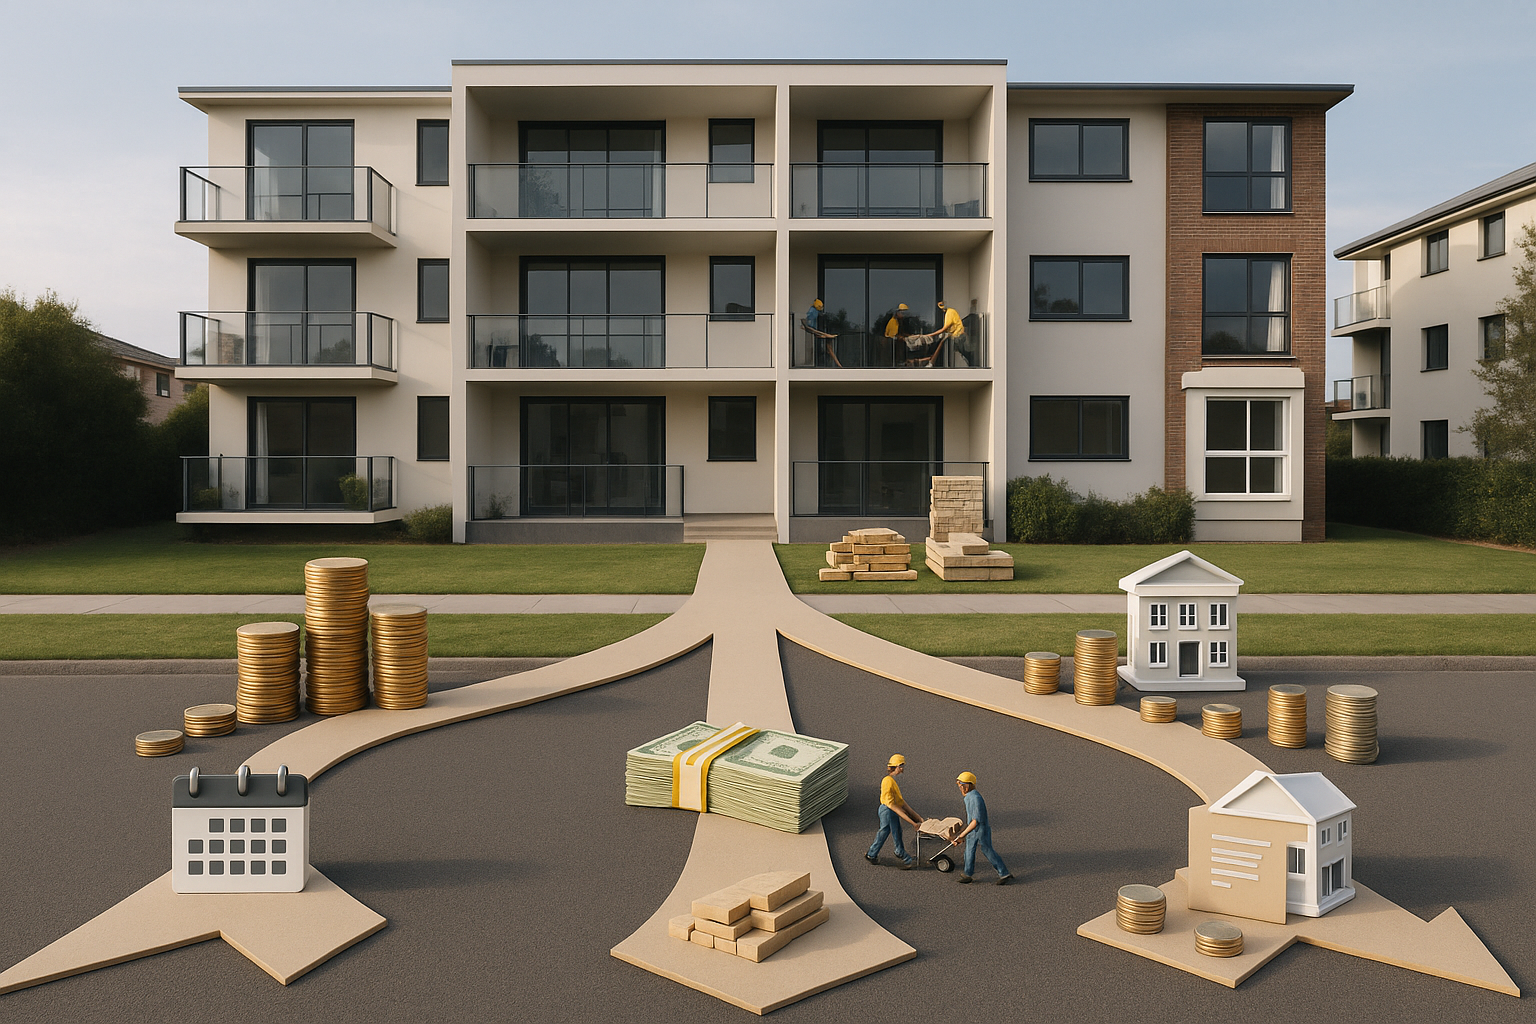
The three main funding paths in plain language
1. Higher ordinary levies
This means permanently increasing the regular admin/capital works fund contributions and paying for works out of accumulated balances.
Pros
- No external debt, no interest.
- Cleaner balance sheet – may appeal to some buyers and valuers.
- Works well for smaller, planned projects with long lead times.
Cons
- Slow: you may need years of higher levies to build the cash.
- Doesn’t work where repairs are urgent or compliance‑related.
- Politically hard – owners feel the increase immediately and permanently.
Best for: predictable, non‑urgent upgrades (e.g. long‑planned lift upgrade in 5+ years) where you can stage contributions.
2. Special levies
Special levies are one‑off or staged extra contributions voted by the owners corporation to fund specific works.
Pros
- No interest cost.
- Clear start and end – levy is linked to a defined project.
- Simple to explain: “Each lot pays $X by Y date.”
Cons
- Cash shock for owners; some will need to refinance or use personal loans.
- Higher risk of arrears and forced sales for stretched owners.
- Politically ugly – expect pushback, especially in investor‑heavy buildings.
Best for: modest works where most owners can handle a one‑off hit, or where the scheme wants to avoid debt entirely.
3. Strata building loans
A strata loan is borrowed by the owners corporation and repaid through levies over time instead of upfront contributions.
(If you need the mechanics, see Strata Loans Explained: Structures, Rules And What Lenders Really Want.)
Pros
- Works start quickly – crucial for fire, cladding or waterproofing issues.
- Spreads cost across current and future owners over 10–15 years.
- Softer cashflow per quarter vs a large special levy.
Cons
- Interest and fees increase the total project cost.
- Levies rise for years; impacts affordability and resale.
- Lender covenants (e.g. minimum levies, arrears triggers) need managing.
Best for: large, urgent or compliance‑driven works where many owners can’t pay a big lump sum.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Talk to a CPA-certified broker
Free consultation, plain-English advice tailored to your situation.